
Startup selection criteria when pitches sound the same
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Three founders pitch you an AI recruiting tool. Each promises a huge market, faster hiring, and a better experience. The decks could almost trade logos.
You need a way to compare the businesses underneath those claims. A useful screening process makes the differences visible, gives promising founders a fair hearing, and identifies which uncertainty deserves your next hour of diligence.
Set your investment boundaries first
Startup selection criteria are the standards you use to decide which companies deserve a closer look. They cover the team, customer problem, market, product advantage, traction, and business economics.
Before comparing those qualities, decide whether the opportunity fits your investing plans:
- Stage and sector: The company's development stage and industry match the risks you intend to take.
- Check size: The amount fits your startup-investing budget without crowding out other investments.
- Time horizon: You can leave the money invested for years and afford to lose it entirely.
- Ability to assess it: You understand the core risks or have access to someone with the relevant expertise.
A company can be promising and still fall outside those boundaries. Passing for that reason keeps your portfolio within its intended boundaries.
Compare companies at similar stages. A prototype needs evidence that a problem is real and that the team can build. A company with paying customers should have evidence of continued use, renewals, and a repeatable way to acquire more customers. Hardware and regulated businesses may need technical or regulatory milestones before commercial traction is possible.
Round labels alone don't settle this. Two companies raising a seed round may have very different amounts of operating history.
Six startup selection criteria that reveal real differences
Use the same six criteria across comparable pitches. For each one, record the founder's claim, the evidence supporting it, and the biggest unanswered question. A polished answer without supporting evidence stays an open question.
1. Founder insight and ability to execute
An earned secret is a useful insight the founders gained through direct experience with the problem. It might come from doing the customer's job, building an earlier product, or spending months observing a workflow.
A former recruiter might know that hiring stalls because managers disagree about requirements before interviews begin. That insight could lead to a different product than another resume-ranking tool.
Ask what the founder learned, how they learned it, and what they changed because of it. Then connect that insight to execution. The team needs someone who can build the product, someone who can reach customers, and a workable way to make decisions together.
In a 2016 investor survey, 885 institutional venture capitalists placed more importance on the management team than on product or technology. That describes investors' preferences; it doesn't establish that an impressive résumé predicts success.
We care about what a founder did with their experience. Our guide to evaluating early-stage founders goes deeper on working relationships, references, and decision-making.
2. A specific customer with an urgent problem
“Every business hires” doesn't identify the first customer. “Regional staffing agencies losing placements because candidate paperwork takes too long” gives you a buyer, a workflow, and a cost.
Separate the person using the product from the person paying for it. Then establish what happens today when the problem goes unsolved.
Useful evidence includes an existing workaround, spending on an inferior solution, a paid pilot, or customers repeatedly giving the team access to their workflow. Compliments and hypothetical willingness to buy carry less weight than those commitments.
Ask the founder to describe a recent customer interaction, including an objection or rejection. Specific friction is more informative than a slide full of positive interview summaries.
3. A focused starting market with room to expand
A wedge is the narrow customer segment or use case where a startup starts. A good wedge gives the team a reason to win its first customers and a plausible route to a larger business.
Start with reachable buyers and what they could reasonably pay. A giant industry-spending figure doesn't show how much of that spending the startup can capture.
For a recruiting company, staffing agencies might be the starting point. Expansion into employers' internal hiring teams would require different buyers, integrations, and sales processes. Treat each expansion as another assumption that needs evidence.
The selection question is whether the initial segment can support meaningful progress, and whether success there creates an advantage in the next segment. A narrow launch with no credible expansion path may suit a small business better than a venture-backed startup.
4. Differentiation that changes customer behavior
Founders should be able to name their competition, including spreadsheets, internal tools, and doing nothing. Understanding those alternatives helps them explain why customers would switch.
At Hustle Fund, we look for that competitive self-awareness. The useful follow-up is what the team does differently because it understands the market.
“Uses AI” is a feature description. A product that handles a specific workflow with less setup, reaches buyers through a trusted channel, or has permission to use valuable customer data has a more concrete advantage.
Distinguish an advantage today from one that could become harder to copy. A workflow integration might help win a pilot; accumulated customer relationships or specialized data might strengthen that position later. Early-stage companies rarely have a fully developed moat, an advantage competitors struggle to overcome.
Ask why a customer chose this product over the closest alternative, and what a competitor would need to reproduce that benefit.
5. Traction that shows continued demand
Traction is evidence that the company is making progress with customers. Compare the quality of that progress as well as its size.
A waitlist, a free trial, a paid pilot, and a renewal are different commitments. Keep them separate. For products with recurring use, examine groups of customers who started at the same time and whether they keep using or paying for the product.
Revenue also needs context. One large services contract is different from repeat product sales. A customer gained through a founder's personal relationship is useful early evidence, but it leaves a question about how the company reaches the next customer.
A founder who can explain cancellations, inactive accounts, and failed sales has material you can evaluate. A headline growth number without those details gives you less to work with.
6. A business model and funding plan that can support the next milestone
Identify who pays, what they pay for, and what it costs to serve them. For an AI product, that includes computing costs and any human work needed to deliver reliable results.
Early unit economics, the revenue and costs associated with serving a customer, will be incomplete. Look for a credible explanation of which costs fall as the product improves and which costs grow with usage.
Then connect the raise to a milestone. The company might need to turn pilots into renewals, demonstrate technical feasibility, or acquire customers beyond the founders' network. Its spending plan should provide enough runway, the time before its cash runs out, to pursue that milestone.
Be cautious when the plan depends on raising another round before the team can learn whether the current approach works.
Build an evidence card for every pitch
Keep a short note for each criterion using three fields:
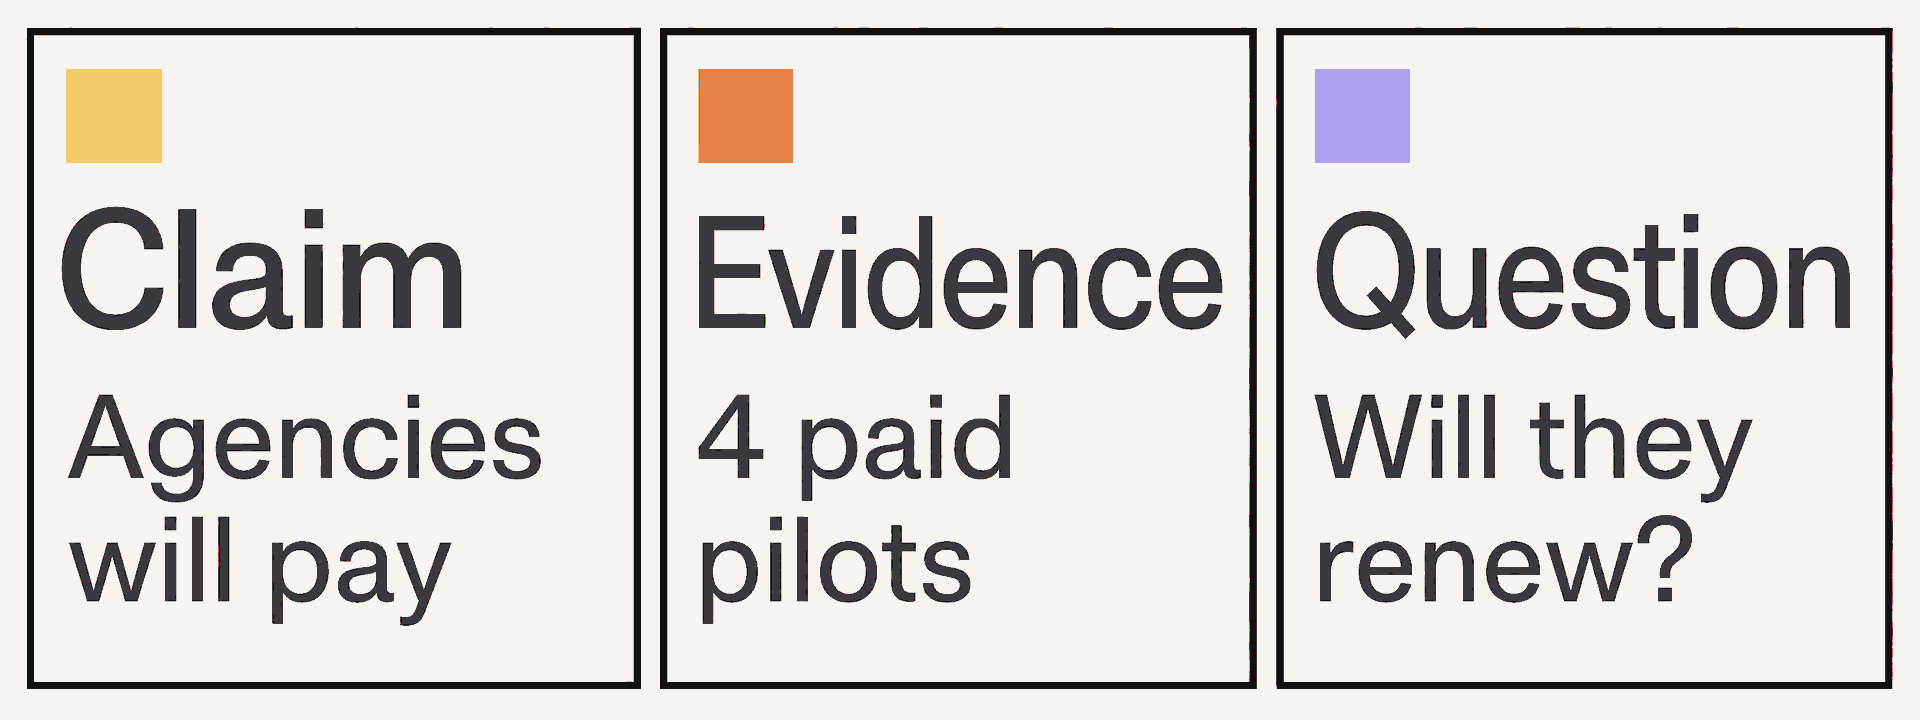
- Claim: What must be true for the investment case to work?
- Evidence: What has happened that supports or contradicts that claim?
- Open question: What remains unknown, and could it change your decision?
Four paid pilots in a hypothetical example support the claim that agencies will spend money on the problem. Whether they renew remains a separate question.
Our co-founder Elizabeth Yin writes in Democratizing Knowledge (2021), “The more disciplined you are in your thought process/rubric, the more you can improve over time.” Keeping these fields separate gives you something concrete to revisit when new information arrives.
Use plain assessments such as supported, untested, or contradicted. An untested assumption is different from evidence that customers reject the product. Avoid adding everything into a single score that lets an exciting market cancel out a serious integrity concern.
In Angel Squad, we share founder pitches and investment memos alongside education and peer discussion. Comparing your reasoning with our investment thesis and other members' questions helps expose assumptions you might have missed.
Compare two pitches using the same criteria
Consider this hypothetical screening example. Both companies describe themselves as AI recruiting platforms, and both have a product in customers' hands.
- Company A: Two technically experienced founders target employers of every size. They have 2,000 free accounts, but haven't separated active users from signups. Their acquisition plan is paid advertising. Pricing and the cost of human support remain unresolved.
- Company B: A former staffing-agency operator and a technical co-founder focus on candidate onboarding for regional agencies. Four agencies pay for pilots. Three use the product weekly; one has stopped because it doesn't fit the agency's workflow. Sales have come through the operator's network. Customers report less paperwork, but there is no renewal history yet.
Company B gives you a clearer starting point for further diligence. Its insight, customer, and workflow are specific, and its traction includes payment and repeated use. The inactive pilot also identifies a concrete product limitation.
Its unresolved risks are substantial. The team still needs to establish whether agencies renew and whether it can sell beyond the founder's contacts. Company A may have a valuable insight that its deck hasn't explained, so free-account totals alone don't justify dismissing it.
The next questions differ:
- For Company A: Which customer segment uses the product repeatedly, and what problem brings those users back?
- For Company B: Why did the fourth agency stop, and what evidence supports sales to agencies outside the founder's network?
This comparison earns Company B more attention. It doesn't settle an investment decision. Price, terms, customer evidence, and founder diligence can still change the outcome.
PunchUp Live shows what a specific wedge looks like
PunchUp Live is a real example from our portfolio. It was founded by Danny Frenkel and Alex Dajani, formerly at Meta.
In an August 2025 interview, Frenkel described a gap in live entertainment: artists market shows, ticketing platforms handle purchases, and venues host performances. Artists have limited visibility into what drives ticket sales across that fragmented process.
The team started with comedy. Dajani described comedy as its focus at the time, while identifying potential applications for musicians and podcasters. Frenkel also explained that performers needed industry representation, such as a manager or agent, to join its professional network.
That gives an investor several specific claims to examine: a defined customer group, a problem tied to revenue, a focused entry point, and a potential distribution channel through representatives. It also leaves real questions about repeat use, measurable sales improvements, and the economics of serving performers and venues.
On June 17, 2025, PunchUp announced a seed round of $2.3 million led by Social Leverage, with our participation. That is a historical financing milestone. It doesn't establish investment returns or prove that the original selection thesis was correct.
The useful lesson is how much more clearly you can assess a company once “tools for creators” becomes a particular customer, workflow, and route to market.
Decide what deserves more diligence
After screening, choose one of three next steps:
- Proceed: The company fits your boundaries, has a credible investment case, and the remaining questions deserve deeper work.
- Wait: A specific missing milestone could change your view. Name it, such as a pilot renewal or a technical demonstration, rather than asking for “more traction.”
- Pass: The opportunity falls outside your plans, evidence undermines the core thesis, or a serious unresolved concern makes the risk unacceptable.
Screening narrows your attention. Before investing, the work expands to customer and founder references, financial records, ownership records, and the terms of the actual offering. Our angel diligence checklist covers that next stage.
Keep the portfolio in view throughout. As Elizabeth Yin writes in Democratizing Knowledge (2021), “Select a portfolio.” Most startup bets may fail, and a thoughtful selection process still leaves you exposed to uncertainty and luck.
If you want to practice evaluating deals with our investment memos, education, and fellow investors, apply to Angel Squad.
This is educational content, not investment, legal, or tax advice. Startup investments are speculative, illiquid, and long-term, and you can lose your entire investment. Seek independent advice from qualified financial, legal, and tax professionals before investing.











