
Fund wind down: a practical guide for venture managers
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
This material is for education only. It is not legal, tax, investment, accounting, or valuation advice. Fund duties and distribution results depend on governing documents, side letters, applicable law, portfolio transfer restrictions, fees and carry, taxes, cap tables, valuation policy, and timing. Private funds and startup securities are speculative, illiquid, long-term investments with a risk of total loss. Past results and current marks do not guarantee future results. Rely on the fund’s governing documents and qualified independent legal, tax, accounting, and investment advisers.
Closing a venture fund is part of running one. The hard case arrives when the fund’s term is ending while private shares, contingent claims, unpaid expenses, and impatient limited partners (LPs) remain. A good fund wind down gives each of those loose ends an owner, a decision rule, and a documented path to closure.
What a fund wind down actually means
Several events get blurred together in casual conversation. They are different:
- The investment period ends. The fund generally stops making new investments, subject to the limited partnership agreement (LPA).
- The fund term approaches its end. The manager decides whether to use an available extension or begin winding up.
- A dissolution event starts the wind-up. For many structures, dissolution changes the entity’s purpose to settling its affairs. It does not make the entity disappear immediately.
- The fund winds up or liquidates. The team realizes or transfers assets, settles liabilities, calculates distributions, and finishes reporting.
- Cancellation or termination ends the entity. This is the formal endpoint after the fund has dealt with its remaining property and obligations.
The LPA controls much of that sequence. Closed-end private funds commonly have an 8-to-12-year life, and extensions are widely used to handle illiquid holdings, unresolved claims, or poor sale conditions. The exact term, extension rights, fees, consent thresholds, and winding-up authority come from the fund’s documents, not a universal venture rule. Fund lifespan terms vary by strategy and structure.
A successful fund may still need an extension or a long wind-down. PitchBook found that more than 40% of unicorns had spent at least nine years in a VC fund by late 2024. A valuable private company can simply outlive the vehicle that first backed it.
The venture fund wind-down process
The work runs in four broad phases: approve the plan, map the assets and claims, sell or transfer what remains, then distribute proceeds and close the entity.
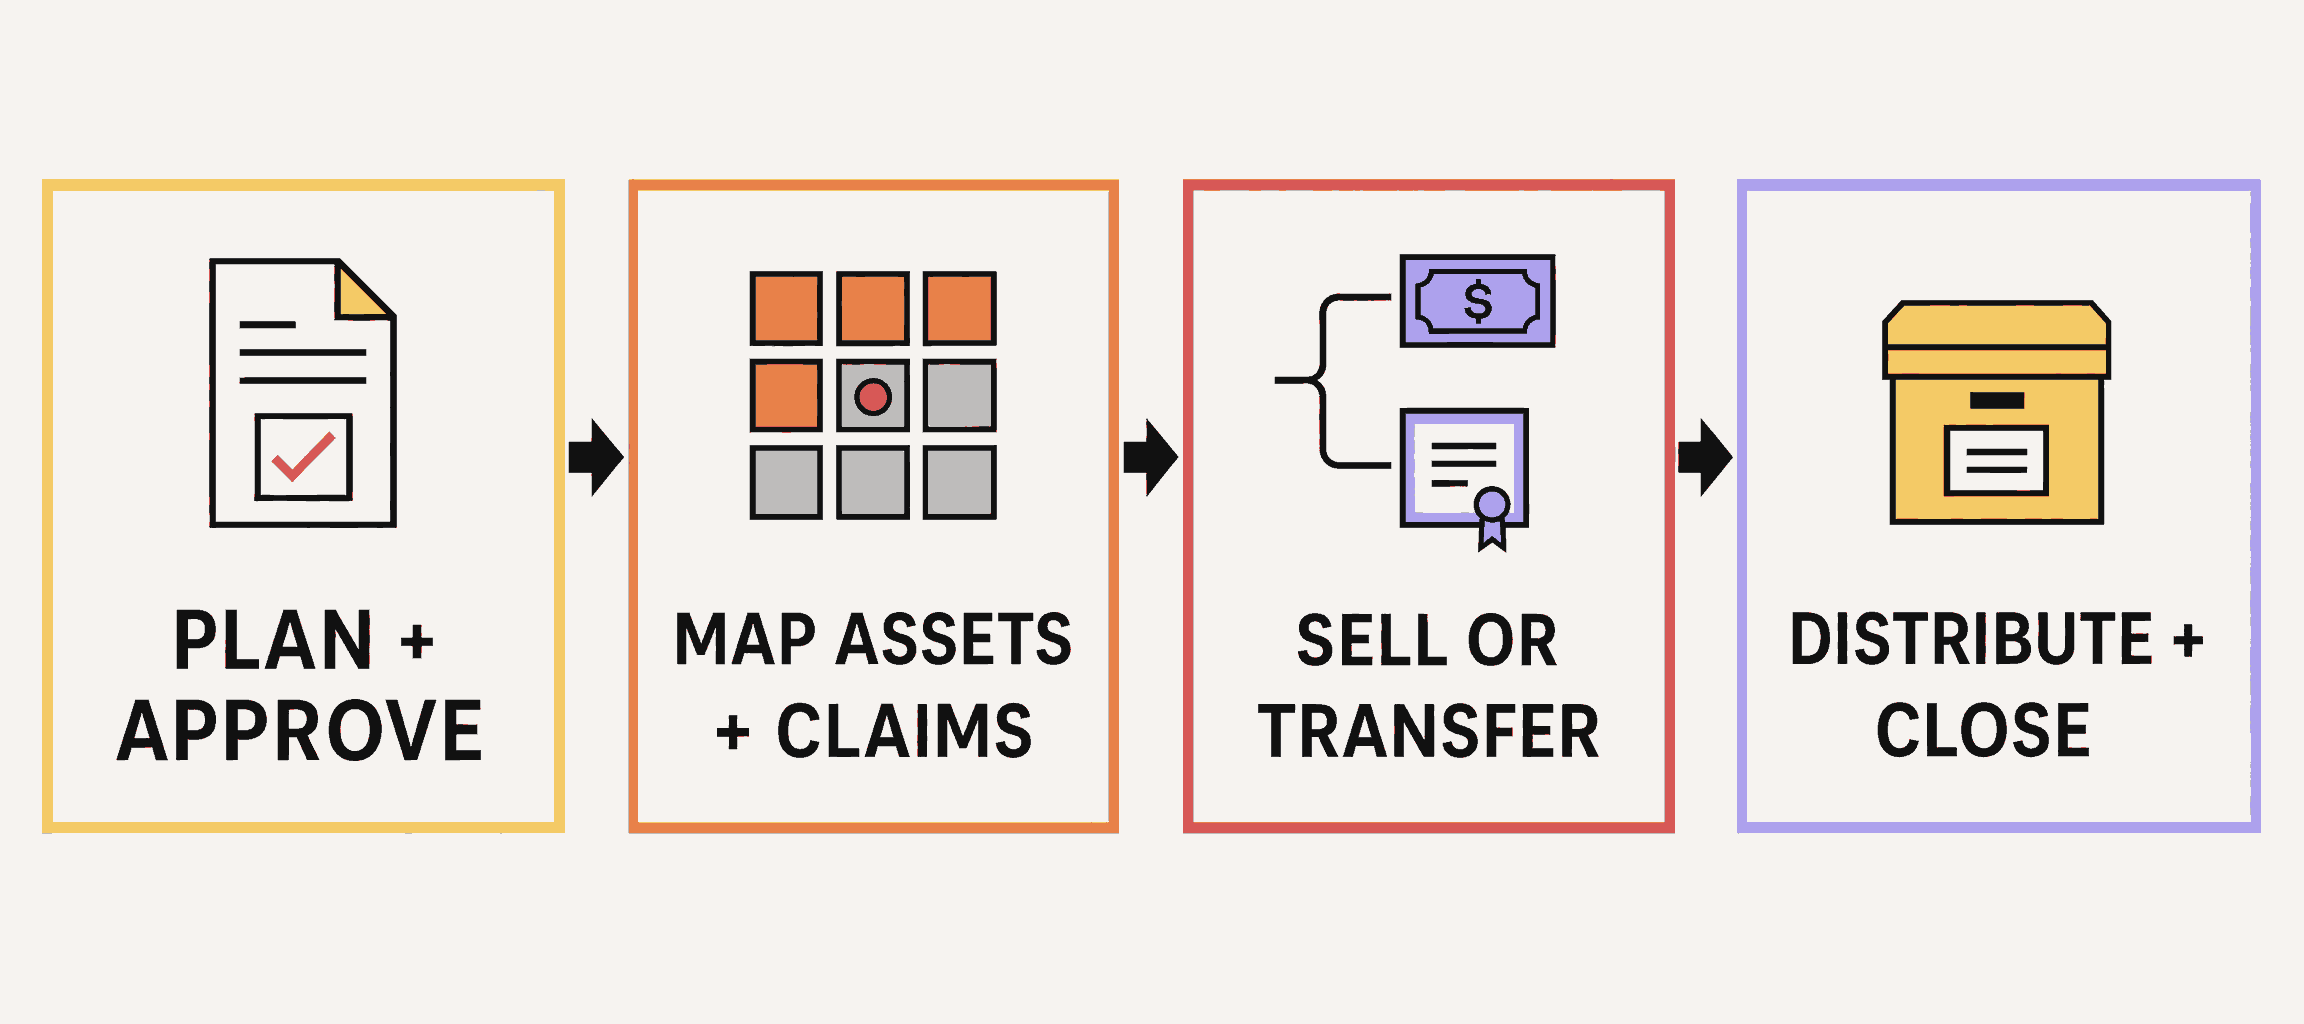
Inside those phases, fund managers should work through seven steps.
1. Start with the documents
Build an obligations register before setting a date or calling a buyer. Review the LPA, private placement memorandum, subscription agreements, side letters, advisory committee provisions, management-company agreements, and every relevant portfolio-company document.
Capture the clauses that answer these questions:
- What event starts dissolution or winding up?
- Who can approve an extension, asset sale, in-kind distribution, or continuation vehicle?
- Do management fees change during an extension or liquidation period?
- How should the fund value private securities for a transfer or distribution?
- What reserves, indemnities, carried-interest adjustments, or clawbacks may survive?
- Do stockholder agreements, rights of first refusal, or company consents restrict transfers?
Turn each answer into an owner, deadline, required approval, and evidence file. This register becomes the spine of the wind-down plan.
2. Keep the right team in place
Winding down still requires people who understand the fund. Assign a lead and confirm responsibilities across the general partner (GP), fund administrator, legal counsel, tax adviser, auditor, valuation provider, banking partner, and any secondary-market adviser.
Our co-founder Eric Bahn calls fund back-office work “utterly draining.” The tail can be worse because fee income may be falling as experienced staff move on. Decide early who will maintain the books, answer LP questions, collect portfolio data, approve wires, manage records, and sign final filings.
Keep a written decision log. It should record the alternatives considered, conflicts identified, valuations used, approvals received, and reason each route was chosen.
3. Map every asset and claim
A fund cannot close around an incomplete inventory. Reconcile the administrator’s ledger, bank and custody records, cap table evidence, and the manager’s portfolio tracker.
Map:
- cash, public securities, private shares, Simple Agreements for Future Equity (SAFEs), convertible notes, warrants, escrow rights, and earnouts;
- written-off companies that still exist legally or could make a later distribution;
- unpaid administration, audit, legal, tax, insurance, registered-agent, and banking costs;
- contingent liabilities, indemnities, pending disputes, tax exposures, and potential clawback amounts; and
- the records and contractual duties that must survive the entity’s cancellation.
Then classify each asset by transferability, expected time to liquidity, valuation confidence, likely sale costs, approval requirements, and ongoing carrying cost. A single “remaining NAV” figure hides the decisions that matter.
4. Give LPs a real plan
Send an initial notice once the GP has a credible proposal and the disclosure timing has been cleared with counsel. Explain:
- why the wind-down or extension is happening;
- which document provisions authorize it;
- what assets and liabilities remain;
- which liquidity routes are under review;
- what conflicts, fees, carry, and valuation questions exist;
- which LP or advisory committee approvals are required; and
- when investors should expect the next update, distributions, statements, and tax documents.
Share decision dates separately from hoped-for liquidity dates. A portfolio company can delay a transfer, exercise a contractual right, or change its own exit plan. LPs can handle uncertainty better than a deadline that keeps slipping.
5. Choose an exit route asset by asset
The right answer may differ within one portfolio. Introduce each option clearly before asking LPs to approve a package.
- Use an extension. This fits when the LPA permits it, the fund can cover the tail, and a plausible value-creating milestone is close enough to justify more time. State what the extension is meant to accomplish, its cost, who consents, and what happens if the milestone never arrives.
- Sell through a secondary transaction. A sale converts the position to cash and can simplify the fund’s final distribution. Price discovery, buyer diligence, transfer restrictions, rights of first refusal, taxes, transaction costs, and conflicts can reduce the apparent benefit. Run a documented process rather than treating the latest financing mark as cash value.
- Distribute the asset in kind. The fund transfers securities to LPs instead of selling them. This can preserve future upside, yet it shifts custody, tax, eligibility, cap-table, and liquidity work to each recipient. The LPA and company documents must allow the transfer, and each LP needs a workable way to receive the asset.
- Move selected assets to a continuation vehicle. Existing LPs may receive a choice to sell, roll into the new vehicle, or use a combination. The same GP sits on both sides of the transaction, so rationale, price, process, fees, carry, time, and conflicts need unusually clear treatment. ILPA’s continuation-fund guidance centers alignment, transparency, and enough information for LPs to make an informed choice.
- Document a write-off or abandonment. This route applies when an asset has no realistic path to value and the relevant documents, law, accounting policy, and tax treatment support it. A zero mark by itself does not settle ownership or close the entity.
Use the same decision test for every position:
- Authority: Is the route allowed, and whose approval is required?
- Net value: What remains after time, fees, taxes, discounts, and operational cost?
- Optionality: Can LPs choose liquidity or continued exposure?
- Transferability: Can the company and every intended recipient complete the transfer?
- Fairness: How was value established, and how are conflicts managed?
- Tail risk: What claims, escrows, or later proceeds may remain after the transaction?
As our co-founder Elizabeth Yin writes, “Going back to first principles is critical since the market always changes and evolves.” At fund end, that means comparing the expected net result of holding, selling, and transferring. Habit is not a wind-down strategy.
6. Settle liabilities before final distributions
Build a closing cash budget. Include final audits, tax work, administration, legal bills, insurance, filing fees, banking, record retention, and a reserve for known or reasonably foreseeable claims. Reconcile the waterfall, carried interest, previous distributions, and any clawback or giveback mechanics before releasing the final amount.
The order matters. Delaware’s limited-partnership statute, for example, requires a winding-up partnership to pay or make reasonable provision for claims before distributing remaining assets to partners. It also addresses contingent and future claims based on facts known at dissolution. That statutory winding-up order is a useful reminder even when a fund is formed elsewhere: cancellation should follow the liability analysis.
Cash may go out in tranches while a reserve stays behind. Tell LPs what portion is being held, why, who controls it, what could consume it, and when the unused balance may be released.
For U.S. partnership funds, the tax close follows its own timetable. The IRS says a partnership’s tax year ends when it terminates and winds up its affairs. Coordinate final returns and investor tax reporting with the actual legal and operational sequence under the Form 1065 instructions.
7. Finish dissolution, cancel, and archive
Once assets are realized or transferred and liabilities are paid or reserved for, complete the required entity, regulatory, tax, licensing, and notice filings. Close vendor contracts and bank or custody accounts only after the final money and records are secure.
Create a durable archive containing:
- governing documents, consents, notices, and the decision log;
- valuation materials and transaction files;
- final capital-account, waterfall, wire, and distribution records;
- tax returns, financial statements, audit materials, and regulatory filings; and
- a contact and custody plan for later claims, escrows, tax questions, or surprise proceeds.
The certificate of cancellation is a milestone. The job ends when the remaining obligations have an enforceable home and the records can support what the GP did.
What LPs should ask during a wind-down
LPs should receive enough information to understand the manager’s decision and its effect on their own liquidity, taxes, and continuing exposure. Ask six direct questions:
- Which LPA provisions govern the term, extension, wind-up, valuation, and approvals?
- What assets and claims remain, and when were the private positions valued?
- What alternatives did the GP compare for each material asset?
- What fees, carry, transaction costs, taxes, and reserves affect the amount or timing of distributions?
- What conflicts exist, and what independent price discovery, opinion, or LP advisory committee process addresses them?
- What will I receive, what actions must I take, and which events could change the schedule?
Silence is not evidence of misconduct. It is evidence that the communication plan needs work. LPs should know when the next answer is coming even when the final number is still unknown.
Design the ending before Fund I closes
The least painful wind-down starts at formation. Give the LPA workable extension, valuation, transfer, reserve, expense, and approval mechanics. Keep cap table evidence and portfolio consents current. Budget for the tail. Maintain an LP communication cadence before a problem appears. Choose service providers that can support the full fund life rather than the exciting deployment years alone.
And be honest about the commitment. A fund is a long-lived operating system for other people’s money. Investors who want more startup-investing reps before accepting that full stack can learn through a community, discuss deals with peers, and see how experienced investors frame risk.
If that is your next step, apply to Angel Squad and build your early-stage investing judgment before you build a fund around it.











