
Pro rata rights: meaning, math, and when to exercise
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
This is educational information, not legal, tax, or investment advice. Pro rata rights and investment eligibility depend on the governing documents, the offering, and applicable law. Startup investments are speculative, illiquid, long-term, and can result in a total loss. Seek independent review from qualified legal and tax professionals.
A pro rata clause looks simple until a financing notice lands in your inbox. Then the real questions start: How much can you buy? Which round does the right cover? When does it expire? And is exercising it a good use of your next dollar?
What are pro rata rights?
Pro rata rights give an existing startup investor the option to buy part of a future financing so they can maintain their ownership percentage. “Pro rata” means “in proportion.” These rights are also called participation rights or preemptive rights in some agreements.
If you own 10% of a startup before a new round, your pro rata right may let you buy 10% of the securities sold in that round. Full participation can keep you at 10%. Passing can reduce your percentage because the company issues new shares to other investors.
Three details matter:
- It is a right, not an obligation. You can decline the investment.
- It requires more capital. Your original check does not protect your percentage by itself.
- The contract controls. Your agreement defines the calculation, covered securities, deadlines, exceptions, and termination events.
Even full participation does not promise protection from every source of dilution. An option-pool increase, SAFE conversion, employee grant, or other excluded issuance can still change your percentage. The right covers only what the signed clause says it covers.
That is why “I have pro rata” is the beginning of the analysis. It is not the answer.
How pro rata rights work
A typical process has four steps:
- The right is documented. In a priced round, it may sit in an investors’ rights agreement. A Simple Agreement for Future Equity (SAFE) investor may receive it in a separate side letter.
- The startup plans another financing. The company sends eligible investors a notice describing the security, price, terms, and amount available.
- The investor chooses. The agreement provides an exercise window. The investor elects all, part, or none of the permitted allocation, depending on the document.
- The round closes. An investor who participates pays for new securities. An investor who passes keeps the securities already owned, but usually holds a smaller percentage after the new issuance.
The current NVCA model agreement shows how detailed the priced-round version can become. It uses a “right of first offer” for defined Major Investors, gives them 20 days after the offer notice to make the first election, and adds a 10-day window for fully participating investors to request unsubscribed securities. It also excludes specified issuances and contains termination language.
Those are model terms, not a universal market deadline. Your executed documents can use a different timetable, calculation, or scope.
Why investors want the right, and why founders limit it
An investor may value pro rata rights for three reasons:
- Access. A contractual allocation can preserve room in a later round when new investors want the available shares.
- Ownership. Participation can maintain the ownership percentage measured by the agreement. Depending on the capital structure, that percentage can affect economics or voting power.
- Threshold-dependent rights. Some information, governance, or other rights depend on continuing to qualify as a Major Investor.
A lower ownership percentage is not automatically a bad outcome. The company receives fresh capital, and a smaller share of a more valuable company can be worth more. Pro rata rights preserve the choice to invest. They do not make dilution inherently harmful.
Founders have a different constraint: every share reserved for an existing investor leaves less room for a new lead or strategic investor. Broad rights can also create more notices, elections, waivers, and cap-table work in every financing. That is why eligibility thresholds, excluded issuances, and time limits matter to both sides.
A pro rata calculation with clean share math
Here is a hypothetical, simplified example. It covers one company, one investor, and one priced equity round. It assumes every new share has the same price and ignores option-pool changes, SAFEs, convertible notes, warrants, multiple share classes, transaction costs, fees, carry, and taxes.
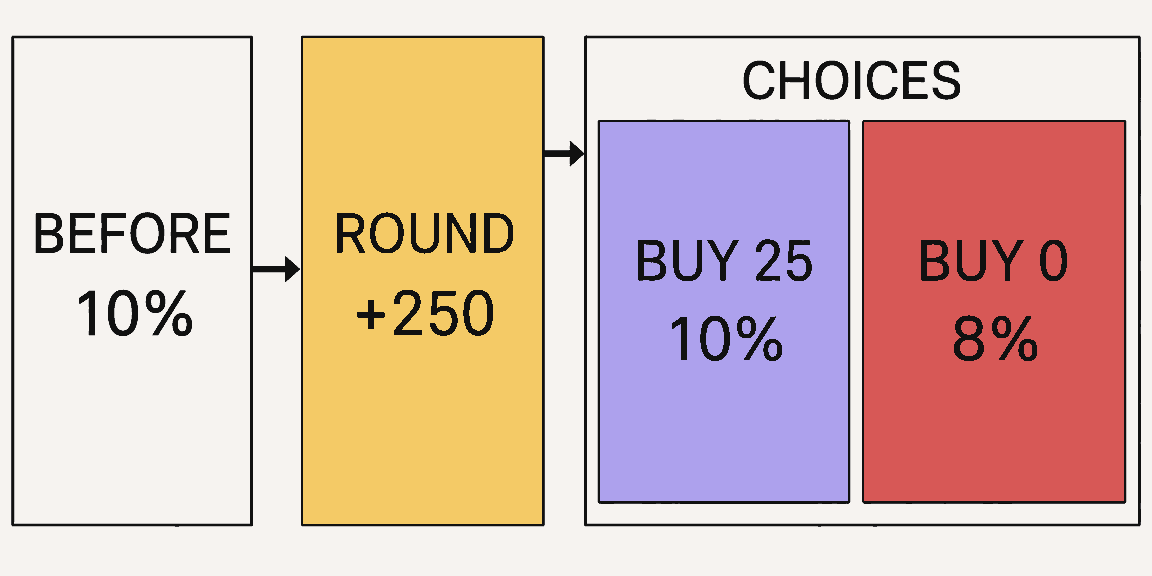
You own 100 of 1,000 shares, or 10%, immediately before the round. The company will issue 250 new shares in total, including shares reserved for eligible existing investors.
Your pro rata allocation is:
10% × 250 new shares = 25 shares
If you buy all 25 shares, you own 125 of the 1,250 post-round shares. That is still 10%.
If you pass and all 250 shares go to other investors, you own 100 of 1,250 shares. Your ownership falls to 8%.
The check-size shortcut is just as simple when the announced round amount includes your participation:
Pro rata check ≈ pre-round ownership percentage × total new-money round
If you own 3% and the company is raising $4 million in total, your estimated allocation is $120,000.
Treat that as an estimate. If the quoted “new money” excludes your check, the formula needs a gross-up:
Required check ≈ ownership percentage ÷ (1 − ownership percentage) × other investors’ new money
At 3% ownership, a $4 million round that excludes your participation produces an estimated check of 3% ÷ 97% × $4 million = $123,711, rather than $120,000. Your check increases the final round total too.
If SAFEs convert or the option pool expands at closing, the percentage used in the contract may differ from the percentage shown in a portfolio dashboard. Request the financing notice and pro forma capitalization table, then apply the definition in your signed agreement.
In Hustle Fund’s fundraising guide, our general partner Eric Bahn warns about stacked pre-money SAFE valuations: “It is really easy to mess up these calculations”—a useful reminder that a headline ownership percentage is only as reliable as the cap table beneath it.
Where pro rata rights appear
Priced equity rounds
Investors in a preferred-stock financing often receive participation rights through an investors’ rights agreement. Eligibility may depend on meeting a Major Investor threshold, and that status can depend on how many shares the investor continues to hold.
A priced-round right may cover multiple future issuances and last until an initial public offering, acquisition, loss of eligibility, or another termination event. It can also exclude employee equity, acquisition consideration, stock splits, strategic issuances, or other categories of securities.
SAFEs
Pro rata rights are not automatically included in every SAFE. YC’s current U.S. post-money SAFE materials put the right in an optional side letter, separate from the SAFE itself.
Scope matters here. YC’s U.S. side letter covers the investor’s pro rata share of Standard Preferred Stock sold in the next Equity Financing. It ends at that financing’s initial closing, or earlier upon specified liquidity or dissolution events. It is a right for one conversion round, rather than a perpetual pass into every later round. Other side letters may use different language.
If you need a refresher on how the instrument affects ownership, read our guide to pre-money and post-money SAFEs.
SPVs
An investment through a special purpose vehicle (SPV) adds another layer. The vehicle or its manager may hold and administer the right, while the underlying investor owns an interest in the vehicle. Review both the startup’s agreement and the SPV documents before assuming you personally control a follow-on allocation.
Seven terms to inspect before relying on the right
The words “pro rata” do not tell you enough. Find these terms in the executed documents:
- Eligible holder. Does the right belong to every investor, only Major Investors, a named investor, or an investment vehicle?
- Calculation base. Which outstanding and convertible securities count in the numerator and denominator? Is ownership measured on an as-converted or fully diluted basis?
- Covered financing. Does the right apply only to the next priced round or to multiple issuances?
- Excluded securities. Employee grants, acquisition shares, equipment financings, strategic issuances, and other transactions may sit outside the clause.
- Notice and deadline. How will the company notify you, and how many days do you have to respond and fund?
- Amount and priority. Can you buy “up to” your allocation, take unsubscribed shares, or buy more than pro rata? Can the company reduce the allocation?
- Transfer and termination. Can the right move to an affiliate or SPV? Does it end after a pass, below an ownership threshold, at an IPO, or at a sale of the company?
Also check whether an amendment or waiver can be approved by a majority of similarly situated investors. A side letter can look personal while still allowing group action to change it.
What pro rata rights do not give you
Similar terms often get blended together. Keep the rights separate:
- Anti-dilution protection adjusts preferred-stock conversion economics in specified down-round scenarios. Pro rata rights require a new investment to maintain percentage ownership. Our guide to anti-dilution provisions explains that distinction.
- Super pro rata rights can let an investor buy more than the amount needed to hold the same percentage. Ordinary pro rata rights generally cap participation at the investor’s proportional share.
- Preemptive rights and rights of first offer may describe the same future-issuance mechanism as pro rata rights, or a broader one, depending on the definitions. The heading does not settle the scope.
- A right of first refusal usually concerns a proposed transfer of existing shares. Pro rata rights usually concern newly issued securities in a company financing.
- Information or board rights govern access and oversight. Pro rata rights alone do not provide either one.
Most of all, pro rata rights do not guarantee a good investment. They preserve access to a financing. The new price, company progress, security terms, and portfolio fit still determine whether that access is worth using.
Should you exercise your pro rata rights?
Treat the follow-on as a fresh investment decision. Familiarity with the company can improve your judgment, but it can also create commitment bias.
Work through these questions:
- What has changed since your first check? Compare actual progress with the milestones in your original investment memo. Look at customer behavior, retention, revenue quality, hiring, burn, runway, and execution.
- What are you buying now? Review the price, share class, liquidation preference, governance rights, and any senior securities. A stronger company can still be unattractive at the wrong terms.
- What does the full cap table show? Model your ownership after SAFE and note conversions, the option-pool increase, and the whole round. A headline round size rarely captures every moving part.
- What else could this money fund? Compare the follow-on with new startup investments, reserves for other portfolio companies, and keeping cash uncommitted.
- Can your portfolio absorb more concentration? Exercising shifts more capital into one company. Decide whether the potential upside justifies the added single-company exposure.
- Do you have time to decide well? Request the notice, pro forma cap table, current financials, round documents, and closing schedule early enough to review them.
Our co-founder Elizabeth Yin puts the capital-allocation point plainly: “Decisions are never in isolation - they are a comparison game.” A pro rata right creates a choice. It does not make the choice for you.
A practical pro rata checklist
When a follow-on notice arrives:
- Locate the executed agreement that grants the right.
- Confirm the holder, covered financing, calculation base, and termination language.
- Request the round notice, draft financing documents, and pro forma cap table.
- Recalculate the share allocation and required cash.
- Compare the new terms and company progress with your original thesis.
- Measure the check against your portfolio budget and concentration limits.
- Get independent legal and tax review.
- Submit the election and funds before the contractual deadlines.
- Save the signed closing documents and update your cap-table records.
The meaning is simple: pro rata rights let you protect your percentage by investing again. The decision is harder. Read the clause, calculate the real allocation, and compare the follow-on with every other use of your capital.
If you want to build that decision-making muscle alongside other active and aspiring angels, apply to Angel Squad.











