
Ecommerce Venture Capital: The Investor Exception Test
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
Ecommerce venture capital creates a hard question for investors: when is an online seller an outlier-scale company rather than a solid, capital-hungry business? The distinction affects what you ask, how you model risk, and whether equity is the right fuel. Let's build the decision from first principles.
Important: This material is educational only. It is not investment, legal, tax, accounting, or valuation advice. Private-company securities are speculative, illiquid, and long term, and you can lose all invested capital. Past results and current marks do not guarantee future results. Every outcome illustration is hypothetical and simplified, and actual results depend on governing documents, security terms, fees, expenses, carry, taxes, the cap table, dilution, valuation policy, timing, follow-on capital, and financing and exit conditions. Review the governing documents and seek advice from qualified independent professionals for your situation.
Ecommerce is a channel, not one business model
Calling a startup “ecommerce” tells you where a transaction happens. It says little about who holds inventory, what the customer repeats, or how the company gets paid. Start by placing the company in the right category:
- Inventory-owning brand or retailer. The company designs, sources, or buys physical goods, then sells them online. Direct-to-consumer brands sit here, though many also sell through wholesale or stores.
- Marketplace. The company connects buyers and sellers and earns a fee. It may avoid inventory risk, then face a different challenge: creating enough supply and demand in the same market at the same time.
- Commerce software or infrastructure. The company sells payments, logistics, storefront, data, or workflow tools to merchants. Its economics may resemble software or financial technology more than retail.
- Hybrid. Hardware, subscriptions, services, physical locations, proprietary data, and commerce can reinforce one another. The combination may create stronger retention or defensibility, along with more operating complexity.
The reluctance usually associated with ecommerce venture capital applies most directly to inventory-owning brands. Our earlier D2C investing guide explores that category in more depth. A marketplace or commerce-infrastructure startup deserves a different rubric.
Why venture funds need outlier-scale proceeds
A venture fund pools outside capital and invests across a portfolio. Some companies may fail completely. Others may return a modest amount. A small number of large outcomes can drive most of the portfolio's value.
This skew is often called the power law of venture returns.
That incentive explains our co-founder and General Partner Elizabeth Yin's blunt line in Democratizing Knowledge: “Investors are looking for THE VERY HIGHEST ROI opp. NOT great businesses.” ROI means return on investment. A VC rejection can reflect the fund's economics even when the underlying company could become profitable and durable.
Fund managers do not all require the same return from every company. Fund size, check size, ownership, reserves, stage, timing, and the rest of the portfolio change what counts as material. The shared question is probabilistic: can this investment produce enough proceeds, at a high enough probability, to justify its risk and matter to the portfolio?
For each plausible outcome, an investor can estimate a probability, multiply it by the proceeds the investor would receive after dilution, and add the results. Those estimates are uncertain. The exercise forces the investor to separate company exit value from investor proceeds and to see how heavily the case depends on a rare outlier.
A simplified hypothetical portfolio illustration
Status and scope: This is a hypothetical, simplified 10-company venture portfolio calculation dated September 8, 2026. It treats every modeled outcome as terminal and fully realized, with no unrealized value remaining.
Capital basis: The portfolio invests one equal unit in each company, 10 units total, with no follow-on investments. Each company has an independent illustrative outcome distribution: a 70% chance of 0x, a 20% chance of 1x, a 9% chance of 5x, and a 1% chance of 100x.
Basis and exclusions: Outcome multiples represent gross proceeds to the investor after an assumed dilution path. The illustration is before fund or special purpose vehicle fees, expenses, carried interest, and taxes. It excludes debt, liquidation preferences, option-pool changes, Simple Agreement for Future Equity (SAFE) instruments, notes, warrants, transaction costs, currency effects, and differences in exit timing. Real portfolios use uneven checks, correlated outcomes, follow-ons, and far less tidy probabilities.
The expected gross proceeds multiple is 1.65x: 70% × 0x + 20% × 1x + 9% × 5x + 1% × 100x. Yet the chance that none of the 10 companies reaches the 100x outcome is 0.99 to the tenth power, or about 90%, using the illustration's independence assumption. Expected value is a mathematical average across repeated imaginary portfolios. One actual portfolio gets one set of outcomes.
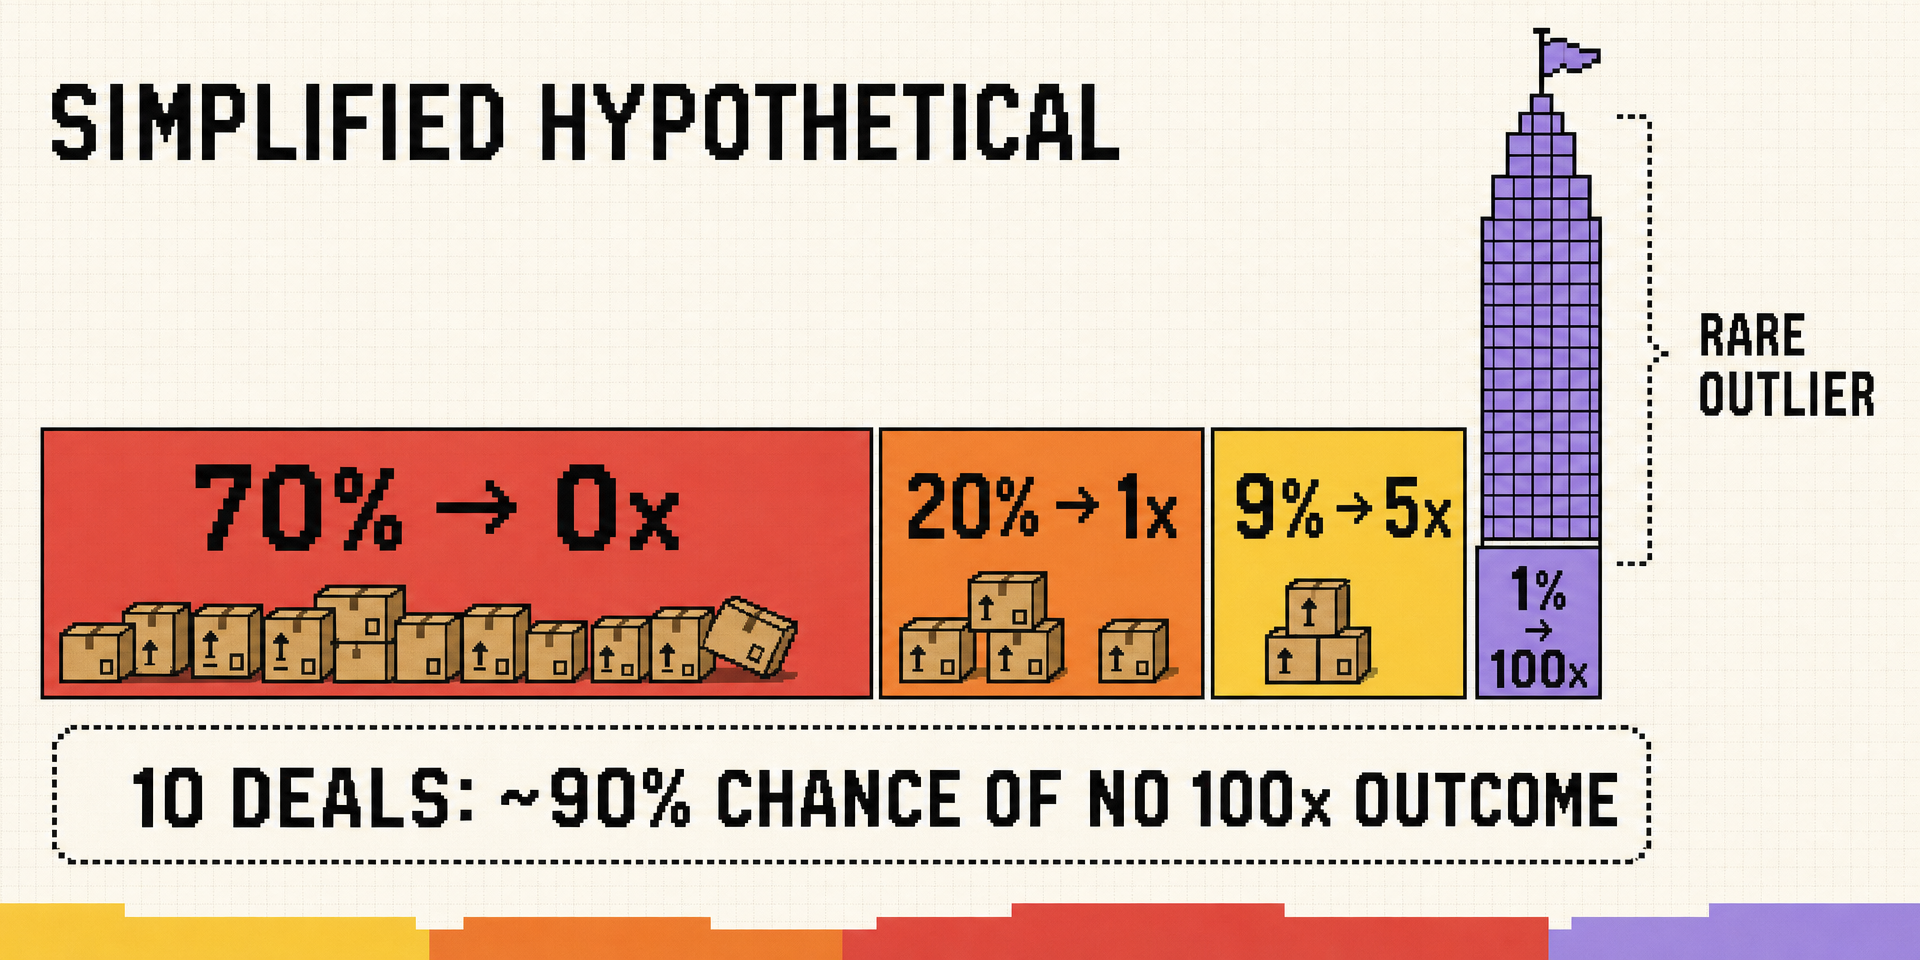
A fund therefore asks two questions: can this company produce proceeds material to the fund, and is that outcome plausibly reachable? Inventory, acquisition spending, and narrow exit options can reduce either side of that equation.
The ecommerce diligence stack
An attractive dashboard can hide weak cash generation. Rebuild the model from the order up, then connect it to customer cohorts, inventory, and a possible exit.
1. Gross margin
Gross margin is net revenue minus cost of goods sold, divided by net revenue. The definition looks simple. The accounting choices are not. Freight into a warehouse, duties, packaging, manufacturing labor, and inventory write-downs may sit in different places across companies.
Ask for monthly net revenue and cost of goods sold by product and channel. Reconcile gross sales to discounts, refunds, and net sales. Then identify why margin should improve or deteriorate as the business grows. Larger orders may reduce unit cost. Wholesale mix, promotions, new products, or more complex fulfillment may move it in the other direction.
Gross margin is the first pool of money available to pay for acquisition and operations. It does not show whether an order creates cash after the variable costs required to serve it.
2. Contribution margin
Contribution margin takes the order one layer deeper. Start with net revenue, subtract cost of goods sold, then subtract variable costs such as payment processing, pick-and-pack, outbound shipping, returns, and channel commissions. Some companies also subtract paid acquisition at this level. Use one definition consistently and state every included cost.
Review first orders and repeat orders separately. A heavily discounted first order may lose money and still work if later purchases arrive soon and carry healthy contribution. That case weakens fast when the repeat forecast relies on averages, old cohorts, or a few unusually loyal customers.
Growth with negative contribution before fixed overhead can consume more cash with every order. Scale helps only when a concrete cost or behavior improves.
3. Repeat purchase and retention
Retention should match how people naturally buy the product. A 30-day repeat rate is useful for a monthly consumable and almost meaningless for a mattress. Define the expected repurchase window before judging the cohort.
Request customer cohorts by first-purchase month. Track the share that returns, the timing of later orders, cumulative net revenue, and cumulative contribution profit. Split subscription renewals from one-off reorders, and split full-price customers from customers acquired through deep discounts.
Subscription enrollment is an intention. Successful renewals, low involuntary churn, and retained contribution profit are evidence. For infrequent products, look for expansion into adjacent purchases or services that fits the same customer relationship. Avoid inventing repeat behavior that the category does not support.
4. Customer acquisition cost and payback
Customer acquisition cost (CAC) is the sales and marketing cost required to acquire a new customer. A blended CAC can make paid channels look better when referrals, existing brand traffic, or wholesale customers enter the same denominator. Rebuild paid and blended CAC separately, and include creative, agency, influencer, and sales costs when they are part of acquisition.
Calculate payback from contribution profit, rather than revenue. Then compare the payback period with the company's cash cycle. A customer who repays acquisition spending in nine months can still strain a company that pays a supplier today, holds stock, and collects repeat contribution much later.
Check cohorts by channel and acquisition month. Ask what happens to CAC when spend doubles. Early performance in a new channel may reflect a small, eager audience that cannot absorb the next dollar at the same efficiency.
5. Inventory and working capital
An inventory-owning company often pays cash well before it makes a sale. Purchase-order deposits, production, ocean or air freight, warehousing, and final supplier payments can turn fast revenue growth into a cash squeeze.
Map the full cash conversion cycle. Review supplier terms, minimum order quantities, production lead times, inventory turns, stockouts, aged units, write-downs, and concentration by supplier and product. Compare the cash forecast with committed purchase orders, instead of relying on the current bank balance.
Also ask what type of capital funds each job. Equity may fit product development, a new channel, or technology with uncertain payoff. Repeatedly selling ownership to finance ordinary replenishment can make future dilution and fundraising needs hard to escape. Purchase-order finance, inventory facilities, or operating cash flow carry their own costs and risks, yet they may match predictable inventory more closely.
6. Fulfillment and returns
The sale is not finished when a carrier scans the package. Failed deliveries, customer support, exchanges, refunds, reverse logistics, damaged goods, refurbishment, and disposal can change the economics after revenue appears.
Segment these costs by product, channel, geography, and customer cohort. A product with fit, sizing, fragility, perishability, or cold-chain requirements deserves its own return and fulfillment model. Ask whether a returned item can be resold, how long that takes, and what value is recovered.
Operational quality can become an advantage. It can also break during a demand spike. Review fulfillment capacity, service-level agreements, single points of failure, and the cost of the next volume tier.
7. Market size
A large retail category does not make one company venture-scale. Build the reachable market from the number of plausible customers, purchase frequency, net annual spend, and the share the company might earn through actual channels.
Then test the expansion story. Which adjacent products, geographies, customer types, or services increase customer value? Why does the company have a right to win there? Each adjacency can add market size while adding inventory, acquisition, and execution risk.
Market size and capital efficiency belong in the same conversation. A huge market is less useful when reaching it requires continuous subsidy, and a focused market can support an excellent business without producing a fund-sized outcome.
8. Defensibility
Brand can be defensible when behavior proves it. Look for direct traffic, organic referrals, repeat purchasing, pricing power, low discount dependence, earned distribution, and a community that competitors struggle to copy.
Other sources include protected product design, proprietary formulation, exclusive supply, better data, specialized regulation or know-how, and technology that improves the product or operating model. A marketplace may gain liquidity or data advantages as participation grows. Commerce software may become embedded in a merchant's workflow.
Name the mechanism and the evidence. “We will build a brand” is a plan. Stable cohort behavior or a hard-to-reproduce supply relationship is evidence. Also ask how the moat changes if a larger retailer copies the product, a platform changes its rules, or the company's main ad channel becomes less efficient.
9. Exit paths
An exit model starts with likely buyers and their reasons to acquire. A strategic buyer may value a product line, customer relationship, distribution channel, technology, supply chain, or operating capability. A financial buyer usually needs dependable cash generation and a credible improvement plan. A public listing requires far more scale, controls, liquidity, and market readiness.
Model investor proceeds across several plausible exit values. Include ownership at exit, future dilution, preferences, debt, transaction costs, and the security's conversion terms. Company sale price and investor return are different numbers. Our guide to MOIC mechanics shows how realized proceeds, unrealized value, and invested capital fit together.
A smaller acquisition can be meaningful to an angel who entered early and retained enough ownership. The same proceeds may barely affect a large fund. A thin set of plausible buyers says little about business quality. It makes the equity return path more uncertain.
What makes an ecommerce company venture-backable?
These nine filters interact. A lower gross margin can coexist with fast inventory turns and cheap organic acquisition. A high first-order CAC can work with repeat contribution that arrives quickly. A specialist commerce investor may also understand supplier, channel, or regulatory risks that a generalist cannot underwrite confidently.
Elizabeth Yin gives us the right posture in Democratizing Knowledge: “Going back to first principles is super important since the market always changes and evolves.” Dismissing an entire category skips the work. So does funding every fast-growing store as a technology company.
Venture-backable ecommerce exceptions tend to combine several characteristics:
- A large, reachable market with evidence that the initial customer and channel can expand.
- Healthy contribution economics that survive returns, fulfillment, and normalized acquisition costs.
- Cohort retention that matches the product's real purchase cycle and creates cumulative contribution profit.
- A working-capital plan that does not require new equity for every step up in inventory.
- Defensible distribution or product advantages that get stronger with scale.
- More than one credible path to a large exit, supported by the economics and strategic value a buyer would inherit.
Warby Parker is a useful boundary case because it outgrew the shape of a simple online store. Its 2025 Form 10-K describes an integrated digital and physical model with 323 stores as of December 31, 2025, in-house product design, proprietary shopping technology, a vertically integrated supply chain, eye exams, and contact lenses. The filing also reports multi-year cohort revenue retention.
That bundle makes “ecommerce” an incomplete description. It does not prove that a new online brand will follow the same path, or that any Warby Parker investment produced an attractive return at every entry price. It shows what an exception can contain: owned product, services, technology, retention, physical distribution, and a broader customer relationship.
The angel investor lens
An angel invests personal capital and does not have to produce a venture fund's return for limited partners. That freedom can make a smaller outcome relevant. It does not repair weak unit economics or turn a low sale price into a high return multiple.
Your entry price, ownership, dilution, security, follow-ons, and final proceeds still decide the result. The investment can remain illiquid for many years, with no dividends, secondary sale, acquisition, or public listing. Forecasts for repeat purchase, CAC, inventory, and exit timing can all be wrong. Total loss is possible.
Use five questions to decide whether an exception belongs in your portfolio:
- Does the core order create contribution profit? If it relies on repeat purchases, what mature cohorts prove the timing and amount?
- Where does growth consume cash? Trace acquisition, inventory, returns, and supplier payments through the next two inventory cycles.
- What will this round prove? Tie the capital to a dated operating milestone that could change the next investor's view.
- What could you receive at exit? Model your proceeds across plausible outcomes after dilution and security terms.
- Why are you equipped to judge or help? Category experience can reveal a real exception. Personal enthusiasm for the product is weaker evidence.
Inside Angel Squad, our angel-investing community, we practice this kind of diligence through curated early-stage opportunities, frameworks from our Hustle Fund investing work, and discussion with other operators and investors. The repetition matters because no single metric settles an early-stage decision.
Make the exception earn its place
Start with the business model, rebuild contribution economics, follow the cash through inventory, and model investor proceeds instead of headline company value. Then ask whether the exceptional outcome is both large enough and plausible enough for your portfolio.
If you want to sharpen that judgment alongside other operators and evaluate real early-stage opportunities from our network, apply to Angel Squad.











