
When to Approach Angel Investors: A Founder Readiness Guide
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Founders often start thinking about investors when the bank balance gets uncomfortable. That pressure makes it harder to choose the right investors, explain the use of funds, or keep building during the raise. A better timing decision starts with the milestone you want to reach and the evidence you already have.
When should you approach angel investors?
Start building relevant investor relationships before you need to raise. Make a formal fundraising ask when you can name the next business milestone, show credible evidence from your current stage, and explain how a specific amount of capital gets you there.
Those are two different activities:
- Relationship-building means meeting people who understand your market, learning how they invest, sharing occasional progress, and helping them understand how you work. You can start this well before a round.
- A formal raise means you are actively asking investors for capital. You have a target amount, the milestone it funds, a use-of-funds budget, and a financing plan for reaching that milestone and deciding what comes next. It demands focused time from you and your team.
Company age alone does not decide the timing. A pre-revenue founder with a working prototype, five prospective customers testing it, and a clear plan for the capital may be ready for serious conversations. A company with revenue may need to wait if its growth plan, customer retention, or use of funds is still fuzzy.
Fundraising is a tool for reaching a business milestone. As our general partner Elizabeth Yin writes, “You didn’t start your company to fundraise.” The round should serve the company rather than become the company’s main measure of progress.
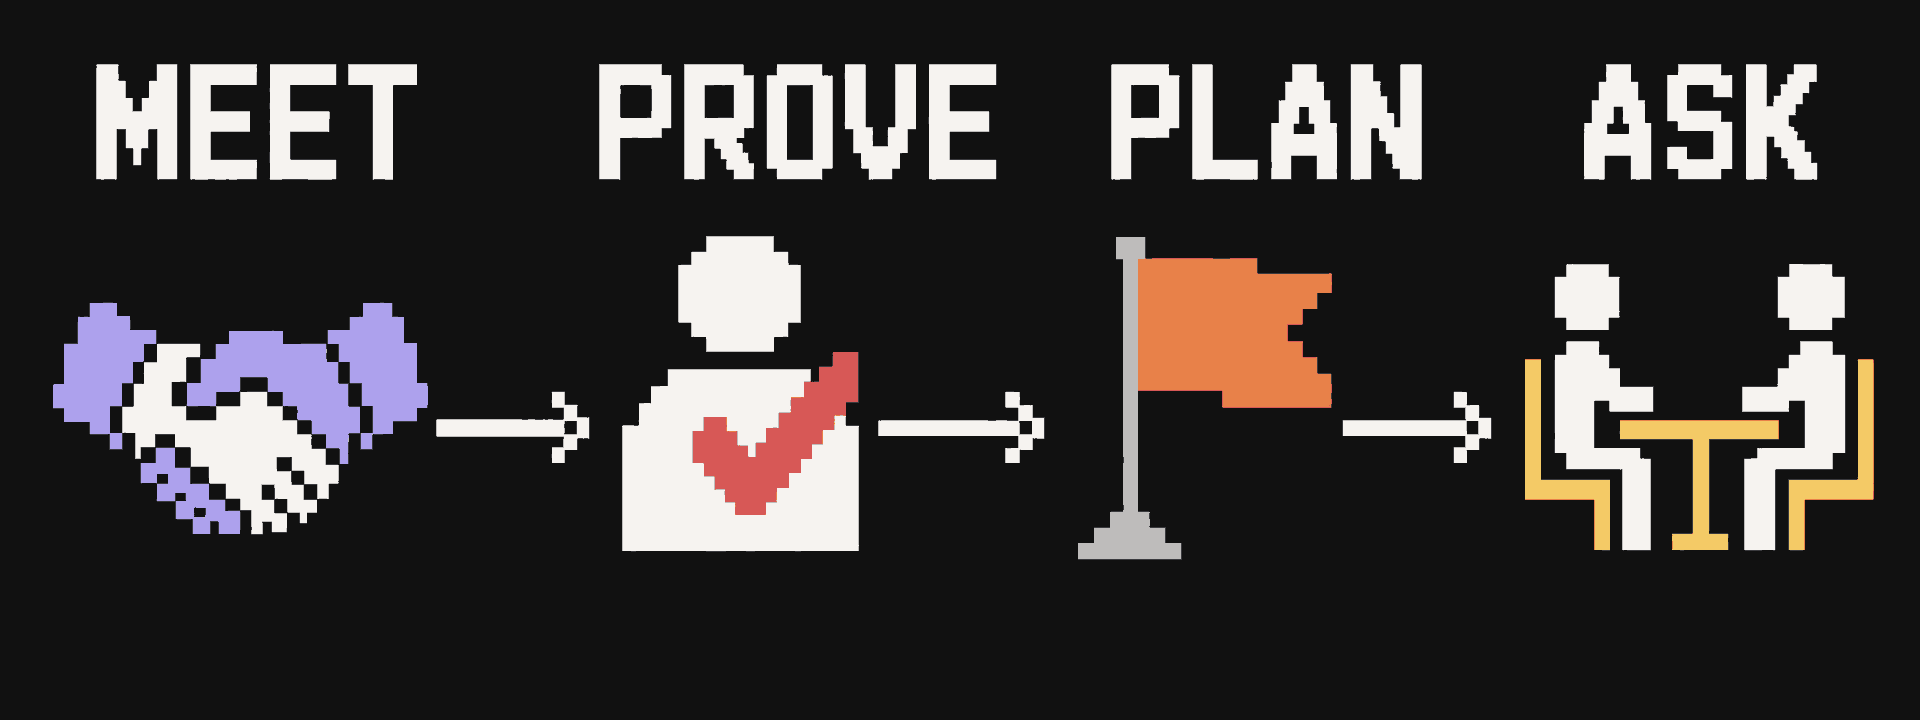
The useful sequence is relationship first, evidence next, then a formal ask tied to a milestone.
What stage do angel investors invest at?
Angel investors commonly invest at the idea, pre-seed, and seed stages. Some invest later. Each angel has a different investment focus, check size, risk tolerance, geographic focus, and level of involvement.
Early-stage startup investing is risky, and many investments fail. Readiness gives an angel a reason to take that risk. It does not remove the risk.
That range is why a universal revenue target or company-age rule is misleading. At pre-seed, an angel may assess the founders’ insight, speed, and early customer learning. At seed, the conversation may depend more on product use, revenue, retention, or repeatable customer acquisition. Our guide to funding-stage expectations explains how the evidence changes from pre-seed through Series A.
At Hustle Fund, we meet founders very early. We still expect evidence. Early evidence might be ten customer interviews that changed the product, a prototype used in a real workflow, or a pilot with a defined start date. The evidence should match the claim you are making.
Five signs you are ready to make the ask
Readiness comes from alignment across the business, the round, and the investors you plan to contact. One strong signal cannot carry a weak case everywhere else.
You know what the capital will accomplish
Tie the raise to one meaningful milestone. That could be shipping a regulated product, turning pilots into paid contracts, proving repeat usage, or finding a repeatable acquisition channel.
Work backward from that milestone. List the people, product work, sales activity, compliance work, and operating buffer required to reach it. The amount you raise should follow from that plan. “We want more runway” is vague. “This capital funds six customer implementations and the product work needed to measure renewal” gives an investor something concrete to assess.
You have evidence of demand or learning
Angels do not require the same evidence from every startup. They do expect signs that you have moved beyond assumptions.
For a pre-product company, useful proof may include repeated customer pain, access to a hard-to-reach buyer, or a prototype that has changed after user feedback. For a live product, useful proof may include new users completing the product’s key first action, repeat usage, paid pilots, revenue, retention, or a sales pipeline with clearly labeled stages.
Keep the claim proportional to the proof. A waitlist shows interest in joining a list. It does not show product use. A signed pilot shows commitment. It does not show renewal. Our guides to first-time founder credibility, customer traction, and a short product demo can help you present the evidence accurately.
Your team has a credible reason to win
Investors will look for the connection between the team and the problem. Relevant experience helps when it gives you an insight, customer access, technical ability, or operating speed that another team would struggle to copy.
Be ready to explain who owns product, customer acquisition, and company operations. Name the gaps too. A two-founder team that knows it needs a regulatory lead is more credible than one that pretends every role is covered. These team signals matter more than a long list of prestigious employers.
You have time to run a deliberate process
A raise competes with product, customers, hiring, and sleep. Starting when the company is days from missing payroll turns every conversation into a rescue attempt. It also makes it harder to walk away from an investor who is a poor fit.
You need enough operating room for introductions, first meetings, follow-ups, due diligence (the investor’s review of the company), document review, and delays. There is no fixed runway number that works for every company. Build a fundraising plan around your cash needs, team capacity, and likely decision cycle, then leave room for the process to take longer than the happy path.
You have a focused investor list and basic materials
Choose angels whose stage, sector, geography, check size, and experience fit the company. A sector operator who understands your buyer can evaluate early evidence that a generalist may miss. Investor fit saves both sides time.
Prepare a concise deck, current metrics, a working product view when relevant, a clean capitalization table that records who owns what, incorporation records, major customer agreements, and a clear account of prior financing. You do not need to send every document with the first note. You should be able to support the claims you make and respond quickly when a serious investor asks.
When to wait before seeking angel investment
Waiting can be the stronger founder decision. Use the time to remove one or two major uncertainties rather than collecting polite rejections from investors who cannot see the case yet.
- The capital has no defined job. If you cannot connect the money to a milestone, keep planning. Capital without a purpose can fund activity while leaving the core risk untouched.
- You have not built a customer learning loop. A polished deck cannot replace direct contact with the people who have the problem. Run interviews, tests, prototypes, or sales conversations and show what changed.
- The business does not fit venture-style capital. Angel equity comes with dilution, meaning a smaller ownership percentage for existing holders, and investor expectations. A durable local business, a service company, or a company that can grow from customer revenue may be better served by another path. Review the terms affecting ownership with qualified legal and tax professionals before accepting investment.
- You plan to promote the raise indiscriminately. In the United States, the rules for public fundraising communications depend on the offering. The SEC’s general solicitation overview explains why an unrestricted public post can matter. Work with qualified securities counsel before describing an offering publicly.
- You treat every investor as interchangeable. An irrelevant list of hundreds of names is not a fundraising strategy. Narrow the list around people who can understand the company and participate at this stage.
Waiting should have an end condition. Choose the proof that would change the next conversation, such as three completed pilots, four weeks of repeat usage, a technical prototype, or a key hire. Return to investors when you have that new evidence.
How to approach angel investors when you are ready
The first outreach has one job: earn a relevant conversation. It does not need to close the round by email.
Research the fit
Confirm that the investor writes checks at your stage and has a reason to care about the problem. Look at past investments, operating experience, geography, likely conflicts, and whether the person is actively investing. Personalize the note around real fit instead of flattery.
Use a warm path when it is practical
A thoughtful introduction from a founder, operator, lawyer, customer, or investor can transfer context and trust. Ask the connector for an introduction only when the fit is real, and give them a short paragraph they can forward.
Cold outreach can work too. A specific note to a relevant angel is stronger than a vague note sent to everyone.
A targeted email is not automatically outside securities solicitation rules. The SEC says whether a communication is a general solicitation is a fact-specific determination, so have qualified securities counsel review the audience, message, and offering before you send fundraising outreach.
Keep the note short:
- What your company does and for whom.
- The strongest evidence you have earned.
- The amount you are raising and the milestone it funds.
- Why this investor is relevant.
- One clear request for a short conversation.
Treat the first meeting as a dialogue
Our co-founder Elizabeth Yin describes fundraising as “a series of dialogues – not pitches.” Ask how the angel invests, what evidence matters at your stage, how decisions get made, and where the investor can help. You are evaluating the investor while the investor evaluates you.
Leave with a clear next step. That might be a product demo, customer reference, partner call, or a polite agreement to reconnect after a milestone. If the conversation continues, prepare for the investor follow-up call around the questions that remain open.
Your readiness checklist before outreach
Run this check before you activate introductions or send the first batch of notes:
- Milestone: You can state the next business milestone in one sentence.
- Amount and use: Your target amount, use of funds, and financing plan support the milestone.
- Proof: Your main claims connect to customer, product, market, or execution evidence.
- Team story: Each founder’s role and relevant edge are clear, along with material gaps.
- Investor fit: Every person on the first list has a plausible reason to invest at this stage.
- Materials: Your deck, metrics, product view, and company records are current and consistent.
- Diligence readiness: Your capitalization table, formation documents, financing history, and major agreements are organized for qualified review.
- Follow-up plan: You know who owns each response, what progress you will share, and when you will reconnect.
If several items are missing, keep building. If they align, begin with a small set of well-matched investors, learn from those conversations, and refine the process before widening it.
What happens after the first conversation
An interested angel may ask for another meeting, more evidence, references, diligence materials, or an introduction to other investors. The sequence varies, and interest is not a commitment. Our guide to the angel investment process covers the wider path from outreach through closing.
If your company is early and fits Hustle Fund’s pre-seed focus, tell us what you’re hustling. Send the evidence you have, the milestone you are pursuing, and why our team is relevant.
This material is for general educational purposes and does not constitute legal, tax, or investment advice. Fundraising and securities rules depend on the facts, jurisdiction, offering structure, and governing documents. Seek independent review from qualified legal and tax professionals.











