
What Is an Angel Round? Funding, SAFEs, and Dilution
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
An angel round is a startup financing event backed mainly by individual angel investors. The label describes the financing and its backer mix. It is not a fixed legal stage or a special securities-law exemption.
The useful question for an investor is what the check buys. The answer depends on the security, its valuation terms, the option pool, and the ownership denominator used in the cap table.
An angel round can happen at several startup stages
Angel investors generally invest their own money in emerging businesses. Venture funds invest money pooled from their limited partners. That difference describes the investor, not a mandatory place on a startup’s fundraising timeline.
Angels often invest at pre-seed and seed, and they can also join Series A or later rounds. The SEC’s guide to early-stage investors makes the same point: company stage, round, investment structure, and investor type do not line up in one rigid sequence.
An angel round also has no standard size, valuation, or instrument. One startup may sell preferred shares to several angels in a priced financing. Another may issue SAFEs to angels over several closings. A third may take a pooled check from a special purpose vehicle (SPV). The round name alone tells you very little about ownership.
The legal analysis is separate. A private company’s offer and sale of securities must be registered or qualify for an exemption, even if there is only one investor, according to the SEC’s private-company guidance. “Angel round” is not one of those exemptions, and the label does not tell you whether every participant must be accredited.
What an angel receives depends on the instrument
Three instruments appear often in angel rounds. Each gives the investor a different legal position today and a different path to future ownership.
- Priced equity: The company sells shares at an agreed price per share. If the angel buys the shares directly, they become a stockholder at closing. If the check goes through an SPV, the vehicle becomes the startup stockholder and the angel owns an interest in the SPV. Preferred shares may include liquidation, voting, information, or participation rights that common shares do not have, so the percentage alone is incomplete. The charter, stock purchase agreement, and investors’ rights agreement control the details. Our guide to term-sheet rights goes deeper on those provisions.
- Convertible note: The investor lends money to the company under debt that can convert into equity. The note usually has interest and a maturity date, along with conversion terms that may include a valuation cap or discount. The signed note decides what happens if conversion, maturity, or another trigger arrives.
- Simple Agreement for Future Equity (SAFE): The investor funds the company now for contractual rights to stock later. A SAFE is not stock when signed, and the standard Y Combinator form is not debt and has no interest or maturity date. A priced equity financing generally triggers conversion, but liquidity and dissolution provisions also matter. YC publishes the current SAFE forms and guide.
An SPV is not a fourth security type. It is an entity that aggregates several investors into one line on the startup’s cap table. The SPV might hold preferred shares, a note, or a SAFE, while each participant owns an interest in the SPV. The wrapper has its own governing documents and allocation mechanics. Its terms may also add fees or carry to the startup security underneath it. The broader mix of debt, equity, and convertible claims is the company’s capital structure.
Valuation changes the ownership math
Valuation works differently in a priced round and a SAFE round. Mixing the two sets of terms is one of the fastest ways to misread an opportunity.
Priced-round valuation sets a share price now
In a simple primary priced round, pre-money valuation is the negotiated value immediately before the new cash. Post-money valuation equals the pre-money valuation plus the primary investment.
If a company raises $1 million at a $4 million pre-money valuation, the post-money valuation is $5 million. The new investor’s 20% post-round ownership follows from $1 million divided by $5 million, assuming the agreed fully diluted capitalization contains no other adjustments. The share price still depends on how many shares and reserved options sit in that denominator.
A deeper guide to startup valuations can help you assess the headline number. Our co-founder and GP Shiyan Koh puts it plainly: “The check size, entry valuation, and follow-on investments all impact potential returns.” A valuation is one input. Ownership, security rights, future dilution, and company outcomes still matter.
A SAFE cap is a conversion term
A SAFE valuation cap sets a ceiling used to calculate the conversion price when the cap applies. It is not a current appraisal or agreed present value of the company. A discount, most favored nation provision, or the next round’s price can change the conversion calculation under other SAFE forms.
Simplified hypothetical, not a projection: An angel invests $250,000 on a YC-style post-money valuation-cap SAFE with a $5 million cap. If cap pricing applies, $250,000 divided by $5 million implies 5% as-converted ownership before the later priced round.
That investor does not receive issued shares or an unconditional 5% stake at signing. New money in the priced round and any related option-pool expansion dilute the converted position. If the priced round’s price is at or below the cap price, the SAFE may convert into more shares than the cap estimate. The signed SAFE and the conversion cap table provide the answer.
Pre-money SAFEs require a different calculation. When a company has issued several pre-money SAFEs at different caps, each instrument can convert at a different price and the SAFEs can dilute one another. In that setting, our co-founder and GP Eric Bahn warns: “It is really easy to mess up these calculations.” Build the pro forma from the company’s actual SAFE terms rather than reusing the post-money shortcut.
Dilution starts with the denominator
Dilution means a holder’s shares become a smaller percentage of a larger capitalization after the company issues or reserves more equity. The original shares do not disappear. The denominator grows.
You also need to know which denominator a percentage uses:
- Issued and outstanding ownership counts shares that have already been issued.
- Fully diluted ownership usually adds shares reserved for options and other securities that could become shares under the stated assumptions.
- Post-financing ownership models the round, conversions, and any option-pool change on top of the pre-round cap table.
An employee option pool is a reserve of shares available for equity awards. It may include shares underlying outstanding, unexercised option grants, and unissued shares available for future grants. Once an option is exercised, the resulting shares become issued and outstanding rather than remaining in the pool. A pre-money pool increase enters the fully diluted denominator used to set the round price, so existing holders generally bear that dilution before the new investor buys in. A post-money pool increase dilutes existing and incoming holders together. The term sheet must say which treatment applies.
A priced angel round, worked from check to cap table
Simplified hypothetical U.S. priced round, not a SAFE or a projection: The financing is a primary issuance, so the $1 million goes to the company. There are no notes, SAFEs, warrants, other investors, secondary sales, fees, or transaction adjustments in the calculation.
- The founders hold 8,000,000 common shares.
- The company has 2,000,000 unissued option shares reserved and counted in the negotiated pre-money fully diluted capitalization.
- Pre-money fully diluted shares are 10,000,000. At a $4 million pre-money valuation, the price is $0.40 per share.
- The angel’s $1 million buys 2,500,000 new preferred shares.
- The post-money valuation is $5 million, and post-round fully diluted shares total 12,500,000.
- On that fully diluted basis, the founders hold 64%, the unissued option pool represents 16%, and the angel holds 20%.
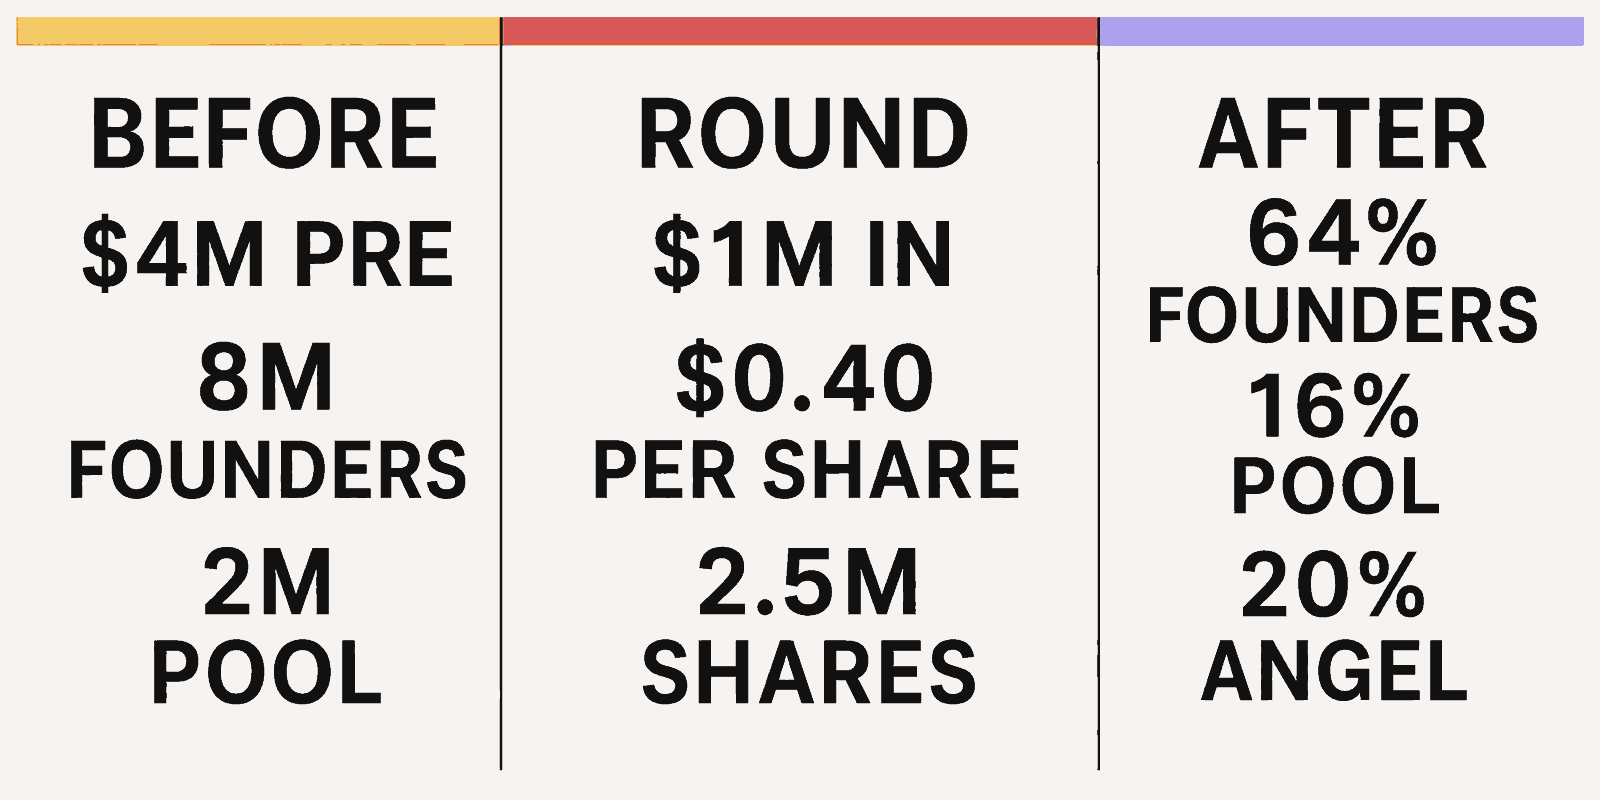
The 2,000,000 reserved option shares are not issued shares, and they do not contribute cash to the round. They count only because the parties agreed to use a fully diluted denominator that includes the reserve. That treatment leaves the founders with a different post-round percentage than a deal with no pre-money option reserve, even when the headline valuation and investment are the same.
The calculation follows the pro forma cap-table convention of adding the proposed financing and negotiated option reserve to the existing capitalization before comparing ownership.
Pro rata rights require another check
A pro rata right gives an investor an option to invest more money in a future financing, subject to its terms and the available allocation. It does not freeze the investor’s ownership percentage or protect the investor from dilution without more capital.
The standard YC post-money SAFE does not include pro rata rights by default. YC provides an optional side letter for parties that agree to them. Our guide to pro rata rights covers the portfolio decision behind exercising or declining that option.
Before signing, use our capitalization-table guide to reconcile the pro forma cap table to the actual financing documents. Focus on five checks:
- Current securities: Match every stockholder, share class, option grant, warrant, SAFE, and note to the company’s records.
- The denominator: Label issued and outstanding, fully diluted, and post-financing percentages. Confirm how unissued option reserves are treated.
- Conversion assumptions: Model every SAFE and note using its purchase amount, cap, discount, most favored nation terms, interest, and maturity provisions as applicable.
- The new round: Confirm the share price, new shares, primary and secondary amounts, pool top-up, and ownership immediately after closing.
- Rights outside the cap table: Read the charter, purchase agreement, investors’ rights agreement, voting agreement, and side letters. The NVCA model documents show how several priced-round agreements fit together, but the signed deal documents govern.
If you invest through an SPV, perform one more reconciliation. Multiply the SPV’s modeled startup ownership by your economic share of the vehicle, then account for the SPV’s expenses and carry under its documents. Your name may sit in the SPV ledger while the vehicle appears as the startup’s cap-table line.
What happens after the angel round
The company closes the financing, updates its records, and uses the capital. An investor then faces company updates, possible follow-on decisions, further dilution, and an uncertain wait for an acquisition, public offering, shutdown, or another outcome. Private startup securities are usually illiquid, and you can lose the entire investment.
The operational work of reviewing deal flow, signing, wiring, storing records, handling tax documents, and receiving distributions belongs in our separate guide to how angel investing works. Here, the cap table and signed financing documents are the final record of what the round did to your ownership.
Practice the math before you commit
Explore Angel Squad to learn with Hustle Fund’s team, review curated deal flow, and decide deal by deal whether an eligible opportunity fits your portfolio.
Disclaimer: Startup investments are speculative, illiquid, long term, and may result in total loss. The examples above are simplified educational hypotheticals, not projections or legal, tax, accounting, valuation, or investment advice. Actual outcomes depend on the governing documents, security terms, fees, carry, taxes, cap table, valuation policy, and timing. Past results and current marks do not guarantee future results. Review the signed documents and seek independent advice from qualified legal, tax, accounting, and investment professionals for your deal and jurisdiction.











