
TVPI: Formula, Meaning, and How Venture Investors Read It
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
Important: This is general educational information, not investment, legal, tax, accounting, or valuation advice. Every example is hypothetical and simplified, not a projection. Startup and private-fund investments are speculative, illiquid, long-term, and can result in total loss. Past results and current marks do not guarantee future results. Actual TVPI depends on governing documents, management fees, carried interest, taxes, cap-table rights and preferences, valuation policy, cash-flow and reporting timing, and the treatment of capital calls, distributions, recycling, and fund expenses. Read the governing documents and work with qualified independent investment, legal, tax, accounting, and valuation advisers.
TVPI compresses the cash a fund has distributed and the estimated value it still holds into one multiple. That makes it useful, easy to quote, and easy to misread. Here’s how to calculate it, compare it with other fund metrics, and find the assumptions hiding behind the headline number.
What does TVPI mean?
TVPI stands for total value to paid-in capital. It measures a private fund’s total reported value relative to the capital its limited partners (LPs) have contributed so far.
The TVPI formula is:
TVPI = (cumulative distributions + residual value) ÷ paid-in capital
Each input has a specific job:
- Cumulative distributions are the value the fund has already transferred to LPs. Check whether these were cash or securities distributed in kind.
- Residual value is the fund’s estimated net asset value (NAV) for investments and other relevant assets still held at the reporting date.
- Paid-in capital is the capital LPs have actually contributed. It is different from committed capital, which includes amounts the manager may call later.
TVPI can also be expressed as:
TVPI = DPI + RVPI
Distributions to paid-in capital (DPI) is cumulative distributions divided by paid-in capital. Residual value to paid-in capital (RVPI) is residual value divided by paid-in capital.
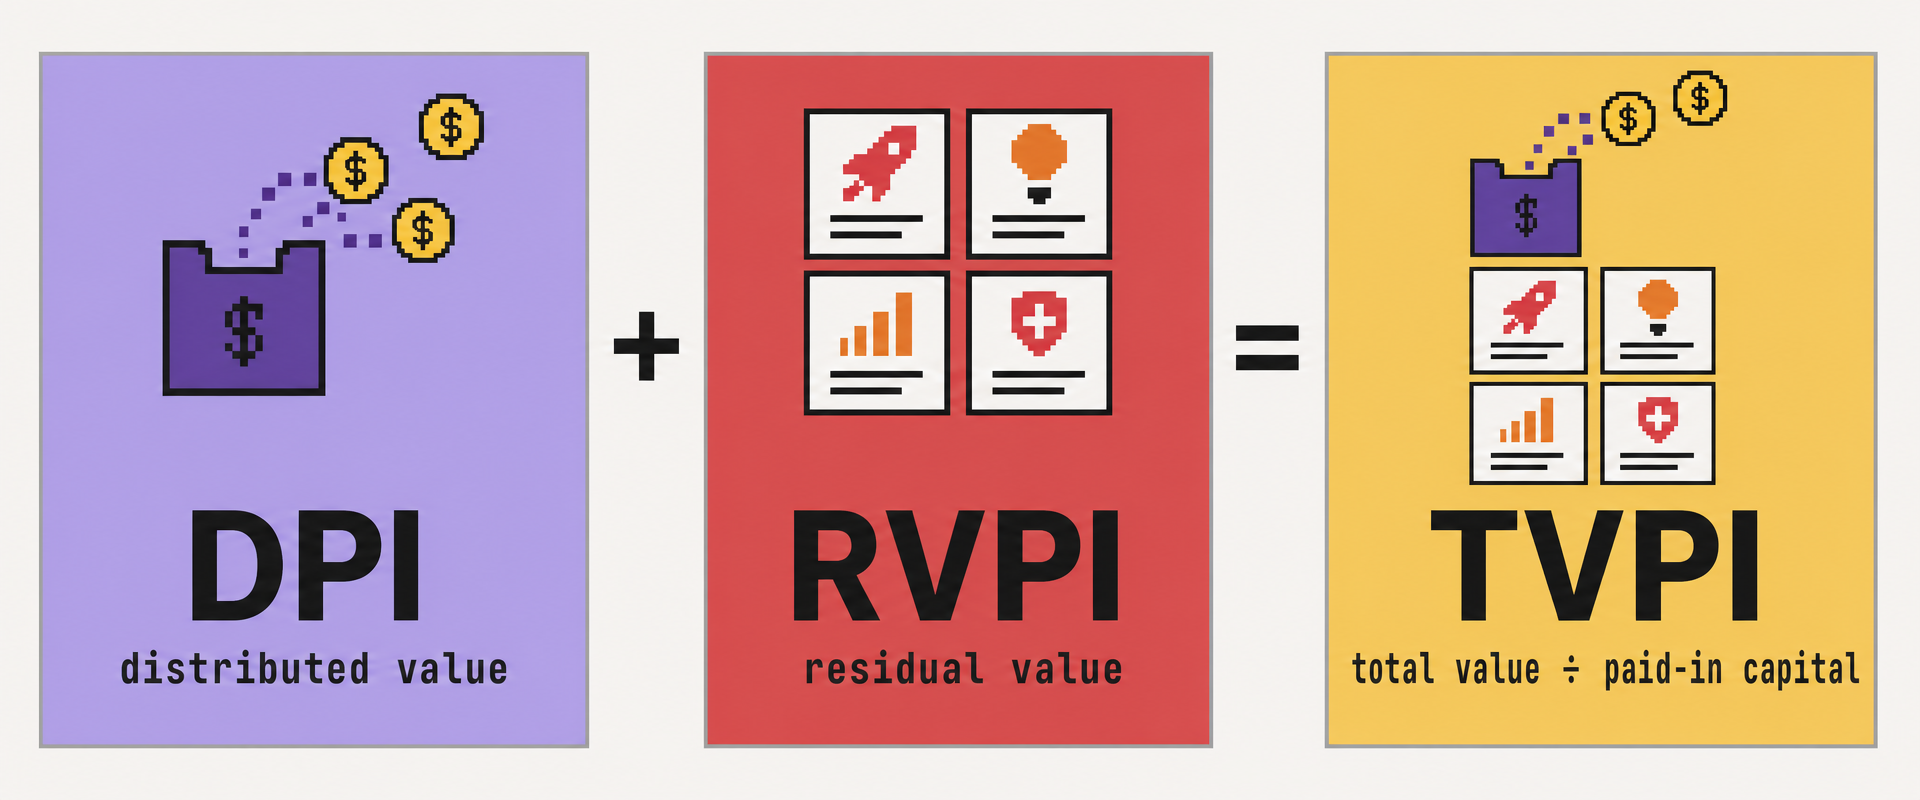
That split matters. A 1.50x TVPI could contain substantial cash distributions, or it could rest almost entirely on unrealized valuations. The headline multiple alone won’t tell you which.
What does a 1.0x TVPI mean?
A 1.0x TVPI means the fund’s distributions plus remaining NAV equal its paid-in capital at that reporting date. It does not mean LPs have received all their money back. DPI shows the distributed portion.
A TVPI above 1.0x means reported total value exceeds paid-in capital. A TVPI below 1.0x means reported total value is below paid-in capital. Neither result is a complete verdict without the fund’s age, strategy, valuation basis, and DPI.
How to calculate TVPI
Use numbers from the same reporting date and the same scope. Mixing a gross portfolio NAV with net LP contributions produces a polished-looking answer that compares unlike things.
Hypothetical, simplified fund-level example: As of December 31, 2030, this example covers one 2026-vintage venture fund on a net-to-fee-paying-LPs basis. Paid-in capital is $8 million, including initial investments, follow-ons, management fees, and fund expenses. Cumulative distributions are $3 million, and residual NAV is $9 million, so the realized/unrealized value mix is $3 million/$9 million. Carried interest is already reflected in LP distributions and NAV; taxes are ignored; there is no subscription line, recycling, recallable distribution, or in-kind distribution. All cash flows are measured through the reporting date under one consistent valuation policy. This illustration is not a projection.
The calculations are:
- TVPI: ($3 million + $9 million) ÷ $8 million = 1.50x
- DPI: $3 million ÷ $8 million = 0.375x
- RVPI: $9 million ÷ $8 million = 1.125x
The report shows $1.50 of total value for every $1.00 contributed. Only $0.375 per dollar has been distributed. The remaining $1.125 is residual value that still has to survive dilution, company performance, exit terms, fees, carry, taxes, and time before it becomes cash an LP can use.
That is the honest reading of 1.50x TVPI. Saying “the fund returned 1.50x” would overstate what happened.
What is a good TVPI?
There is no context-free “good” TVPI. Compare a fund with peers that share its vintage year, strategy, stage, geography, fund size, reporting date, and net or gross basis.
Our co-founder and general partner Elizabeth Yin puts the broader allocation lesson plainly: “Decisions are never in isolation - they are a comparison game.” TVPI follows the same rule.
Recent venture data shows how wide the range can be. At year-end 2025, a dataset of 2,906 venture funds found that 2019-vintage funds had a median TVPI of 1.33x, a 75th-percentile TVPI of 1.90x, and a 90th-percentile TVPI of 3.01x. Those are sample benchmarks, not universal targets, and each still contains unrealized value.
Fund age changes the reading. A young net TVPI can sit below 1.0x while fees and early write-downs arrive before exits. An older fund with high TVPI and low DPI deserves questions about when and how the remaining value may turn into distributions.
Before calling a TVPI good, establish these six points:
- Peer group: Compare funds with similar vintages and strategies.
- Basis: Compare net with net, or gross with gross.
- Realization mix: Separate DPI from RVPI.
- Concentration: Identify how much residual value comes from the top one, three, and five holdings.
- Valuation quality: Review the valuation policy, last priced round, subsequent company performance, and any stale marks.
- Direction: Track what changed from the prior quarter and why.
TVPI vs. DPI, RVPI, MOIC, and IRR
These metrics answer different questions. Introduce the question first, then choose the number.
TVPI vs. DPI
TVPI asks: What total value does the fund report for each dollar LPs have paid in?
DPI asks: What value has the fund distributed for each dollar LPs have paid in?
TVPI includes realized and unrealized value. DPI contains distributions only. Once a fund has sold or written off every investment and residual value reaches zero, TVPI and DPI converge, assuming the same scope and capital basis.
DPI is firmer than residual NAV, though it still requires care. A distribution of publicly traded shares has liquidity, price, tax, and timing considerations that differ from cash. Ask whether reported distributions were cash or in kind.
TVPI vs. RVPI
RVPI is the unrealized component inside TVPI. If TVPI is 1.50x and DPI is 0.40x, RVPI is 1.10x.
A high RVPI is normal for a young venture fund. It also makes TVPI more dependent on valuation estimates. As the fund matures and exits occur, a healthy realization process generally shifts value from RVPI into DPI. Total TVPI may rise or fall during that shift.
TVPI vs. MOIC
Multiple on invested capital (MOIC) is a flexible multiple used at deal, portfolio, and sometimes fund level. It often divides current value plus realized proceeds by investment cost.
TVPI is usually the LP-facing fund multiple. Net TVPI uses contributed capital and LP-level value after the economic effects specified by the fund’s reporting basis. Gross MOIC may exclude management fees and fund expenses from its denominator and remove fee and carry effects from its numerator.
The formulas can look identical while the inputs differ. Treating Gross MOIC, Net TVPI, and a report labeled “net MOIC” as synonyms can create a false comparison. Our MOIC formula guide goes deeper on the multiple’s uses.
TVPI vs. IRR
Internal rate of return (IRR) incorporates the timing of cash flows. TVPI does not. Two funds can both report 2.0x TVPI even if one reached that value in four years and the other took twelve.
IRR introduces its own sensitivities, including capital-call and distribution timing. Read it beside TVPI, DPI, and the actual cash-flow schedule. No single metric can carry the whole fund report.
Why TVPI can mislead without being fake
Residual value is an estimate, but “estimate” does not mean “made up.” Private investments lack a continuously quoted market price. Fund managers still need to report fair value between financing rounds and exits.
The current IPEV valuation guidelines call for fair value at each measurement date and the use of current, knowable information. They also say a recent transaction price may be a starting point, while changes in the company and market still need consideration. Judgment is unavoidable. A documented, consistently applied policy makes that judgment easier to assess.
TVPI becomes misleading when the reader cannot see the assumptions. Watch for these failure modes:
- Paper-heavy value: Most of the multiple sits in RVPI, with little DPI.
- One-company dependence: A single marked-up investment drives most of the result.
- Stale marks: A company has missed milestones or the market has changed since its last financing, yet the valuation has barely moved.
- Headline-round shortcuts: The latest financing price is applied without considering security rights, preferences, dilution, or subsequent performance.
- Gross/net confusion: One manager presents gross performance while another presents net performance.
- Capital-base differences: Contributions, recycling, recallable distributions, fees, and subscription facilities receive different treatment.
The Institutional Limited Partners Association’s current performance template defines fund-level Net TVPI and calls for reporting with and without the impact of fund-level subscription facilities. That level of basis disclosure is what makes comparisons usable.
How to read TVPI in a fund report
Start with the multiple, then interrogate the moving parts. Use this sequence:
- Confirm the label. Is the number fund-level Net TVPI, a gross portfolio multiple, or something else?
- Confirm the date and scope. Find the reporting date, fund vintage, currency, and LP class covered.
- Rebuild the equation. Obtain cumulative paid-in capital, distributions, and residual NAV. Check that TVPI equals DPI plus RVPI.
- Inspect distributions. Separate cash from in-kind value and note anything recallable.
- Inspect NAV. Ask which companies drive it, when each was last priced, which valuation method was used, and how preferences or dilution were handled.
- Compare consistently. Use the same vintage, strategy, size band, reporting date, and net/gross basis.
- Read the trend. Explain quarter-over-quarter changes through exits, new capital calls, follow-ons, write-ups, write-downs, fees, and carry.
- Pair the metrics. Read TVPI with DPI, RVPI, IRR, and concentration. Each number checks a different weakness in the others.
Elizabeth Yin writes, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” A repeatable reporting checklist turns TVPI from a bragging point into useful evidence.
Does TVPI apply to angel investments and SPVs?
TVPI is most useful for a pooled private fund with capital calls, fund expenses, distributions, and a residual portfolio. The right metric for an angel investor depends on the structure.
- Direct startup investment: Track invested cost, current fair value, realized proceeds, dilution, and ownership. Deal-level MOIC is usually clearer than calling the result TVPI.
- Single-deal special purpose vehicle (SPV): A manager may report MOIC or a TVPI-like multiple. Confirm whether the number is net of vehicle fees and carry and whether paid-in capital includes every contribution.
- Venture fund: Fund-level Net TVPI, DPI, RVPI, and IRR belong together. Compare them with the governing documents and a consistent benchmark group.
Your personal angel portfolio may contain direct investments, SPVs, and fund interests. Keep the scopes separate. Adding reported multiples together produces nonsense because each multiple can use a different denominator.
TVPI earns its place when you can see what is distributed, what remains estimated, and what investors actually paid. If you want to build that kind of investor judgment alongside experienced operators and gain access to curated early-stage opportunities, apply to Angel Squad.











