
Psychology of Angel Investing: Better Decisions
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A startup pitch can make a capable operator feel unusually certain. The market is familiar. The founder is impressive. People you respect are investing. Then a thin set of facts starts to feel like a complete picture.
That gap between the evidence you have and the confidence you feel is the central problem in the psychology of angel investing. A repeatable decision process helps you see the gap before you write the check.
What the psychology of angel investing means
The psychology of angel investing is how uncertainty, expertise, emotion, social information, and delayed feedback shape an investor’s judgment. It matters because a pre-seed startup gives you little clean evidence. The product may be unfinished, the market may be emerging, and the founder’s plan will change.
Private startup investments add hard financial constraints to that uncertainty. The SEC warns that private placements can involve limited disclosure, indefinite holding periods, illiquidity, and total loss. You still have to decide before the result is knowable.
A bias glossary names the traps. Following the decision sequence shows where you can interrupt them before a reasonable judgment becomes a confident story.
Our broader investing psychology guide explains the recurring mental traps. Consider one hypothetical deal from first impression to post-investment review.
How a smart investor’s view gets narrower
Maya is a hypothetical cybersecurity operator considering a seed-stage security startup. She understands the customer, likes the founder, and sees a problem she has faced herself. Her expertise gives her useful questions and a faster read on technical claims.
It also makes the pitch feel fluent. The story is easy for her to process, so confidence arrives before she has tested the parts outside her expertise: distribution, pricing, founder dynamics, financing needs, and the terms of the round.
Expertise is still an asset. Research on experienced angels found that they combined formal analysis with expertise-based intuition when assessing very early-stage companies. In that study, their assessments of entrepreneurs predicted the unusually profitable investments in the sample four years later. This angel-investor research supports keeping both intuition and analysis visible in the record.
Fluency starts to feel like certainty
Maya writes an early thesis: “Security teams need this, and this founder understands the buyer.” That may be right. She has bundled two observations with several untested assumptions.
She also has a successful operating career. Skill in one domain can create confidence in an adjacent one. An experiment involving venture capitalists found overconfidence in their predictions about new ventures and warned that it could inhibit learning. That venture-capitalist study does not tell us how common overconfidence is among angels. Maya can still separate the evidence from confidence carried over from her career.
Peer interest compresses the remaining questions
Next, a respected investor commits to the round. Three other angels join. The social signal is relevant, but Maya treats the names as a substitute for understanding why they invested.
Peer behavior is not automatically irrational herding. A study of angel groups distinguished visible external enthusiasm from information held by existing investors. Experienced angels in the study responded more to the latter, which could include firsthand knowledge of company performance or the founder. The study’s social-proof findings suggest that the source and information behind a signal matter more than the number of recognizable names.
Incentives matter too. As our general partner Shiyan Koh says, “Show me the incentives, and I'll show you the outcome.” A lead with the right to keep investing in later rounds, a scout earning a share of investment profits, and an operator writing a personal check may all like the same deal for different reasons.
The first thesis directs the search
Maya now asks questions, but most of them help complete the story she already likes. She spends more time validating buyer pain and less time investigating sales cycles, implementation burden, and why the incumbent cannot copy the product.
A field experiment involving public-stock investors found that participants placed more value on messages supporting their prior beliefs. That confirmation-bias evidence is not an estimate of the effect among angels. Maya can assign part of the diligence process to finding evidence that would make her pass.
The round closes soon. Time pressure turns unresolved questions into “risks we can live with.” Maya invests. The choice may work out, and the process can still be weak. It may fail, and the process can still have been reasonable.
Use a pre-check before every decision
A pre-check creates distance between the pitch and the check. It should fit on one page and force five decisions while the original facts are still visible.
- Set the loss boundary. Decide the most you can lose on this check without changing your financial plan or behavior toward the founder. Base the amount on your full financial position, other startup exposure, and investment risk tolerance, not on how exciting the deal feels. There is no universal right check size or portfolio count.
- Write the thesis in plain language. State why this company, why this founder, why now, and what must become true. Separate observed facts from assumptions. “The founder signed three design partners, prospective customers who help shape and test the product” is a fact. “Those partners will convert to durable revenue” is an assumption.
- Name the disconfirming evidence. Write two facts that would make you pass. Then look for them. This turns “I did diligence” into a test of the thesis. A structured due diligence checklist can cover the company, market, team, terms, and references without confusing more documents with more certainty.
- Interrogate the social signal. Ask what another investor knows, how they know it, whether they invested before, how much direct access they have, and what incentive shapes their recommendation. “A lot of smart people are in” is weak evidence. A specific customer reference or observation from an existing investor is stronger.
- Run a pre-mortem. Assume it is three years later and the investment is a total loss. List the three most plausible causes. Gary Klein’s pre-mortem method is designed to surface risks before a decision. It is a risk-identification tool, not proof that the check will perform better.
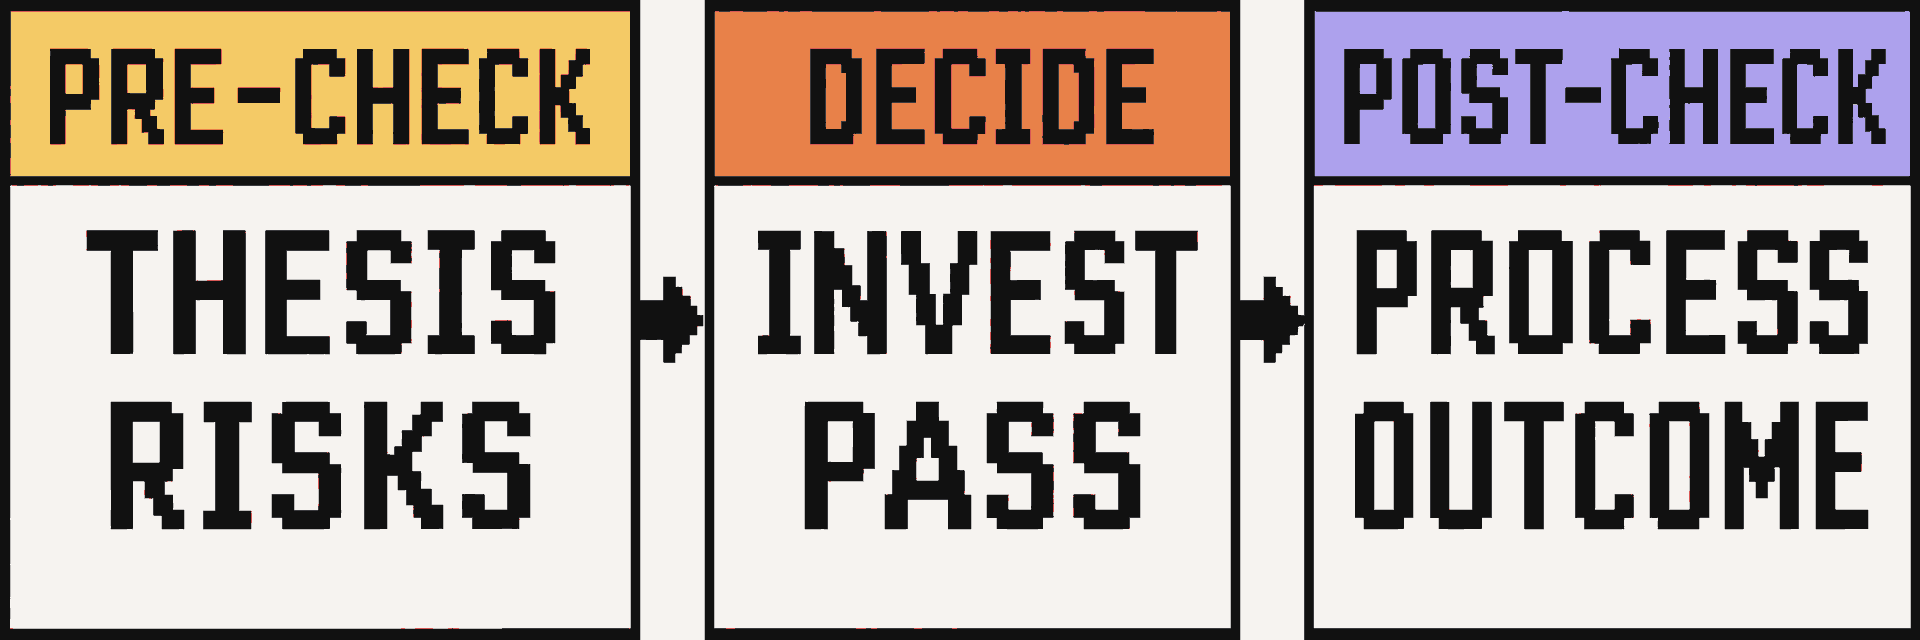
The pre-check ends with a decision and a confidence range. “Invest, 60% confidence that the company reaches its next financing milestone” is more useful than “This is a winner.” The number is a record of your belief, not a prediction dressed up as precision.
Use a post-check to learn without rewriting history
Startup feedback is slow and messy. A price increase in a later round may reflect progress, market conditions, or investor demand. A shutdown may follow a sound initial decision and an unpredictable event. Cash returned is clearer than an unrealized valuation estimate, but even a realized result does not reveal whether the original reasoning was good.
Our co-founder Elizabeth Yin made that point while reflecting on her seven-company personal angel portfolio: “My portfolio is 3-5 years into angel investing, and all of this is paper gains.” By “paper gains,” she meant unrealized increases in value, not cash returned. An interim valuation can inform a post-check, but it is not a final outcome.
Outcome bias makes a decision look better after a good result and worse after a bad one, even when the information available at the time is identical. Baron and Hershey demonstrated this pattern in a series of decision experiments. Hindsight bias adds another problem. In Fischhoff and Beyth's study, people remembered completed events as more likely than they had originally predicted. Once you know what happened, your earlier uncertainty becomes hard to remember.
A decision journal preserves that uncertainty. Review it on a fixed cadence and keep the process review separate from the company update.
- Re-read the original entry before the latest update. Record what you believed, your confidence, the assumptions, and the failure cases.
- Score the process using only then-available information. Did you follow the pre-check? Did you investigate disconfirming evidence? Did your check stay inside the loss boundary?
- Compare assumptions with new evidence. Mark each assumption supported, weakened, unresolved, or no longer relevant. Do not change the original wording.
- Record surprise. Write what happened that you had not considered. This is where your future checklist improves.
- Make the next decision fresh. A follow-on check is a new investment on current facts and terms. Prior capital is gone either way. Declining to invest again is not an admission that the first check was wrong, and investing again is not automatically a sunk-cost mistake.
If a company fails, our guide to the psychology of investment losses goes deeper on the emotional side of reviewing the loss without taking it out on the founder.
Set the right standard for the process
The pre-check and post-check can expose assumptions, improve consistency, and make your learning record more honest. They cannot remove the sparse evidence at the center of early-stage investing. They do not guarantee a better return.
Aim for a defensible decision with a survivable downside, made from the information available at the time. Startup investments remain speculative, illiquid, long-term, and capable of producing a total loss. Luck will affect the result, and thoughtful investors can reach different conclusions on the same deal.
Practice the process before the next pitch
If you want to compare your reasoning with other operators while reviewing curated opportunities, apply to Angel Squad.
This content is for educational and informational purposes only. It is not investment, legal, tax, accounting, or valuation advice or a recommendation to buy or sell any security. Private startup investments are speculative, illiquid, long-term, and may result in total loss. Past results and current valuation estimates do not guarantee future results. Consult qualified independent financial, legal, tax, accounting, and valuation professionals, and review the governing offering documents, terms, fees, profit-sharing terms, tax treatment, company ownership records, valuation policy, and timing before making an investment decision.











