
Future of Investing: AI, Access and the Risks That Stay
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
You can read company filings with artificial intelligence (AI), automate a portfolio, or find a private investment online. Each opens a door. Each also creates a decision you still own. Understanding the future of investing means knowing which changes improve your process and which risks come along for the ride.
Where the future of investing is taking shape
AI-assisted research, automated portfolio management, digital ownership records, and online private-market access are changing how people invest. These shifts affect different parts of the process. A tool that saves research time does something different from a platform that offers a new investment or a system that records ownership.
For public-market investors, that can mean faster analysis and more personalized portfolios. For aspiring angels, people who invest their own money in startups, it can mean smaller entry checks, more companies to evaluate, and more ways to learn from experienced investors.
Our view is that broader access earns its value when investors have the knowledge to use it. More opportunities also mean more opportunities to make an expensive mistake. The useful question for every new tool is what it improves, what it leaves unresolved, and who remains responsible.
1. AI is making research faster and raising the standard for evidence
AI can summarize a lengthy filing, organize founder updates, or turn a collection of documents into a first list of diligence questions. Due diligence is the investigation behind an investment decision, including the business, people, finances, and terms.
The International Monetary Fund’s capital-market analysis identifies potential gains in risk management and market efficiency. It also warns that similar automated responses can amplify selling during market stress. Faster decisions can spread mistakes faster, too.
We’ve seen the operational side firsthand. In 2024, our general partner Eric Bahn wrote about structured deal intake and an AI workflow that summarized portfolio-company updates. He also stated the boundary clearly: “We never make an investment decision based off an AI recommendation alone, but it's a helpful aide.”
That distinction matters when the inputs are incomplete. A startup’s pitch deck may call a customer a partner even though the customer has never paid. An AI summary can repeat the claim neatly. The underlying commercial relationship still needs to be understood.
A useful research workflow keeps three things separate:
- Evidence: The original filing, financial statement, customer conversation, or company document.
- Interpretation: Your explanation of what the evidence suggests.
- Open questions: Missing information and assumptions that could change the decision.
AI belongs in the organizing and drafting work. Accountability for the interpretation stays with the investor. Confidential founder materials also belong in systems authorized to handle them, rather than any convenient public chatbot.
Using AI to analyze investments is also a different decision from investing in AI companies. A growing technology market does not establish that a particular company has durable customer demand or that its investment terms are attractive. An AI startup still needs customers, distribution, and a credible way to keep its advantage.
2. Automated portfolios are making personalization more practical
Robo-advisers are automated digital investment advisory programs. They typically use information about your goals, time horizon, finances, and risk tolerance to recommend and manage a portfolio. In its robo-adviser bulletin, the Securities and Exchange Commission (SEC) explains both the model and its limits, including what a questionnaire captures and leaves out.
Automation can make recurring contributions and rebalancing easier to maintain. Rebalancing means adjusting holdings back toward a chosen mix after market movements change their proportions. Those tasks are different from deciding what mix suits your life.
Consider an operator whose salary and employer equity both depend on the technology sector. A portfolio built from a short risk questionnaire may miss that concentration if the system has no information about the employer shares. Adding startup investments can increase the same exposure, even when the companies have different names.
Personalization becomes useful when the inputs include the rest of your financial life. Cash needs, debt, job exposure, existing investments, fees, and taxes all affect the plan. A polished dashboard cannot fill in information it never received.
For angels, the lesson is to plan the startup allocation within the whole portfolio. An automated public-market account and a collection of private startup checks serve different needs and have different exit constraints.
3. Private-market access is widening through several distinct routes
Online infrastructure makes it easier to discover companies, collect commitments, handle documents, and pool smaller investments. The route still determines what you own, who makes decisions, and whether you’re eligible to participate.
Three routes illustrate the differences:
- Direct investing: You invest in a company and hold the security specified in its financing documents. You take responsibility for evaluating that company and the terms.
- Syndicates and special purpose vehicles: A syndicate brings investors together around a deal. A special purpose vehicle (SPV) is a separate entity that can pool their capital into an investment. Investors generally hold interests in the vehicle, whose documents set its fees, decision rights, and economics.
- Securities crowdfunding: Eligible companies can raise money online under Regulation Crowdfunding through a registered intermediary. The SEC’s crowdfunding rules allow participation by non-accredited investors, subject to investment limits and other requirements.
An accredited investor is someone who qualifies under securities rules through specified financial or professional criteria. Whether that status is required depends on the offering and its exemption from SEC registration requirements. A smaller check does not change the eligibility rules.
This is where learning and investing access need to stay distinct. In Angel Squad, our angel-investing community, you can learn from our approach, review curated deal flow, and compare questions with peers. Joining does not require accredited-investor status.
Participating in a particular investment may require it, depending on the offering and its exemption. Membership does not guarantee eligibility for a deal, an allocation, or a return.
The original appeal of small-check investing remains useful. You can limit the dollars exposed to one company and leave room for other decisions. But a small check still needs a reason to belong in your portfolio, and fees may matter more relative to the amount invested.
Secondary transactions add another distinction. A secondary purchase buys an existing holder’s interest rather than necessarily sending new capital to the company. A late-stage private-company purchase has a different information set and risk profile from backing a startup at pre-seed. Neither creates a guaranteed path to an initial public offering or a quick sale.
4. Tokenization is changing records and trading infrastructure
Tokenization represents an asset or an interest in an asset as a digital token recorded on a blockchain or similar shared ledger. It can change how ownership is recorded and transfers are processed. The legal and economic rights behind the token remain essential.
In September 2026, the SEC issued temporary, conditional relief from the legal definition of an exchange for certain blockchain-based venues trading tokenized public stocks. It also covers the dealer definition for qualifying participants supplying their own assets for trading. The order limits the stocks and trading volumes, leaves other securities rules in place, and does not make private-company tokens freely tradable.
The SEC staff’s tokenized-securities statement distinguishes issuer-sponsored securities from third-party structures. A third-party custodial token can represent a security entitlement, an indirect interest in an underlying security held in custody. A third-party synthetic token can instead represent the third party’s own security, with returns tied to another security’s value or related events rather than ownership in that company.
Imagine two products showing the same company name in an app. One represents an indirect interest in shares held by a custodian; the other is a separate issuer’s security that tracks those shares’ value. The interface can look similar while voting rights, claims on assets, and exposure to the intermediary differ.
The relevant investment facts are the issuer, the asset or obligation you hold, the custodian, the fees, and the conditions for transfer or redemption. A new recording system does not resolve weak business economics or create a willing buyer.
5. Communities can broaden judgment as well as access
Technology makes it easier for investors in different cities and industries to discuss a company. That is valuable when each person brings information the others lack.
A software engineer may recognize the difficulty of a technical claim. A sales leader may see that the company’s proposed buyer rarely controls the budget. Someone who has worked inside a hospital may understand why a convincing demo takes months to reach procurement.
Those perspectives can improve the questions asked during diligence. They can also help after an investment, through a customer introduction, a hiring referral, or feedback in an area the investor knows well. Useful operator experience remains part of the original promise of broader angel participation.
Group discussion has a failure mode, too. Several people repeating the lead investor’s opinion are still relying on one opinion. Write your own thesis before the discussion, then record what changed and which evidence changed it. Our startup diligence checklist gives that conversation a concrete starting point.
What better technology leaves unchanged
Startup investments remain speculative, illiquid, and long-term. Many bets may fail, and any single check can be lost entirely. The SEC’s private-placement bulletin highlights limited disclosure, restricted resale, and the possibility of holding an investment indefinitely.
Our general partner Elizabeth Yin put the portfolio principle plainly in Democratizing Knowledge: “Don't try to pick a co. Select a portfolio.” Broader access can help you assemble that portfolio, but diversification cannot assure a profit or protect against loss.
Different company names can also hide shared risks. Several startups may depend on the same customers, financing conditions, or technology supplier. Your job, employer equity, public investments, and private checks may all be exposed to the same downturn.
Portfolio construction includes the amount you can afford to lose, how long you can leave it invested, how you pace decisions, and whether you reserve capital for follow-on rounds. A follow-on is an additional investment in a company you already backed. Better software makes those choices easier to record; it does not make them for you.
Use three filters before committing capital
A repeatable decision process helps you assess an investment even when its technology or access route is new. Use three practical lenses: evidence, rights, and portfolio fit.
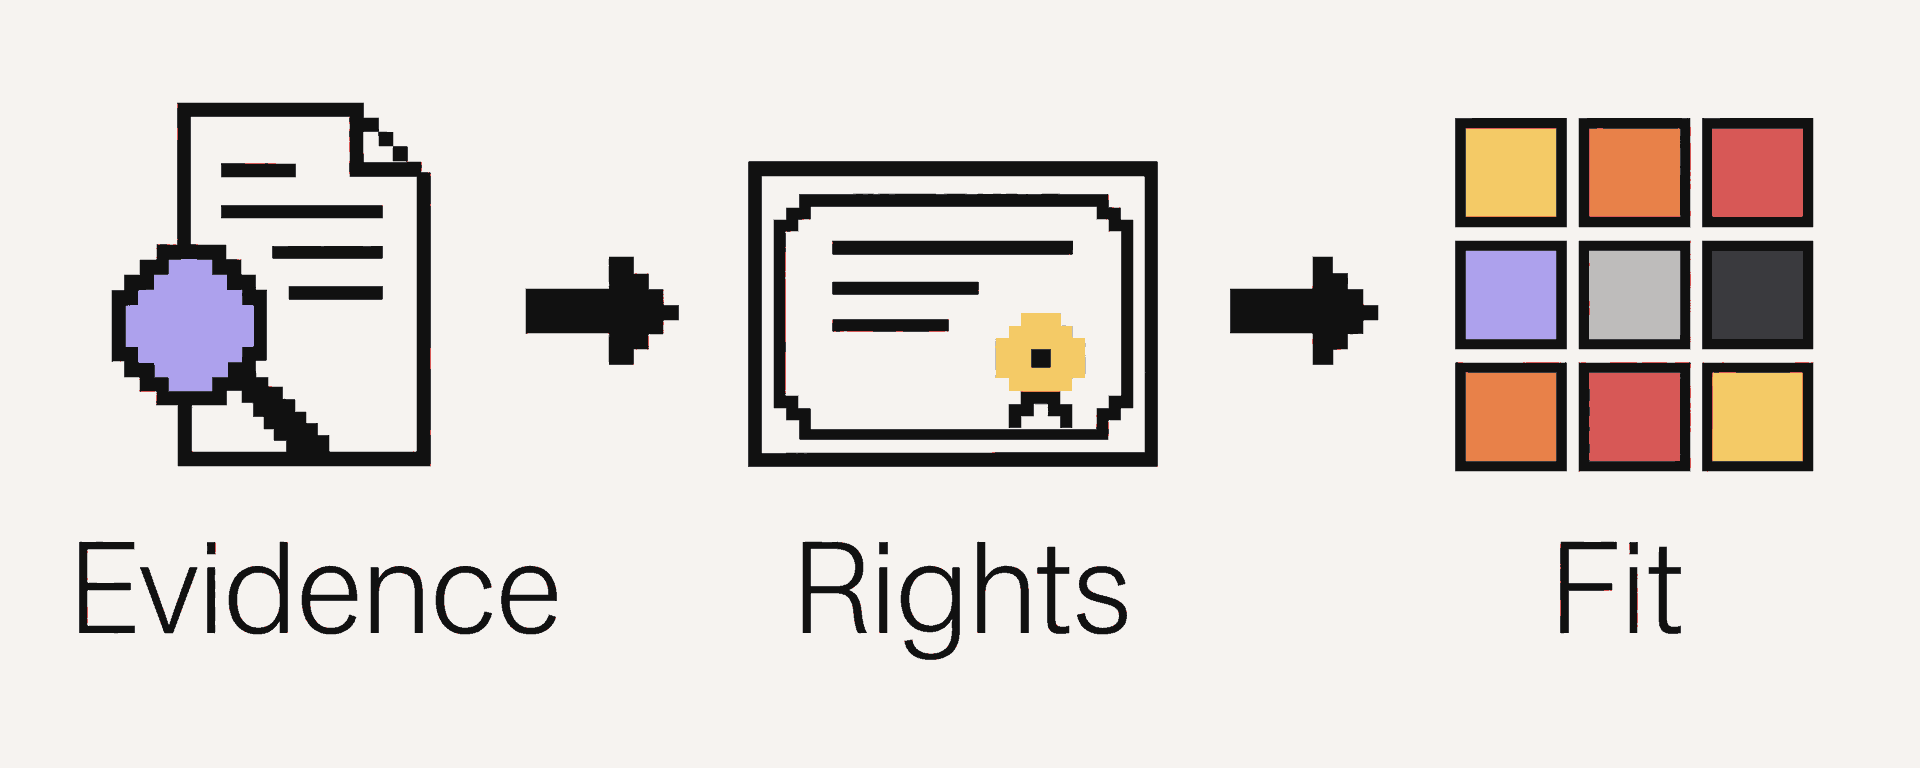
- Evidence: Name the source of each material claim and separate it from the interpretation. For a startup, that includes who pays, why customers return, and what the team has demonstrated. Record the strongest reason the thesis could fail.
- Rights: State what you would own, who controls it, what fees apply, and how money could come back to you. A direct company security, an SPV interest, and a token tied to another asset are different positions.
- Fit: Explain why the investment belongs alongside your existing holdings and obligations. Include loss capacity, liquidity needs, concentration, and any planned follow-ons.
A tool can improve one filter and leave the others untouched. An AI summary helps organize evidence. An online vehicle can make participation easier. A ledger can change the ownership record. You still need a satisfactory answer on all three before the investment makes sense for you.
If you want to practice that process with experienced operators, learn how we evaluate startups, and discuss curated opportunities, apply to Angel Squad.
This material is educational and does not constitute investment, legal, or tax advice. Startup investments are speculative, illiquid, long-term, and may result in a total loss. Obtain independent review of the governing documents and your circumstances from qualified legal, tax, and investment professionals.











