
Angel Investment Storytelling: Build Your Case
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A startup can leave you with a deck full of facts and no clear reason to invest. Angel investment storytelling turns those facts into reasoning another person can inspect. You need a repeatable way to connect insight, evidence, risk, and a decision, then adapt the result for your private memo, investment partners, co-investors, or limited partners (LPs).
What angel investment storytelling does
An investment story gives facts a causal order. It explains what you noticed, why it could matter, what you checked, and how that evidence led to today’s decision.
A founder’s story explains the company from inside the business. Your investor story evaluates it from outside. It should challenge the founder’s claims, name uncertainty, and show where your own judgment enters the case.
Most angel investments are speculative, illiquid, long-term bets, and many may return nothing. A polished narrative cannot turn uncertainty into predictability. Its job is to make your reasoning visible.
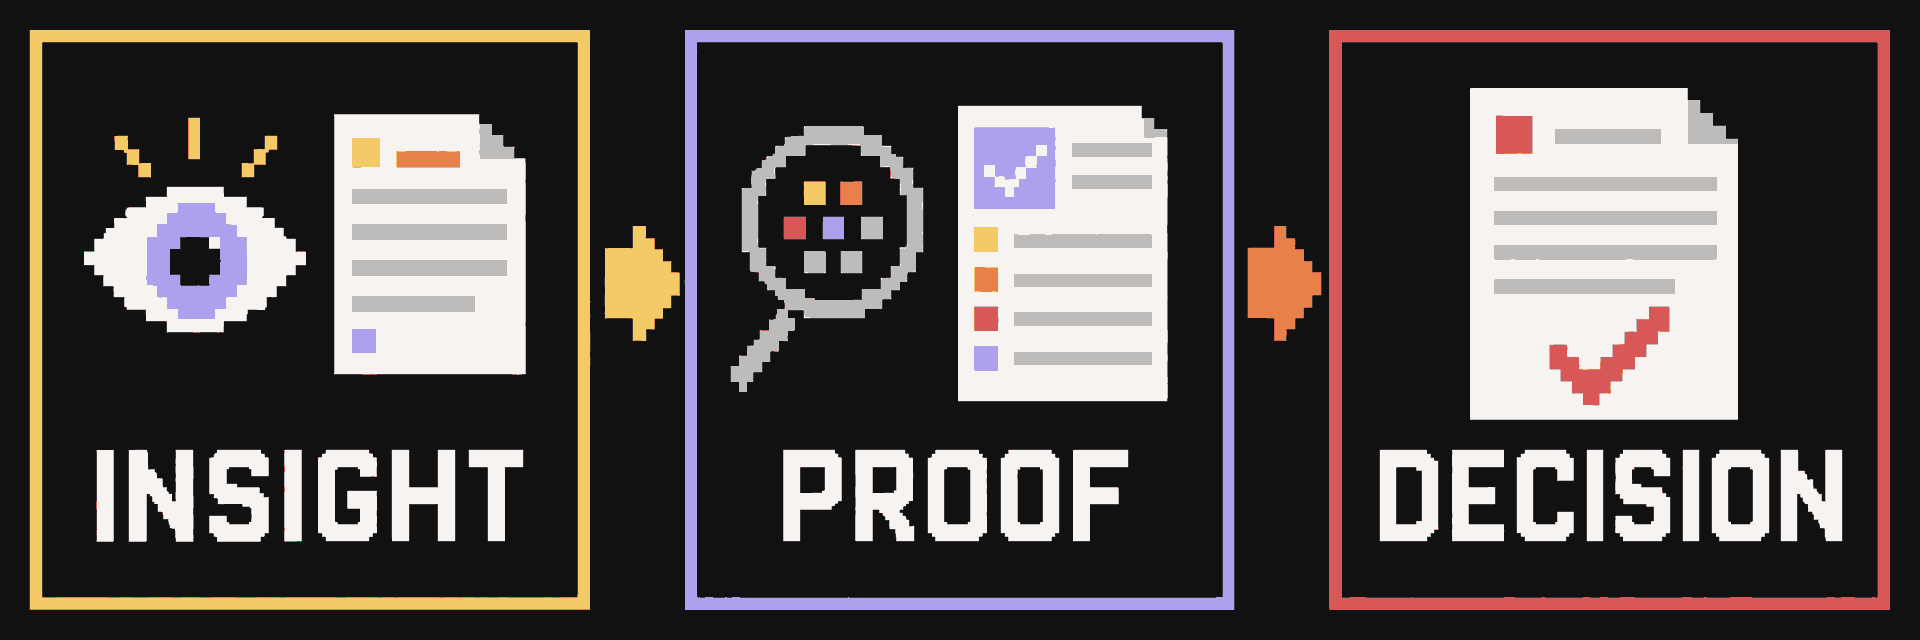
A useful deal narrative has three layers:
- Insight: the change or overlooked behavior you believe matters.
- Proof: the evidence you checked, plus the assumptions and unknowns that remain.
- Decision: why you will invest, pass, or wait, given your strategy and portfolio.
Choose the audience before you draft
The underlying facts stay fixed. The reader determines which question comes first and how much context belongs in the story.
A syndicate is a group of investors investing together in one deal.
- Future you: A personal memo preserves what you believed before the outcome was known. Record the date, decision, evidence, assumptions, counterargument, and what would change your mind.
- Investment partners or a committee: These readers need a recommendation they can challenge. Make disagreements explicit and show which unresolved issue matters most to the decision.
- Syndicate members or co-investors: They need a fair summary of the opportunity, material risks, your relationship to the company, potential conflicts, and direct access to the relevant terms and governing documents. Clear writing cannot replace their diligence.
- LPs: A deal story should show how the investment fits the fund’s stated strategy, portfolio construction, decision process, and post-investment work. One exciting company does not prove a repeatable fund strategy.
Different readers will also notice different risks. As our co-founder Elizabeth Yin writes in Democratizing Knowledge (Hustle Fund, 2021, PDF p. 43), “Investors use their life perspective to assess.” Audience awareness helps you anticipate questions. It should never change the facts to fit the room.
Build the narrative in six steps
1. Write the differentiated insight in one sentence
Start with the belief that makes the deal worth examining. “Artificial intelligence is growing” could describe thousands of companies. “Regional home-care agencies still coordinate last-minute caregiver replacements through phone trees because their scheduling systems do not handle local availability well” gives you a specific behavior to test.
A strong insight names a customer, a change, and a consequence. If the sentence could fit every startup in the category, keep working.
2. Draw the causal chain
Explain how the observation could create company value. Use plain links:
- The customer has a costly or frequent problem.
- The product changes that behavior.
- The change produces a result customers will pay for.
- The company has a plausible way to reach more of those customers.
- The team has an advantage in learning or executing faster than others.
Each link is a hypothesis. A big market does not repair a weak link between product use and customer value.
One of the lenses we use comes from our co-founder and general partner Eric Bahn’s investment thesis: “great execution meets high velocity.” Support that claim with the work a team shipped, the test it ran, the customer it won, and what it learned.
3. Label the source of every important claim
A clean story can make every sentence sound equally certain. Mark the inputs before you write the prose:
- Verified evidence: you checked a document, product, customer reference, or primary source.
- Founder claim: the company supplied the fact, and you have not independently confirmed it.
- Investor assumption: your interpretation of what may happen.
- Unknown: the answer is unavailable or too early to know.
Our guide to writing an investment memo goes deeper on preserving those distinctions. Keep them in the final narrative whenever they affect the decision.
4. Write the strongest counter-story
Give the downside a coherent causal chain too. The customer problem may be real while the startup struggles because onboarding requires too much service work. Early pilots may convert because the founder personally manages every account. An incumbent may copy the feature before the company finds repeatable distribution.
Ask which explanation also fits the current evidence. Then identify the next fact that would separate the positive case from the counter-story.
5. Make the portfolio decision
A company can be compelling and still fall outside your strategy. State the fit with your angel investing thesis, current exposure, check budget, follow-on plan, and ability to help.
End with invest, pass, or wait. A wait decision should name the evidence and trigger that will reopen the case.
6. Compress after the reasoning is complete
Write the personal memo first. It is the least forgiving version because you cannot hide behind audience enthusiasm. Then adapt it.
A partner memo puts the recommendation and open disagreement near the top. A syndicate note explains the company, insight, evidence, and risk in a few short sections. An LP update connects the deal to fund strategy and reports what has changed since the original thesis.
Elizabeth makes the learning value of this record explicit in Democratizing Knowledge (Hustle Fund, 2021, PDF p. 131): “The more disciplined you are in your thought process/rubric, the more you can improve over time.” The written story gives you something specific to revisit.
Worked example: from deal notes to investment story
The company, founder, customers, evidence, and decision in this example are fictional. The example is simplified for teaching and is not an investment recommendation.
ShiftForm sells scheduling software to independent home-care agencies. An angel’s raw notes might look like this:
- Observation: The founder managed caregiver scheduling for six years and saw agencies handle last-minute replacements through spreadsheets, calls, and text messages.
- Verified evidence: The investor reviewed the product, confirmed that five of eight pilots became paying customers, and spoke with two customers who said the product reduced weekly on-call coordination.
- Founder claim: Twenty-four more agencies are in the sales pipeline. The investor has not confirmed those conversations.
- Investor assumption: Onboarding can stay below two hours per agency as customer volume grows.
- Unknown: No customer has reached a second annual renewal.
- Counter-story: Existing scheduling platforms add similar workflows, while ShiftForm’s support workload grows faster than subscription revenue.
- Portfolio fit: The investor has home-care operating experience, a budget for high-risk early-stage checks, and no current company serving this buyer.
The core story becomes: independent home-care agencies have a recurring coordination problem that their existing systems handle poorly. A founder who lived that workflow built a narrower product, converted five pilots, and produced customer-reported time savings. The case depends on lightweight onboarding and retention, neither of which has been proved at scale.
Personal memo version
- Decision: Invest a small check within the fictional investor’s preset early-stage budget, subject to satisfactory review of the deal documents.
- Thesis: ShiftForm can win a focused group of independent agencies because it solves a frequent workflow the founder knows firsthand, and early pilots show willingness to pay.
- Evidence: Five of eight pilots converted. Two customer references confirmed lower coordination time. The investor tested the product.
- Key assumption: New agencies can launch without founder-led setup or heavy support.
- Strongest counterargument: Incumbents can copy the workflow and bundle it into broader scheduling products.
- Unknowns: Renewal behavior, sales-cycle length outside the founder’s network, and support cost at higher volume.
- Investor fit: The check fits the portfolio budget, and the investor can help evaluate channel partners in home care.
- Review trigger: Revisit the thesis after the first three annual renewals and ten customer onboardings completed by someone other than the founder.
This version preserves the decision and the conditions around it. Future results can test the onboarding and retention assumptions without rewriting the original reasoning.
Syndicate note version
The same facts can support a shorter note for possible co-investors:
- What the company does: ShiftForm helps independent home-care agencies fill last-minute caregiver shifts.
- Why I am paying attention: The founder ran this workflow for six years. Five of eight pilots became paying customers, and two customer references confirmed less weekly coordination work.
- What remains unproved: No customer has reached a second annual renewal. The largest risk is that onboarding and support stay labor-intensive as the customer base grows.
- Why I am participating: The deal fits my early-stage portfolio budget and my operating experience in home care. I plan to invest, subject to final document review.
- What each reader still needs: Review the exact offering terms, fees, carry (the share of investment profits paid to the syndicate lead), conflicts, eligibility requirements, company materials, and governing documents. Make an independent decision.
A syndicate note should include only information the issuer or lead has authorized for that audience. It gives another investor your reasoning and its limits. It should not borrow certainty from your decision or present your participation as proof of company quality.
Keep the story tied to evidence
A sharper label can reveal a real insight, or it can make a weak case sound new. Our Raise Millions guide uses a teaching example in which a founder reframes a media company for teachers as a data business. That framing changes the claim an investor must evaluate.
The diligence questions now concern the data itself. What information can the company collect with appropriate rights and consent? Does the data improve a product customers will buy? Is it hard to recreate? Can the company acquire and serve the audience at sustainable cost? The phrase “data business” supplies none of those answers.
Use the same discipline with every attractive narrative:
- trace each conclusion back to its source;
- separate current evidence from future plans;
- preserve the strongest disconfirming fact;
- state whose behavior must change for the thesis to work; and
- remove adjectives that do not change the decision.
Put the story under pressure
A narrative improves when another investor can find the weak link. In an open Warwick manuscript, Jean Clarke and Nick Llewellyn analyzed video of the question-and-answer sessions from 14 UK investment pitches. They observed four recurring interaction patterns and found that investor interventions, including collective questioning, could enable or constrain the founder’s story.
Their study describes what happened in live pitch exchanges. It did not test or prescribe the three-question peer-review exercise we use here.
For a practical review of your own investment case, ask a peer to challenge three points:
- Which sentence is doing the most work with the least evidence?
- What other explanation fits the same facts?
- Which missing fact could reverse the decision?
Inside Angel Squad, members can hear how peers with different operating backgrounds frame the same opportunity. The goal is clearer independent judgment. Consensus is optional.
Common ways an investment story fails
- The insight is generic. “Large market, strong team, great product” gives the reader no reason this company has an edge.
- Proof becomes scenery. A list of metrics has little value until you explain which hypothesis each metric supports or weakens.
- The counter-story disappears. A memo that cannot state the strongest case against the deal has become sales copy.
- The audience changes the facts. Reordering true information is fair. Hiding a material risk because one reader dislikes it is not.
- The story claims certainty. Early-stage investing contains long timelines, limited information, and a real chance of total loss.
- The syndicate note replaces diligence. A clear summary cannot substitute for customer work, source checks, conflict disclosure, or the governing documents.
Want sharper questions before your next check?
Clear deal narratives come from repeated decisions, direct feedback, and exposure to investors who notice different things. Apply to Angel Squad to learn with our team, review curated deal flow, and practice turning startup evidence into an investment case you can defend.
This content is educational and does not constitute investment, legal, tax, accounting, or valuation advice. Review the governing documents and seek guidance from qualified independent legal, tax, financial, and accounting professionals. Private startup investments are speculative, illiquid, long-term, and may result in total loss.











