
Exit Strategy for Angel Investors: From Check to Cash
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
This is general educational information, not legal, tax, investment, accounting, or valuation advice. Startup investments are speculative, illiquid, long-term, and can result in total loss. Past results and current marks do not guarantee future results. Outcomes depend on the governing documents, fees, carried interest, taxes, cap table, valuation policy, and timing. Review the governing documents and seek advice from qualified independent legal, tax, investment, accounting, and valuation professionals.
Getting into a startup investment is usually easier than getting out. A paper valuation can rise for years without putting cash in your account. Then an acquisition headline arrives, and the payout can still disappoint after debt, preferences, dilution, and deal terms. You need a plan that starts before the check and survives the messy reality of minority ownership.
What an exit strategy means for an angel investor
An exit strategy for angel investors is a plan for how an illiquid startup security could become cash, what could reduce the payout, and which decisions remain yours along the way.
That definition matters. Most angels cannot choose when a company sells, force an initial public offering (IPO), or make another investor buy their shares. Your practical strategy has two parts:
- Underwrite plausible liquidity paths before investing. Identify who might buy the company, whether a secondary sale could ever be feasible, and what outcome the entry price and capital structure would require.
- Protect your options after investing. Track your security, dilution, preference stack, transfer restrictions, tax records, and follow-on choices. Help the company become attractive and ready for diligence without pushing founders toward a premature sale.
Headline exit data can give investors a false sense of liquidity. The Q2 2026 Venture Monitor reported $1.83 trillion in quarterly US venture exit value, yet said that value was overwhelmingly concentrated in one newly public company. A record quarter for the market did little for investors who did not own that outlier.
The five paths from private shares to cash
The same five routes appear in most exit plans, but they do not give you equal control or the same kind of proceeds:
- The startup is acquired.
- The startup goes public and you later sell shares.
- You sell in a company-approved secondary transaction or tender offer.
- The company repurchases shares or pays dividends.
- The startup winds down and distributes any residual value.
1. Acquisition
An acquisition is the clearest route to liquidity for many venture-backed startups. A buyer may want the product, team, customers, intellectual property, data, distribution, or strategic position.
The press-release price is only the starting point. Your proceeds can arrive as cash, buyer stock, or both. Some consideration may sit in escrow, depend on an earnout, or be released after closing conditions are satisfied. Debt, transaction expenses, and senior claims can reduce what remains for shareholders.
Minority angels rarely negotiate the sale. Voting agreements and drag-along provisions may allow the required holders to approve a deal and bind other shareholders. Your job is to understand what you own, respond to closing paperwork promptly, and review any release, joinder, tax form, or election before signing.
2. IPO or direct listing
Going public creates a traded security. It does not necessarily create cash for an angel on listing day.
Your preferred shares may convert to common stock, and your position may be subject to contractual lockups, securities-law restrictions, or company trading policies. The SEC says most IPO lockup agreements restrict insider sales for 180 days, although the actual terms vary. The price can move sharply before you are allowed to sell.
Plan the sale decision before the lockup expires. Decide whether you need immediate diversification, want to sell in stages, or can tolerate continued concentration. Then confirm the number of unrestricted shares, the process for removing any restrictive legend, and the tax consequences with independent advisers.
3. Secondary sale or tender offer
A secondary sale transfers your existing security to another buyer while the company stays private. It can happen in a financing, through a company-run tender offer, or as a direct transaction between a holder and an approved buyer.
It is an option, never an entitlement. The SEC notes that private-company securities are often illiquid and may not be freely traded. Federal and state securities rules still apply. Your investment documents may also require company or board consent, give the company or other holders a right of first refusal, or prohibit certain buyers.
Even when a sale is allowed, price is only one term. Check fees, information rights, representations, tax treatment, settlement timing, and whether you are selling all or part of the position. A lower price may be rational if partial liquidity meaningfully reduces concentration. It can also be a bad trade if the discount is steep and the company is close to a credible exit.
4. Buyback, redemption, or dividends
A profitable company may repurchase shares, redeem a class of securities, or distribute cash. These routes can suit a durable business that does not need to sell or go public.
Do not make them your base case unless your documents create a specific right and the company can legally and financially honor it. A founder's willingness to buy you out is not the same as a funded obligation. Dividends also compete with hiring, product development, debt service, and other uses of cash.
5. Wind-down or asset sale
A shutdown is an exit from the cap table, even when it is not a profitable exit. The company may sell equipment, code, patents, domains, or customer contracts and distribute whatever remains after creditors and senior claims.
Common shareholders often receive nothing. A Simple Agreement for Future Equity (SAFE) may have a dissolution payment priority above common stock but below debt and other creditor claims. The actual instrument controls.
Preserve the dissolution notice, final cap table, tax documents, and any statement showing what happened to the security. A company that quietly stops operating can leave investors without the evidence needed to support a tax position.
Your payout follows the documents, not the headline
Four layers determine what reaches you in an acquisition or wind-down.
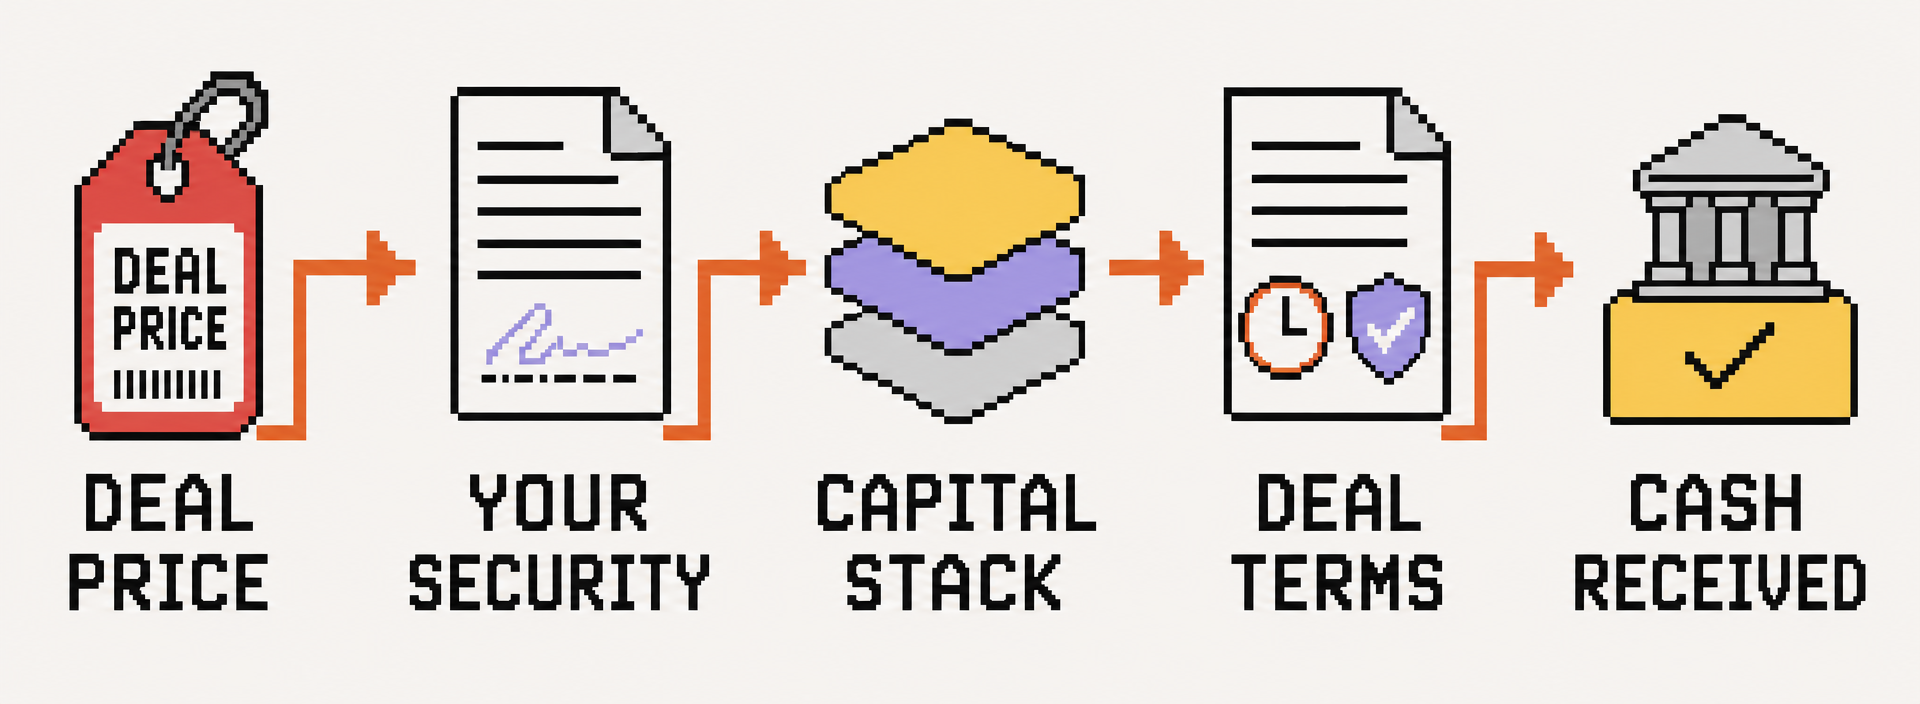
- The form of your investment. Common stock, preferred stock, SAFEs, convertible notes, and special purpose vehicle (SPV) interests have different rights. A standard US Y Combinator post-money SAFE that has not converted is designed to receive the greater of its purchase amount or as-converted proceeds in a liquidity event, subject to its priority. Modified SAFEs can work differently.
- The capital stack. Debt and creditor claims sit ahead of equity. Preferred investors may have seniority over other preferred rounds. Our guide to liquidation preferences explains how 1x, participating, and senior preferences change the waterfall.
- Dilution. New shares, SAFEs, options, and financing rounds can reduce your percentage. A rising company valuation does not tell you what fraction of the exit you still own.
- Deal consideration. Cash at closing, buyer stock, escrow, holdbacks, earnouts, and contingent payments have different timing and risk. Gross proceeds and cash in your bank are not the same number.
Ask for a waterfall prepared from the closing cap table when a transaction occurs. It should show each class, conversion decision, preference, deduction, and payment timing. A back-of-the-envelope ownership percentage is not enough.
Build the strategy before you invest
Add an exit page to every investment memo. It should answer seven questions.
1. What outcome fits the business?
Name plausible acquirer categories and the strategic asset each would value. For a niche software company, a modest strategic sale may be more credible than an IPO. For a company attacking a huge market with strong growth, remaining independent may preserve more upside.
Avoid asking founders for a promised exit date. Ask what they want to build, which companies have bought comparable assets, and what milestones would create strategic interest.
2. Does the entry price leave room for a meaningful outcome?
Compare the post-money valuation with credible exit ranges in the sector. Then account for future dilution and preferences. A company can succeed operationally while producing a weak return for an early investor who entered at an aggressive price.
3. What security will you own at exit?
Read the liquidity-event, dissolution, conversion, transfer, information-rights, and amendment provisions. For an SPV, read both the underlying company documents and the vehicle agreement. Fees and carried interest can make the SPV investor's net proceeds different from the direct holder's gross proceeds.
4. What already sits ahead of you?
Review existing debt, preferred rounds, outstanding SAFEs and notes, option pools, and any unusual senior or participating preferences. Repeat this review after major financings. A later round can change the exit economics without changing your original certificate.
5. What choices will still be yours?
Information rights can help you monitor the company. Pro rata rights can let you buy enough in a later financing to maintain ownership. Neither creates liquidity.
Treat every follow-on check as a fresh allocation decision. Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge (p. 287), “Decisions are never in isolation - they are a comparison game.” Compare the follow-on with new deals, cash reserves, and the additional concentration it creates.
6. Could a secondary ever be feasible?
Read the right of first refusal, co-sale, board-approval, and other transfer provisions. Ask how the company has handled tender offers or secondary requests, without treating past approvals as a promise. Small, early positions may attract no buyers even when a transfer is technically allowed.
7. What records will taxes require?
Keep purchase documents, wire confirmations, cap tables, conversion notices, issuer details, and every distribution statement from day one. Qualified Small Business Stock (QSBS) under Internal Revenue Code Section 1202 may exclude some eligible federal gain, but eligibility depends on the taxpayer, issuer, business, issuance, holding period, and transaction.
For qualifying stock acquired after July 4, 2025, the 2025 federal law introduced a 50% exclusion after three years, 75% after four years, and 100% after five years, while raising the per-issuer dollar limit and issuer-asset threshold. SAFE conversion and acquisition structures can complicate the start date and qualification. Get independent tax advice before a sale, when there may still be time to act.
Members of Angel Squad learn with other operators and investors while reviewing curated opportunities. That gives you a place to pressure-test exit assumptions, security terms, preference risk, and follow-on choices before you commit capital.
Manage exits at the portfolio level
Exit timing is lumpy. Shutdowns may appear early, while the strongest companies can remain private for years. One acquisition can return cash while many other positions remain marked up and illiquid.
That is why exit planning cannot rescue an overconcentrated portfolio. Elizabeth Yin puts it bluntly in Democratizing Knowledge (p. 130): “Don't try to pick a co. Select a portfolio.” Set a total angel-investing budget, size initial checks consistently, spread commitments over time, and reserve only the follow-on capital your strategy calls for. Our portfolio management guide shows how to track that system.
After each check, maintain a simple exit file:
- Record the security, purchase date, issuer, holder of record, and governing documents.
- Update share counts and preference seniority after financings.
- Separate realized cash, unrealized marks, and written-off positions.
- Log transfer restrictions and any company-run liquidity programs.
- Revisit likely buyer categories when the product or market changes.
- Keep contact details current for the company, SPV manager, transfer agent, and advisers.
When an exit opportunity arrives
Move quickly, but do not let the deadline replace diligence. Get clear answers to these questions:
- What are you being asked to approve, waive, release, or represent?
- What security and share count does the buyer recognize?
- Where do you sit in the final waterfall?
- How much is cash at closing, buyer stock, escrow, or contingent consideration?
- What fees, carried interest, withholding, or transaction expenses apply?
- When will each payment arrive, and who will report it for tax purposes?
- If you have a choice, what concentration and liquidity remain after a partial sale?
Your exit strategy did its job if these answers are already organized when the email lands. You cannot schedule the liquidity event. You can avoid discovering your economics for the first time at closing.
Ready to build that discipline with investors who have seen the documents, tradeoffs, and long waits? Apply to Angel Squad.











