
Unit Economics for Startups: A Complete Worked Example
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Revenue growth can hide a loss on every customer, order, or transaction. Unit economics strips a business down to one repeatable unit so you can see whether growth creates cash or consumes it. The useful work starts with choosing the right unit, using consistent inputs, and stress-testing the assumptions as acquisition gets harder.
What unit economics measures
Unit economics measures the revenue and direct or variable costs attached to the smallest repeatable part of a business. The unit depends on how the company earns money:
- A software-as-a-service (SaaS) company may use one paid account for one month.
- An ecommerce company may use one order, then track the customer across repeat orders.
- A marketplace may use one completed transaction.
- A delivery company may use one fulfilled order.
A useful unit connects an action to an economic result. “One app user” tells you little if most users never pay. “One completed paid booking” gives you revenue, variable cost, and a basis for comparison.
Six calculations usually carry most of the model:
- Unit gross profit: revenue per unit minus cost of goods sold (COGS).
- Gross margin: unit gross profit divided by revenue per unit.
- Customer acquisition cost (CAC): sales and marketing cost divided by new customers acquired in the same period.
- CAC payback period: CAC divided by monthly gross profit or contribution profit from a customer.
- Lifetime value (LTV): the gross profit expected from a customer over the relationship.
- LTV/CAC: lifetime value divided by customer acquisition cost.
Gross profit and contribution profit are different. Gross profit subtracts COGS. Contribution profit goes further by subtracting other variable costs, such as payment processing, usage-based support, refunds, or fulfillment costs that the company does not classify as COGS. Pick one basis, label it, and use it consistently.
A worked unit economics startup example
Consider CloudLedger, a fictional business-to-business (B2B) SaaS company. The example is hypothetical and simplified. It uses steady monthly averages, ignores expansion revenue and discounting, and treats customer churn as constant.
CloudLedger starts with these assumptions:
- One unit is one paid account for one month.
- Average revenue per account is $100 per month.
- Direct hosting, payment, and service costs are $20 per account per month.
- Fully loaded sales and marketing spend is $30,000 per month.
- The company acquires 100 new accounts per month.
- Monthly customer churn is 4%.
- Fixed operating expenses outside sales and marketing are $60,000 per month.
Here is the calculation from one unit to the company-level implication.
- Find monthly gross profit per account. CloudLedger earns $100 and incurs $20 of direct costs. Monthly gross profit is $80. Gross margin is $80 divided by $100, or 80%.
- Calculate CAC. The company spends $30,000 to acquire 100 new accounts. Fully loaded CAC is $300 per account.
- Find CAC payback. Divide the $300 CAC by $80 in monthly gross profit. CloudLedger recovers its acquisition cost in 3.75 months, assuming the customer stays and the margin holds.
- Estimate LTV. A common shortcut for a subscription business is monthly gross profit divided by monthly customer churn. The simplified LTV is $80 divided by 4%, or $2,000. This shortcut becomes unreliable when churn, pricing, expansion, or customer behavior varies sharply. Mature cohort data gives a better estimate.
- Compare LTV with CAC. Divide the $2,000 LTV by the $300 CAC. The simplified LTV/CAC ratio is 6.7x.
- Layer in fixed costs. Unit economics does not show company profit by itself. CloudLedger needs 750 active accounts to cover $60,000 in fixed monthly operating expenses before current acquisition spending. If it keeps spending $30,000 to acquire 100 accounts each month, that simple operating break-even rises to 1,125 active accounts: $90,000 divided by $80. Churn, growth timing, annual prepayments, and working capital will change the cash path.
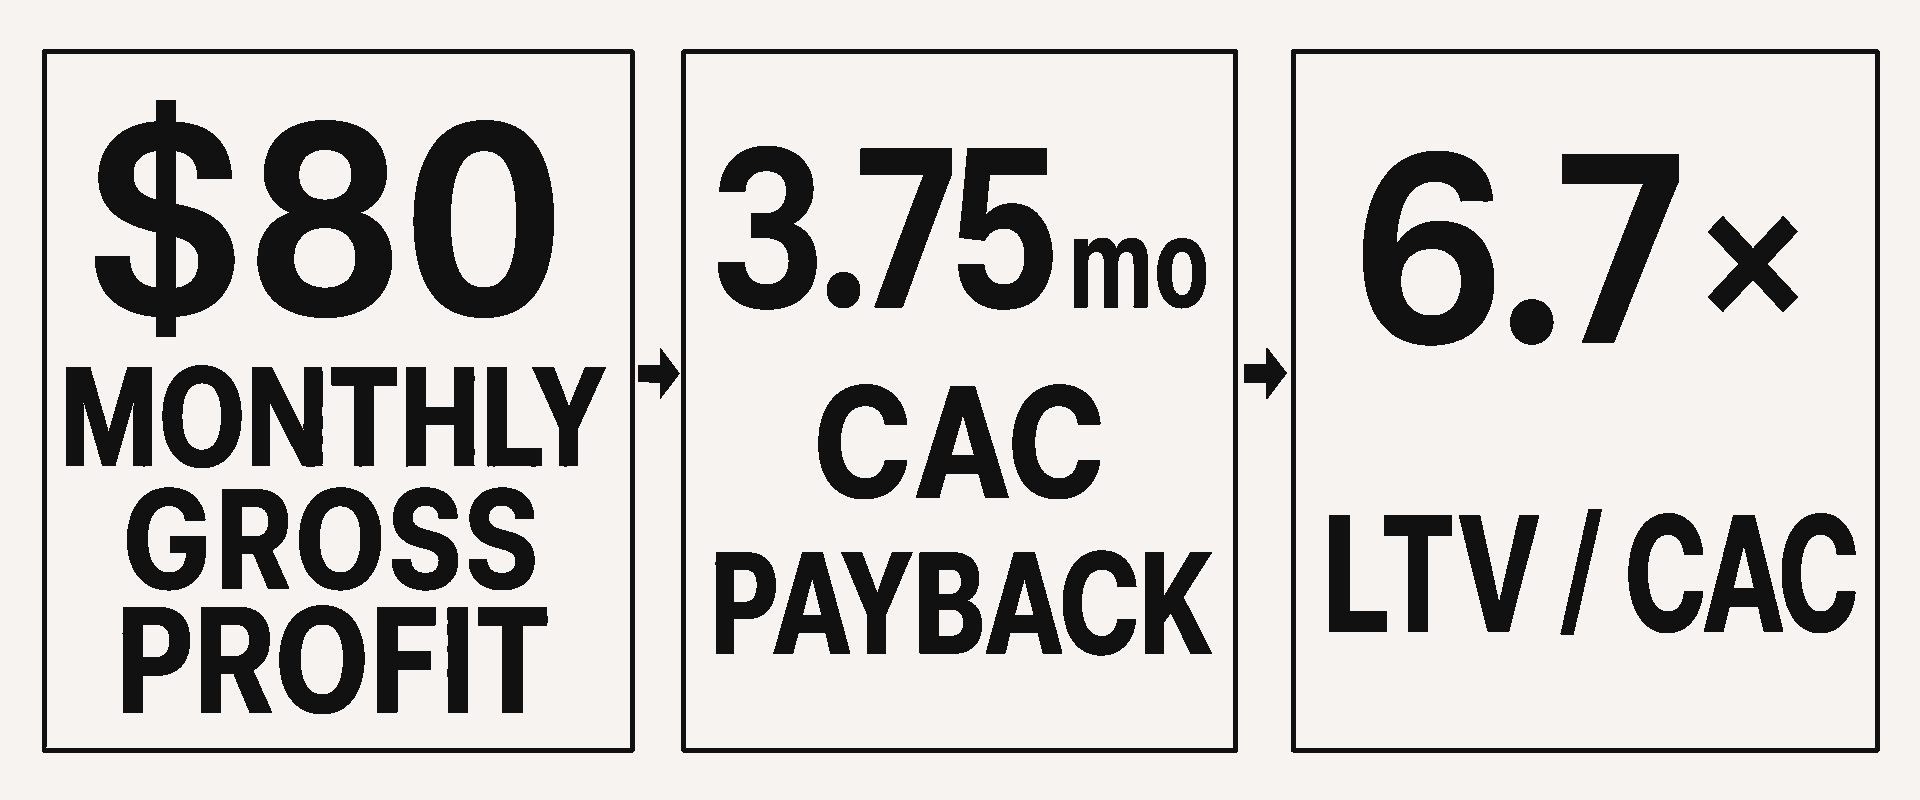
The base case looks healthy. It is still a snapshot built from assumptions. The decision gets more useful when the inputs move.
Stress-test CAC and retention
Our co-founder and general partner Elizabeth Yin writes, “There’s no holy grail number” for CAC. A ratio can look attractive today and deteriorate as a startup spends beyond its cheapest channels or reaches customers with weaker retention.
CloudLedger's model changes quickly under three small tests:
- CAC rises by 50%. At a $450 CAC, payback stretches from 3.75 to 5.6 months. LTV/CAC falls from 6.7x to 4.4x.
- Monthly churn rises to 6%. Simplified LTV falls from $2,000 to about $1,333. LTV/CAC also falls to 4.4x, even though CAC and initial margin have not changed.
- Both happen together. A $450 CAC and 6% churn produce a 5.6-month payback and a 3.0x LTV/CAC ratio.
The combined case still clears acquisition cost in this simplified model, but the cushion is less than half of the base case. More cash remains tied up for longer, and a further change in price, margin, or retention has more room to hurt.
Elizabeth Yin also writes, “Payback period is a big factor - that's largely driven by capital access.” The ratio describes eventual value under the assumptions. Payback shows how long the company must finance growth before that value arrives.
Gross margin does not prove acquisition works
An 80% gross margin sounds excellent. It says nothing about how much the company spends to acquire the account.
If CloudLedger's CAC rose to $2,000 while monthly gross profit stayed at $80, payback would stretch to 25 months. The gross margin would still be 80%. The acquisition model would demand far more cash and expose the company to nearly two years of churn risk before recovering CAC.
The reverse can also happen. An ecommerce company with a 35% gross margin may have viable unit economics if acquisition is cheap, the first order contributes cash, and repeat purchases are strong. Margin, CAC, retention, and payback belong in the same view.
Contribution margin can make that view more honest. If CloudLedger incurs $8 of variable onboarding and support cost outside COGS, contribution profit is $72 per month rather than $80. Contribution-based payback becomes 4.2 months. The accounting classification matters less than a consistent definition that captures the relevant cash burden.
Adjust the model to the business type
The calculation sequence stays similar across startups, but each business model needs a different unit and cost boundary.
SaaS
Track an account or seat over time. Use monthly recurring revenue, direct service costs, CAC, payback, and retention by acquisition cohort. Separate customer churn from revenue churn because retained accounts may expand or contract.
The gross-profit-divided-by-churn shortcut is an estimate, not observed LTV. Early cohorts may have too little history to support a lifetime claim. Show realized retention first, then label the forecast and its assumptions.
Ecommerce
Start with one order and one newly acquired customer. Subtract product cost, freight, fulfillment, payment fees, discounts, returns, and other order-level costs. Then follow the customer into later orders.
A blended CAC can hide the difference between new and returning buyers. Channel-level CAC and repeat-purchase cohorts show whether the company is buying durable customer relationships or renting one-time orders.
Marketplaces and delivery businesses
Use one completed transaction or fulfilled order. Revenue is the company's take-rate revenue, not gross merchandise value. Subtract payment costs, incentives, refunds, support, insurance, and variable operations tied to the transaction.
Supply and demand may have separate acquisition costs. A marketplace can show positive transaction contribution while spending heavily to recruit one side of the network. Both sides belong in the path to scale.
Keep clean math from lying
Most unit-economics errors come from inconsistent definitions or averages that hide the trend. Use these checks before trusting the output:
- Segment the data. Compare CAC, margin, and retention by acquisition month, channel, customer type, and geography. Our customer-acquisition thesis explains why cheap early channels may offer little evidence about acquisition at scale.
- Use a fully loaded CAC. Include the sales and marketing costs required to acquire customers, then show paid-media CAC separately when it helps channel decisions. Keep the inclusion rules stable across periods.
- Match the time windows. CAC from this quarter and retention from a much older cohort can create a ratio that never existed for one group of customers.
- Separate evidence from forecast. Label observed gross margin, CAC, and retention. Put estimates for future pricing, churn, and repeat purchase in their own range.
- Follow cohorts. Blended averages can improve while new customers get worse, especially when strong older cohorts dominate the total.
- Model cash timing. Annual contracts, inventory, payment terms, refunds, and delayed marketplace payouts can create a cash squeeze even when eventual unit contribution is positive.
A model with ranges is usually more useful than a polished point estimate. Show the base case, the downside case, and the assumption that causes the biggest change.
How investors should use unit economics
Founders use unit economics to set prices, choose channels, and manage spend. Investors use the same model to judge whether growth is likely to become more or less capital-intensive.
Five signals deserve attention:
- A stable unit definition. The founder uses the same customer, order, or transaction definition across the deck and source data.
- Cohort evidence. Retention and contribution remain credible as the company reaches customers beyond the founding network.
- Channel clarity. The team knows which channels drive CAC and customer quality instead of relying on one blended number.
- Sensitivity awareness. The founder can explain what happens when CAC, churn, price, or direct cost moves.
- A financed payback period. The fundraising plan covers the cash required to reach payback at the intended growth rate.
Use our unit economics diligence questions when you need a meeting-ready checklist for testing a founder's answers. Unit economics also sits inside a wider startup evaluation framework that includes the team, market, product, traction, and deal terms.
Strong unit economics cannot eliminate team, market, financing, execution, or timing risk. Most early-stage bets may fail, and a neat spreadsheet does not change that. It improves one part of the decision.
Common unit economics questions
What is a good LTV/CAC ratio?
There is no universal ratio. A higher ratio creates more room for acquisition costs to rise, while a very high estimate may reflect early retention data, an inflated LTV, or underinvestment in a working channel. Read the ratio with gross margin, payback, cohort maturity, and capital needs.
Can a pre-revenue startup calculate unit economics?
Yes, as a hypothesis. The founder can model expected price, direct cost, acquisition cost, conversion, and retention as ranges. Those numbers should be labeled as assumptions and replaced with observed cohort data as customers arrive.
Should sales and marketing salaries count in CAC?
A fully loaded CAC should include the people, programs, and tools required to acquire customers. A company may also show media-only or channel CAC for day-to-day optimization. Label each version so readers know what the numerator contains.
Practice the math before the next pitch
If you want to turn this model into a repeatable investing habit, apply to Angel Squad. You can use the math while reviewing curated startup opportunities and compare your read with other operators and investors.











