
Sector-Focused Venture Capital: Should You Specialize?
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Sector-focused venture capital concentrates a firm's startup investing in an industry, technology domain, or related set of problems. For an angel investor, the decision is how narrowly to focus your own investing given your experience, relationships, and existing financial exposure. Comparing specialist and generalist approaches helps you understand where your knowledge is useful and where you'll need help.
A fund's mandate and an angel's focus are different
A venture capital fund invests pooled capital on behalf of its investors. Its mandate defines the scope it can pursue, which may include sector, company stage, and geography. A specialist fund might concentrate on financial technology or industrial automation. A generalist, sometimes called sector-agnostic, fund considers companies across several industries within its other boundaries.
A generalist fund still has boundaries. A fund can be sector-agnostic while investing only in pre-seed companies, very early startups, in one region. A specialist can cover several technologies that solve problems for the same industry.
An angel invests personal capital and can choose a focus without operating a VC fund. You can study clinic software in depth while retaining a broader startup portfolio. You can also remain a generalist and bring in specialists for unfamiliar deals.
Separate the scope of your learning from the concentration of your money. Understanding one market well doesn't require putting most of your startup budget into it.
Specialist versus generalist venture investing
Specialists build depth within a bounded market. Generalists compare a wider opportunity set. Both need diligence, the work of investigating a company before investing, to evaluate founders, customer demand, competition, financing needs, price, and investment terms.
The tradeoffs show up in six parts of the work:
- Expertise. A specialist may recognize a buyer's workflow or a technical constraint from firsthand experience. A generalist may recognize a distribution model that worked in another industry. Either perspective can miss something important, particularly when familiarity substitutes for evidence.
- Opportunity breadth. A specialist can spend more time understanding fewer markets, but passes on companies outside that scope. A generalist can pursue a wider range of companies, with more learning required when a deal involves an unfamiliar technology or buyer.
- Sourcing. Specialists can meet founders through professional associations, former colleagues, customer networks, and industry gatherings. Generalists can build relationships across founder communities and other investors. Neither route guarantees an opportunity to invest or favorable terms.
- Diligence. A specialist's knowledge can make customer conversations more specific. A generalist may need an outside reviewer earlier. Both need evidence that goes beyond the founder's pitch, including evidence that could undermine the investment case.
- Founder support. A specialist might introduce a relevant buyer, explain an implementation obstacle, or help recruit an industry operator. A generalist might help with hiring, fundraising, or distribution across markets. Useful support depends on actual relationships and available time.
- Blind spots. Specialists can become attached to familiar solutions and shared industry assumptions. Generalists can underestimate sector-specific constraints. Independent reviewers help challenge those assumptions; they don't eliminate risk or take responsibility for your decision.
Specialist and generalist describe approaches. Neither label establishes investor quality or better returns. Domain experience also doesn't establish whether a particular company's price or investment terms are attractive.
Decide how much focus your experience supports
Start with a narrow description of the work you understand. “Healthcare” spans drug development, insurance, medical devices, and administrative software. Experience in one part doesn't confer expertise across all of them.
Use these six questions to define a focus you can defend.
1. What do you know firsthand?
Name the customer problem you've worked on, the product you've built or sold, or the purchasing decision you've participated in. Include the type of organization and geography. Selling software to a U.S. outpatient clinic gives you different knowledge from selling to a national hospital system.
Separate recent experience from assumptions you inherited years ago. A course or conference can help fill a gap, but attendance alone doesn't establish competence.
2. What evidence can you interpret?
List the claims you can evaluate with relevant evidence. An operations leader may understand whether a product fits the workflow. A technical specialist may understand performance limitations. A former buyer may understand budget ownership and procurement.
Define the evidence you'd need for each claim: observed usage, customer conversations, implementation records, or technical results. Deck volume is a record of exposure, not proof of expertise.
3. How will you meet founders and customers?
Write down the relationships and communities that could produce relevant conversations. Include people outside your immediate professional circle, such as customers who rejected a product or operators at smaller organizations.
A steady stream of referrals from the same few people can repeat the same assumptions. Track where opportunities come from so you can recognize that pattern. Respect confidentiality and your employer's policies when drawing on professional relationships.
4. What help can you realistically provide?
Choose a contribution you can deliver with the founder's agreement. That might be an introduction to a potential design partner, feedback on a purchasing proposal, or help defining an operations role.
“I know healthcare” is too vague. “I can explain how clinic managers evaluate a scheduling-system change” gives the founder a useful expectation. An introduction still needs both parties' consent, and it may lead nowhere.
5. Where does your expertise stop?
State the questions you can't answer, and identify the kind of independent specialist needed. Commercial experience with healthcare software doesn't qualify you to assess clinical evidence, regulatory status, cybersecurity, or an investment agreement.
At Angel Squad, we combine investing education, curated deal flow, and peer discussion. Comparing how other angels interpret a deal can help you recognize gaps in your reasoning. Participation doesn't replace company-specific technical, financial, or legal diligence, and there's no obligation to invest.
6. What exposure would this add to your life?
Consider your salary, employer stock, other investments, and existing startup holdings together. If you work for a financial-technology company, adding several fintech investments may increase your dependence on the same industry's fortunes.
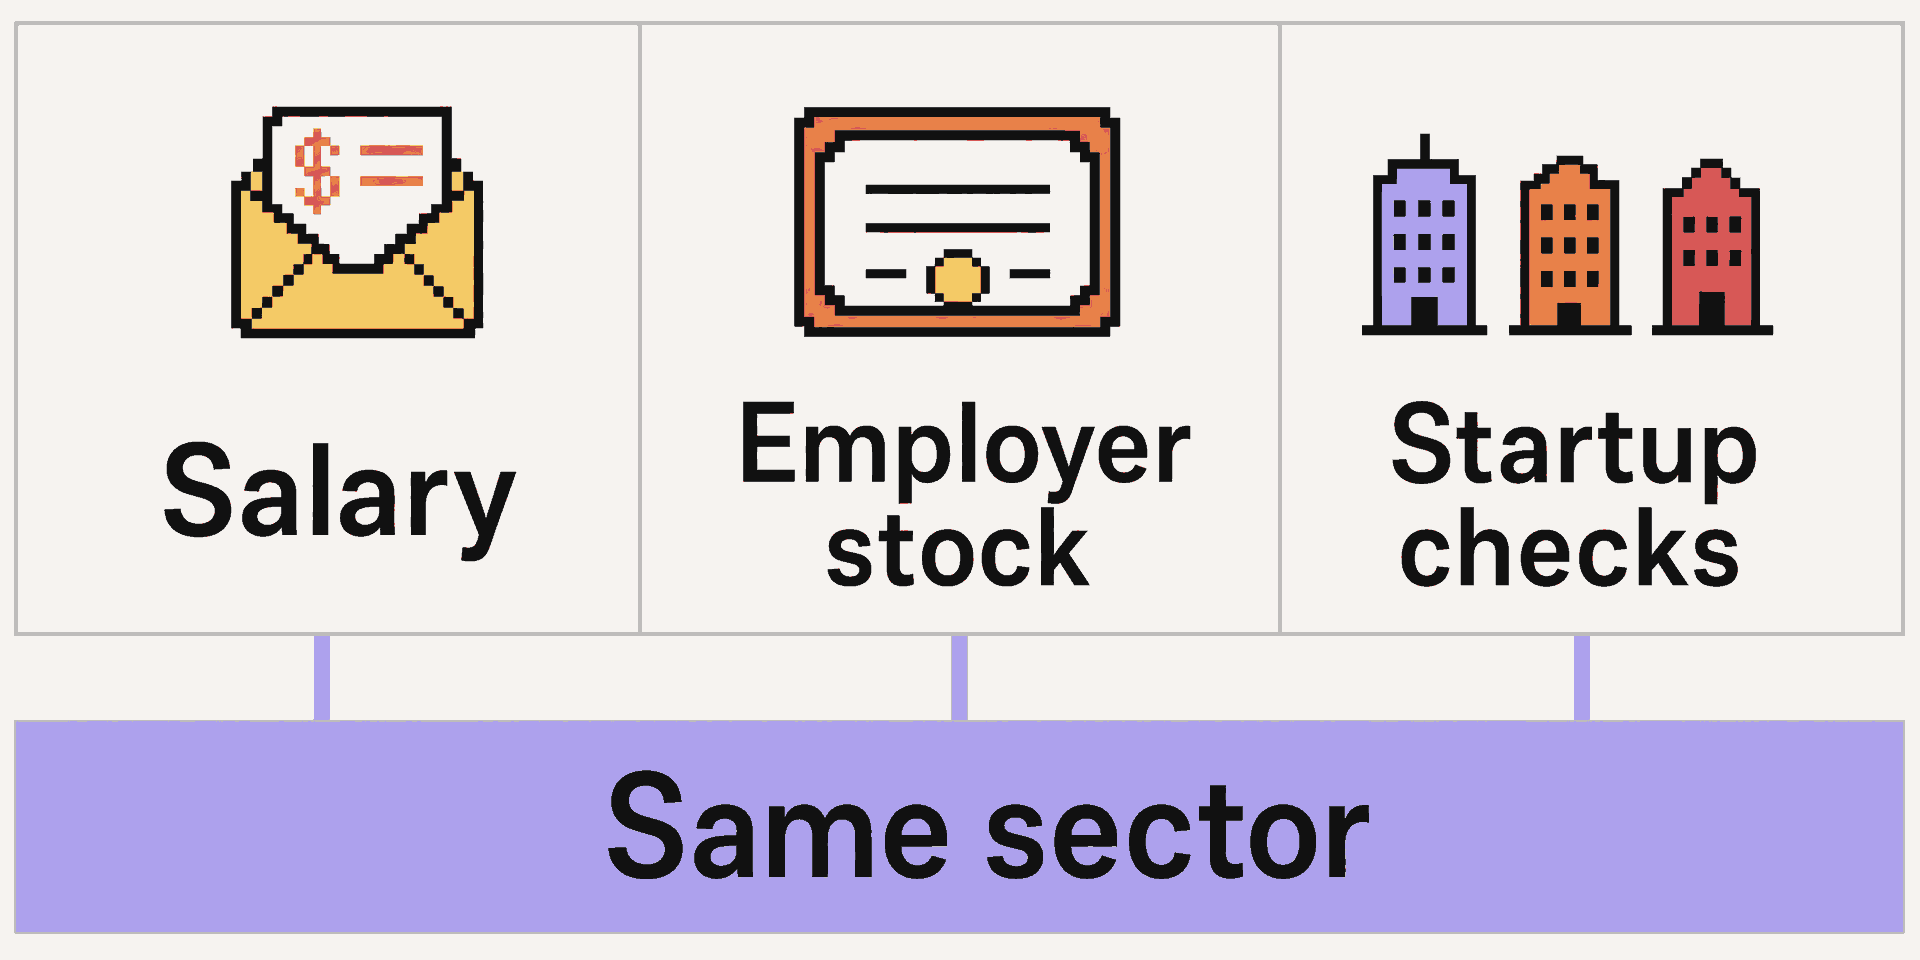
Include the time commitment, too. A narrow focus can consume your learning and sourcing time even when you invest little money. Passing on opportunities outside it is part of that choice.
A focused approach is more credible when you have current experience, relevant evidence, useful relationships, and explicit boundaries. If several of those are missing, a broader learning period or a narrower scope can be a better fit. You can build understanding through deal reviews without writing a check.
Hypothetical diligence example: clinic scheduling software
Suppose you've managed operations for outpatient clinics. A startup pitches software that fills canceled appointments and reduces staff scheduling work. This is a hypothetical example, not a company case study or an investment recommendation.
Your experience helps you investigate how the product would work inside a clinic. The diligence still needs evidence beyond your own experience.
- User and workflow. Front-desk staff use the product. Ask how they fill a cancellation today, which systems they work in, and what happens when the new software fails. Observe whether the product removes work or creates another queue staff must manage.
- Buyer and budget. The clinic manager likes the demo, but the practice owner controls spending. Establish who signs, which budget pays, and what expense or outcome supports the purchase. Enthusiasm from a user doesn't establish authority to buy.
- Evidence of value. Request records of appointment fills, staff time, and continued usage. Distinguish what the software did from what staff did manually. A promising pilot at the founder's former employer may not represent unrelated clinics.
- Adoption process. Map the steps between a demo and routine use: integration, security review, procurement, training, and workflow changes. Identify who owns each step and the costs the startup bears. A product that works in one system may require substantial work in another.
- Data and regulatory questions. Document the product's exact functions and data flows. The U.S. Food and Drug Administration's administrative software guidance distinguishes certain administrative functions, including appointment scheduling, from medical-device functions. That doesn't establish the status of every feature in a product.
- Independent review. Bring in a healthcare privacy lawyer and a security specialist for the questions outside your experience. The U.S. Department of Health and Human Services explains that a vendor's access to protected health information can create a business associate relationship. The relevant obligations depend on the actual service and data access.
Your operational insight can reveal a mismatch between the pitch and the purchasing process. Perhaps staff like the tool, but the budget owner sees little reason to pay. That finding changes the investment case even if the software performs as promised.
A good workflow fit still leaves founder execution, competition, capital needs, price, and investment terms unresolved. Sector knowledge improves the questions you can ask; it doesn't settle the whole decision.
Count shared risks, not just startup names
Sector concentration exposes several investments to developments that can affect them together. The Securities and Exchange Commission's (SEC) guidance on diversifying industry risk explains that investing across industries can dilute risk tied to trends or events in one industry. A change in customer spending, regulation, or access to financing can hurt multiple companies at once.
Different subsector labels can hide that overlap. A clinic-scheduling startup and a billing startup may sell to the same practices, depend on the same software integration, and need another funding round during the same difficult market.
Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge: “Don't try to pick a co. Select a portfolio.” Apply that perspective to how your investments fit together, including investments you already own.
Before adding a company, document these shared dependencies:
- Sector and customer. Which existing holdings depend on the same industry's spending, the same customer group, or one major partner?
- Stage and financing. How many companies need outside funding before they can support themselves? Different products can still share that financing risk.
- Geography and technology. Which companies depend on the same jurisdiction, infrastructure provider, platform, or technical assumption?
- Career and employer stock. Would the event that hurts these startups also threaten your income or employer equity?
There's no universal sector percentage that makes those dependencies acceptable. The decision depends on your finances, existing holdings, loss tolerance, and the uncertainty in each investment. Diversification can reduce some concentration risks; it cannot make private startup investing safe.
The SEC's private-placement risk bulletin notes that investors can lose their entire investment, may receive less disclosure than in registered offerings, and may have to hold securities indefinitely. Those risks remain for both specialist and generalist angels.
Keep your focus current and your decisions repeatable
Expertise can become stale. Continue learning from current buyers, users, technical documentation, relevant research, and independent specialists. Record where new evidence contradicts what your previous job taught you.
Avoid letting a familiar referral network become your entire view of the market. A customer who declined a pilot or a founder pursuing a different approach may explain a constraint your circle has overlooked. Category excitement also deserves separate scrutiny; our guide to investing in hype industries covers that decision more broadly.
Use the same review rubric, a consistent set of decision questions, for each deal. Record the customer problem, evidence of demand, founder capabilities, financing needs, price and terms, unresolved questions, and shared portfolio risks. Distinguish observed facts from your assumptions, and name what would change your decision.
As our general partner Elizabeth Yin writes in Democratizing Knowledge: “The more disciplined you are in your thought process/rubric, the more you can improve over time.” Keep the original notes so later learning doesn't turn into a rewritten story about what you supposedly knew.
Put boundaries around your next deal review
Write a short scope statement before reviewing the next opportunity. For example: “I understand administrative software for independent U.S. outpatient clinics. I need independent review for clinical claims, privacy, security, and investment terms. I will record customer, platform, financing, and career overlap before considering a check.”
Pair that statement with your repeatable review rubric. Your broader investment thesis can cover goals and other selection criteria; the scope statement defines where your sector knowledge applies.
To practice that process with investing education, curated deal reviews, and other angels, apply to Angel Squad.
Early-stage startup investments are speculative, illiquid, and long term. Many early-stage businesses may fail to return even your initial investment, and you may lose your entire investment. This material is educational and is not investment, legal, or tax advice. Review the governing documents and seek independent advice from qualified financial, legal, and tax professionals before investing.










