
Solution Looking for a Problem: An Investor's Guide
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A slick demo can make weak demand look like a temporary detail. For an early-stage investor, that detail may be the whole deal. The hard part is telling the difference between a startup chasing imaginary demand and a new technology whose best market is still emerging. That judgment starts with a precise definition, then moves to customer behavior, founder learning, and the cost of reaching a real market.
What does “solution looking for a problem” mean?
A solution looking for a problem is a product, technology, or feature built before its creator has evidence that a specific customer needs it badly enough to change behavior, spend money, or both.
The phrase is usually criticism. It says the team has fallen in love with what it can build and is now searching for a reason the market should care.
That does not mean every product must begin with a perfect problem statement. Early ideas are messy. New technical capabilities can reveal uses that nobody predicted. The real issue is whether the founder is running an honest search for demand or defending a predetermined answer.
A credible problem hypothesis should identify five things:
- A specific customer. “Finance leaders at U.S. construction firms with 50 to 200 employees” is useful. “Every business” is fog.
- A recurring job or trigger. What happens that makes the customer seek help now?
- A costly status quo. Show the spreadsheet, contractor, delay, error, lost sale, compliance headache, or other workaround.
- A buyer with a reason to act. The user and the person controlling the budget may be different people.
- A result worth switching for. The proposed improvement has to beat the current workaround after price, implementation, risk, and habit are included.
Without those pieces, a founder may have an invention. They do not yet have a business case.
Why a polished product can create false confidence
Technical progress is visible. Customer demand is harder to see. That imbalance creates several traps for founders and investors.
A good demo earns praise. People enjoy clever technology and still decline to pay for it. “That’s cool” is a reaction, not customer pull.
Interviews can manufacture agreement. A founder who explains the product and asks, “Would you use this?” has already led the witness. Y Combinator’s guidance on talking to users recommends asking about present behavior and current workarounds before introducing an idea. What people already do is stronger evidence than what they predict they might do.
Warm contacts are unusually generous. Friends, former coworkers, and friendly design partners may offer time because they like the founder. The signal gets stronger when strangers respond, share sensitive workflow details, introduce the real buyer, or make a commitment.
A trend can hide a missing use case. Adding artificial intelligence, blockchain, spatial computing, or another hot capability may help a deck get attention. The technology label does not tell you who has an urgent problem or how the company reaches them.
Building feels like progress. Another feature creates a satisfying artifact. Killing a weak use case feels like moving backward, even when it saves the company.
For an investor, these traps matter because a startup without a validated problem is carrying product risk, market risk, and distribution risk at the same time. More capital can extend the search. It cannot make customers care.
Starting with technology can work, under strict conditions
Some important products began with a technical discovery before anyone knew the best application. Post-it Notes are the classic example.
In 1968, 3M scientist Spencer Silver developed reusable adhesive microspheres while trying to create stronger adhesives. He spent years looking for a meaningful use. In 1974, colleague Art Fry connected the adhesive to a problem he had with bookmarks falling from his hymnal. A four-city release in 1977 received a lukewarm response. Direct-to-consumer marketing followed, and Post-it Notes launched nationally in 1980. The National Inventors Hall of Fame history shows both parts of the story: a technology-first discovery and a long path to a market.
That success does not give every startup permission to wander. 3M could support years of internal experimentation across a large company. A seed-stage startup has a shorter runway and a narrower margin for error.
A solution-first search is more investable when:
- The underlying technology is genuinely differentiated and hard to reproduce.
- The team can test several use cases without rebuilding the core product each time.
- Potential customers in those markets are reachable now.
- Each experiment is cheap, fast, and designed to produce a decision.
- The founders have named the evidence that will make them double down, change direction, or stop.
- The capital required to find the first wedge fits the financing available.
There is another important distinction. A broad technology is not automatically a solution without a problem.
Matterport is sometimes described as a company that built 3D-capture technology and searched for a use. Its co-founder’s own account of the origin is more specific. The team wanted to make real-world 3D capture easy because creating digital environments by hand was slow, specialized, and expensive. They expected many industries to use that capability, but they had a clear root problem from the start.
An investor should distinguish a fuzzy initial market from an absent customer problem. Those are different risks.
Use an evidence ladder instead of counting interviews
Ten conversations can be more useful than 100. The number matters less than what customers revealed and what they did next.
We sort problem evidence into four levels:
- Words. Prospects describe a frustration or praise the idea. Useful for discovery, weak for validation.
- Workarounds. Customers already spend time, money, or political capital patching the problem. Spreadsheets, consultants, manual reviews, and internal tools all count.
- Commitment. A buyer gives something scarce: money, data, implementation time, a signed pilot, an introduction to procurement, or access to users.
- Repeat behavior. Customers return, renew, expand usage, refer peers, or complain when the product is removed.
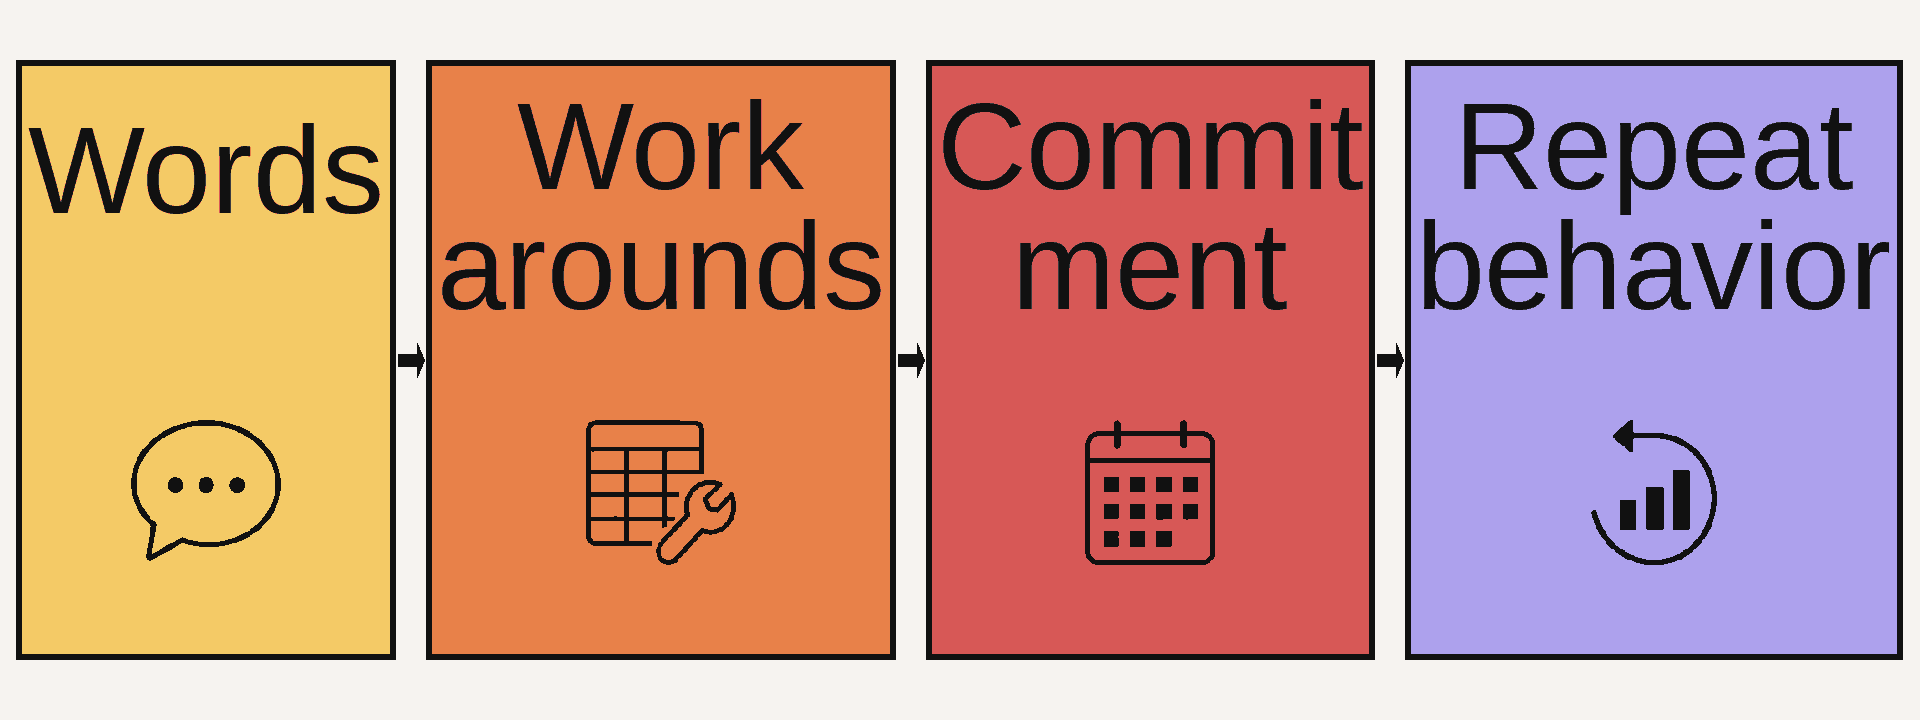
The ladder prevents enthusiasm from masquerading as traction. It also works before meaningful revenue exists. Our guide to evaluating pre-seed startups uses the same principle: trace an important claim through evidence, a test, and the result.
As our co-founder and GP Elizabeth Yin wrote in Democratizing Knowledge, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” A repeatable evidence ladder gives you that discipline without pretending every company should have the same metrics.
Questions that expose a solution in search of a problem
Ask for concrete episodes rather than the founder’s summary. The following questions make vague demand harder to hide.
Problem and customer
- Who feels the pain most often, and who approves the purchase?
- What happened the last time a customer encountered the problem?
- How do they handle it today?
- What does the current workaround cost in time, money, errors, delay, or risk?
- What event creates urgency?
Discovery quality
- How did you find interviewees outside your network?
- Which customer segment rejected the product, and why?
- What did customers show you that contradicted your original belief?
- Which use cases have you stopped pursuing?
- What product or market decision changed because of a customer conversation?
Commitment and pull
- What have prospects committed beyond compliments?
- Did a pilot reach the workflow, data, and buyer that matter?
- What happened after the pilot ended?
- Who came back without being chased?
- What evidence suggests customers will switch from the status quo?
Search economics
- How much runway does the team have to find a narrow entry market?
- Which experiments will run in the next 90 days?
- What result would kill the current use case?
- Can the company test a new market without a major rebuild?
- If the search works, how will the company reach more buyers?
Strong founders answer with names, sequences, artifacts, and decisions. Weak answers drift toward total addressable market, feature lists, and excitement about the technology.
A hypothetical diligence example
Imagine two startups selling the same artificial intelligence tool for insurance claims.
Founder A has interviewed 40 people. Most said claims work is inefficient and the demo looks impressive. The founder cannot identify the budget owner, explain the current review process, or name a use case the team rejected.
Founder B has interviewed 12 claims operations leaders. Eight showed the team the same manual review step. Three provided anonymized files for a test, two involved their security teams, and one agreed to a paid pilot with a defined success threshold. The founder dropped a second use case after learning that customers handled it cheaply with existing software.
Founder B has fewer interviews and much stronger evidence. The paid pilot helps, but the larger signal is the chain of behavior: repeated workflow, access to real data, internal effort from the buyer, a test with a decision rule, and proof that the founder can abandon a weak thesis.
That is what progress looks like before product-market fit.
Red, yellow, and green signals for investors
No single signal decides the investment. Look for a pattern.
Green signals
- The founder describes the customer’s workflow before describing features.
- Prospects reveal consistent workarounds across separate networks.
- Customers contribute money, data, time, distribution, or internal sponsorship.
- The team records failed tests and changes its decisions quickly.
- One narrow use case is becoming stronger while weaker ones are being removed.
- Burn remains low enough to finish the search.
Yellow signals
- Users are enthusiastic, but the economic buyer is unclear.
- Pilots exist, but they sit outside the customer’s normal workflow.
- A deep-tech or regulated product needs a long development cycle before customers can test it.
- The core technology has many possible markets, but the team has no ranking method.
- Demand depends on a future change in regulation, infrastructure, or customer behavior.
Yellow means the risk needs a price, a milestone, and a time limit. It does not mean “no” by default.
Red signals
- The target customer is “everyone.”
- All discovery came from friends, investors, or prospective partners with no buying authority.
- The strongest proof is survey intent, social engagement, awards, or demo applause.
- Customers have no current workaround and show little urgency.
- The founder treats every rejection as a messaging problem.
- Each new use case requires a different product.
- There is no kill criterion, experiment schedule, or runway plan.
The key is founder behavior. A solution-first origin story can improve. A founder who protects the solution from contrary evidence is much harder to underwrite.
Make the unresolved problem part of the investment thesis
At pre-seed, every deal contains unanswered questions. The phrase “solution looking for a problem” should identify a specific risk, not end the discussion.
Write the risk plainly in your memo:
- Current belief: The technical capability may solve a costly problem for a named segment.
- Existing evidence: Customers show a repeated workaround and early commitment.
- Missing proof: Repeat use, purchasing authority, or an efficient path to distribution.
- Near-term milestone: The result that would strengthen or break the thesis.
- Capital exposure: The amount of time and money required to reach that result.
Then decide whether the rest of the deal compensates for the uncertainty. The technology might be unusually defensible. The founders might learn exceptionally fast. The experiments might be cheap. The initial customer network might be accessible. If those offsets are weak, the startup is asking investors to finance an open-ended search.
Humility still matters. A tidy rubric becomes dangerous when it hardens into a rule that ignores changing markets. As Elizabeth Yin wrote in Democratizing Knowledge, “Going back to first principles is super important since the market always changes and evolves.” Diligence will not eliminate uncertainty. It can reveal whether a team is converting uncertainty into evidence.
A polished demo can hide weak demand
The skill is seeing what sits behind the demo: the customer’s old behavior, the founder’s tests, and the commitments earned so far. Members of Angel Squad practice that judgment by learning from Hustle Fund’s approach, reviewing curated deal flow, and comparing notes with other investors. Apply to sharpen your diligence on real early-stage opportunities.
This content is for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Startup investments are speculative, illiquid, long-term, and may result in total loss. Conduct independent diligence and consult qualified professional advisers before investing.











