
Ray Dalio investments: holdings and portfolio facts
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A portfolio tracker can make Ray Dalio’s investments look like an easy-to-copy stock list. The public record is messier. Understanding his personal activity, Bridgewater’s reported holdings, and the All Weather approach gives you a clearer picture of what the numbers mean and which risk lessons carry over to startup investing.
What is publicly known about Ray Dalio’s investments?
There is no complete, live public inventory of Ray Dalio’s personal investments. Public statements and individual investment announcements reveal pieces of his activity. Bridgewater’s regulatory filings describe a separate investment manager’s reportable holdings.
In a March 2026 essay, he says he develops his own All Weather approach for his family and foundation, while Bridgewater manages its versions for clients. He also describes taking tactical positions, bets that change with his market views, alongside that long-term allocation. He does not publish a complete holdings list in the essay.
One publicly announced private-company investment is SandboxAQ, which develops quantitative artificial intelligence (AI) technology. Its April 2025 funding announcement named Dalio as a new investor. That establishes participation in a disclosed round. It does not reveal his check size, current stake, or the rest of his private portfolio.
Bridgewater’s positions need their own label. The firm’s investment committee assumed investment oversight in 2020, and its board took control in 2022, according to its completed transition announcement. Later Bridgewater filings cannot establish that Dalio personally selected or owns the securities they list.
Bridgewater’s reported holdings for June 30, 2026
The latest available Bridgewater quarterly Form 13F in October 2026 covers June 30, 2026. It was filed on August 14. A Form 13F is an institutional investment manager’s report of specified securities over which it exercises investment discretion.
Bridgewater Associates, LP reported approximately $24.38 billion across 997 information-table entries on its Securities and Exchange Commission (SEC) cover sheet. That is the reported value of this particular disclosure, rather than Bridgewater’s total assets under management or Dalio’s personal wealth.
Large entries in the reported holdings list included the following. Values are rounded and refer to June 30, 2026:
- SPDR S&P 500 ETF Trust (SPY): $3.97 billion.
- iShares Core S&P 500 ETF (IVV): $2.25 billion.
- NVIDIA: $774 million.
- Broadcom: $498 million.
- Amazon: $483 million.
The first two are exchange-traded funds (ETFs), which hold baskets of securities and trade on an exchange. Both track the S&P 500, a broad index of large US companies. Two fund names therefore give exposure to much of the same underlying stock market.
The filing establishes reported positions at a quarter-end. It does not establish today’s holdings, the manager’s reasons for owning them, or a recommendation for your account.
What a 13F leaves out
A holdings list can look precise while answering only a narrow question. The SEC’s reporting guidance explains three limits that matter here:
- The information arrives late. Quarterly reports are generally due within 45 days after quarter-end. The September 30, 2026 report is due November 16, so an October portfolio page can still be showing June positions.
- The coverage is incomplete. Form 13F covers designated securities, including many US-listed stocks and ETFs. It excludes short positions and many other assets and exposures. Cash, private startup investments, and securities traded only on foreign exchanges are outside this picture.
- The filer is a manager. The report can aggregate positions across accounts the manager oversees. It does not identify those positions as the founder’s personal property.
A long stock position might sit alongside an offsetting position that the filing does not show. Without that context, its dollar value tells you little about the whole portfolio’s net risk. A tracker’s “Ray Dalio portfolio” label cannot supply the missing information.
How All Weather fits into the picture
All Weather is an approach to portfolio construction. It is distinct from a list of Bridgewater’s disclosed stocks and from a complete account of Dalio’s current assets.
Bridgewater says it originally launched All Weather in 1996 for Dalio’s trust assets. Its All Weather history explains the aim of balancing exposure to unexpected changes in economic growth and inflation, rather than depending on a forecast of the next environment.
Stocks, bonds, commodities, and other assets respond differently to those changes. The framework considers growth coming in higher or lower than expected, and inflation coming in higher or lower than expected.
Risk parity, the portfolio-construction idea associated with All Weather, sizes exposures by their contribution to risk. Equal dollar amounts can produce very unequal risks. A relatively volatile asset can dominate a portfolio even when other holdings take up plenty of space on the statement.
The State Street Bridgewater All Weather ETF, ticker ALLW, is a separate implementation. The ETF and private portfolios are intentionally different because their investors, tax considerations, and regulatory constraints differ. The ETF uses derivatives, contracts whose value depends on underlying assets, which add risks. Neither the ETF nor a simplified allocation circulated online establishes Dalio’s personal holdings.
Balancing exposures also cannot guarantee a profit or prevent losses in every market.
What startup investors can learn from this approach
We look for risks that could hurt several investments at once.
A startup portfolio cannot reproduce All Weather’s asset-class balancing. Early-stage companies share risks, may need more funding, and can be difficult or impossible to sell. The SEC’s private-placement bulletin warns about total-loss risk, illiquidity, and limited disclosure.
We plan for the possibility that most startup bets may fail. You can still build a more deliberate process around those constraints.
Look beneath the company count
Imagine three startups: hiring software, a payroll platform, and an AI sales tool. They solve different problems, but each sells mainly to venture-backed technology companies.
If those buyers cut spending, all three startups could lose customers. If investors also become reluctant to fund technology companies, the startups could face weaker sales and harder fundraising at the same time. Three company names can share one important source of risk.
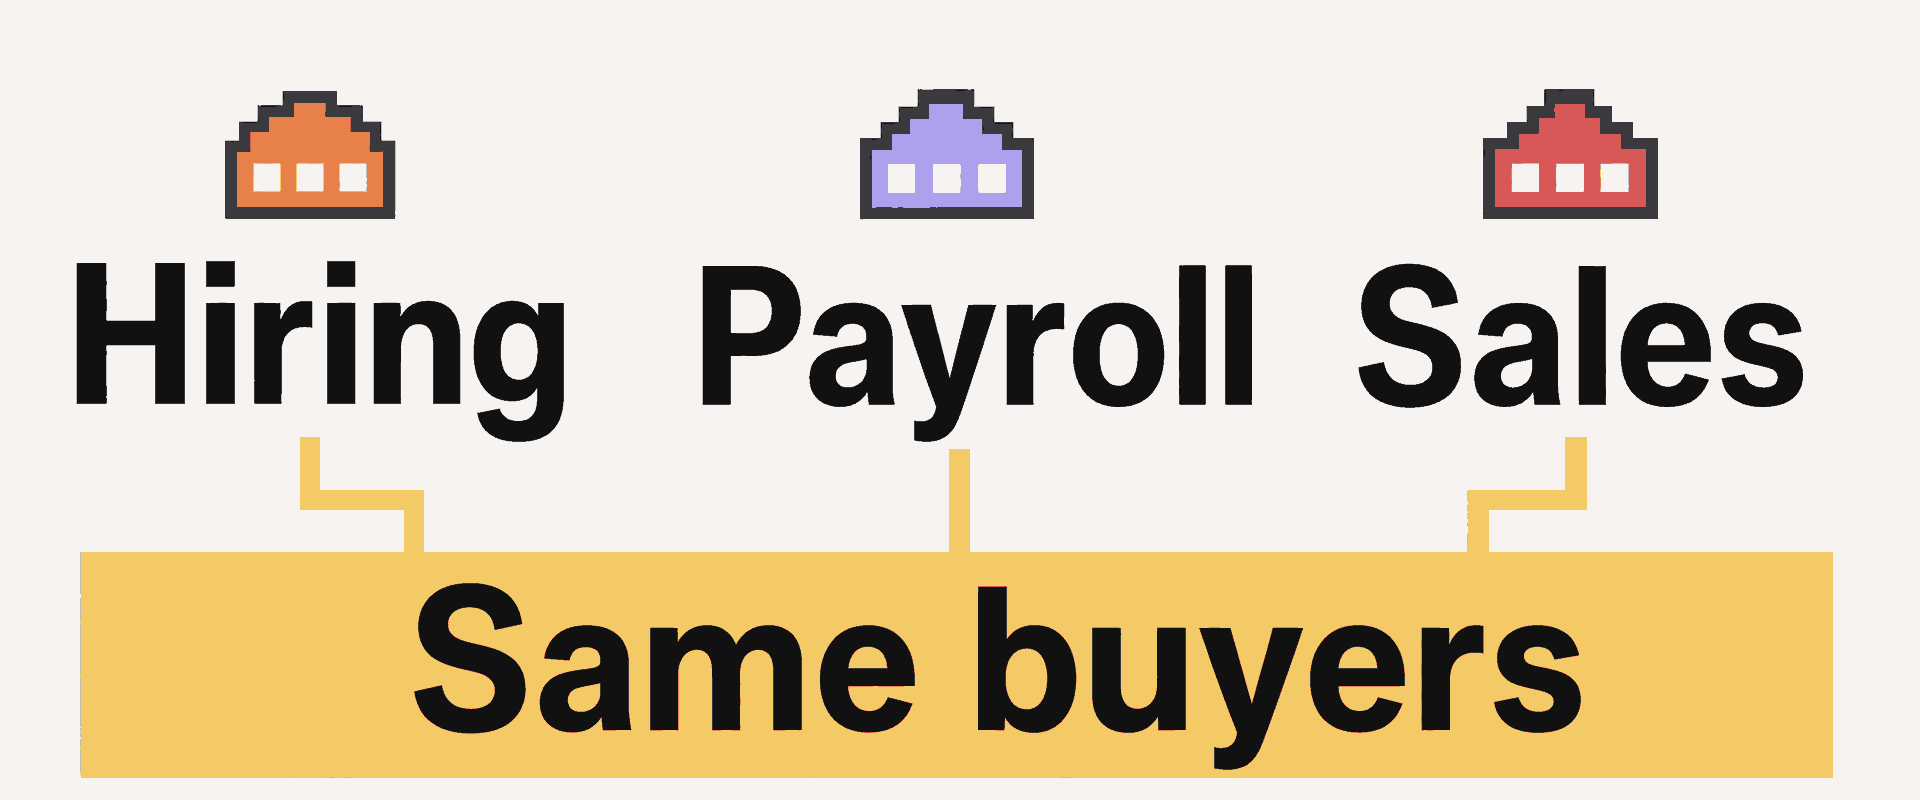
Record the dependencies behind each investment: customer budgets, distribution channels, geography, regulation, funding needs, and key suppliers. Then look across the portfolio for repeated dependencies. Sector expertise can help you evaluate a business while still leaving your investments concentrated in one market.
Our co-founder and general partner Elizabeth Yin puts the portfolio perspective plainly: “Don't try to pick a co. Select a portfolio.” Our case for spreading your bets starts with that uncertainty about individual outcomes.
Include the risks outside your angel portfolio
Your job, employer equity, and startup checks can depend on the same industry. An investor working at a venture-backed software company may already have substantial exposure to technology hiring, valuations, and financing conditions before writing an angel check.
Set a total amount you can afford to lose and leave illiquid for years. Keep near-term obligations and emergency savings outside that budget. Decide how much room remains for future investments and possible follow-on rounds before an exciting pitch changes your plan.
More startup positions can reduce dependence on one company. They cannot make the overall startup allocation liquid or safe.
Make your reasoning visible before the outcome
Our co-founder and general partner Eric Bahn says, “Investing requires practice like everything else.” Practice includes explaining a decision well enough to learn from it later.
For each opportunity, write down three things:
- The investment case: the customer problem, why this team could solve it, and the evidence behind that view.
- The failure case: the strongest contrary evidence and the event that could break the business.
- The portfolio fit: the capital at risk and the dependencies this investment would add or repeat.
A famous co-investor’s name does not fill in those answers. Neither does a manager’s quarterly filing. A dated record lets you revisit what you believed without rewriting the original reasoning around a good or bad result.
If you want to practice reviewing founder pitches and investment memos with other operators, apply to Angel Squad.
This is educational content, not investment, legal, or tax advice. Startup investments are speculative, illiquid, long term, and can result in a total loss. Seek independent guidance from qualified investment, legal, and tax professionals about your circumstances.











