
Niklas Zennström: Skype Co-Founder and Atomico Investor
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Niklas Zennström's career crosses two jobs that startup investors often study: building a category-defining company and backing the next generation of founders. He co-founded Skype, then founded the venture firm Atomico. His founder-to-investor path shows how operating experience shapes an investment lens and where that lens stops. You still need your own process, portfolio plan, and tolerance for loss.
From Skype to a European proof point
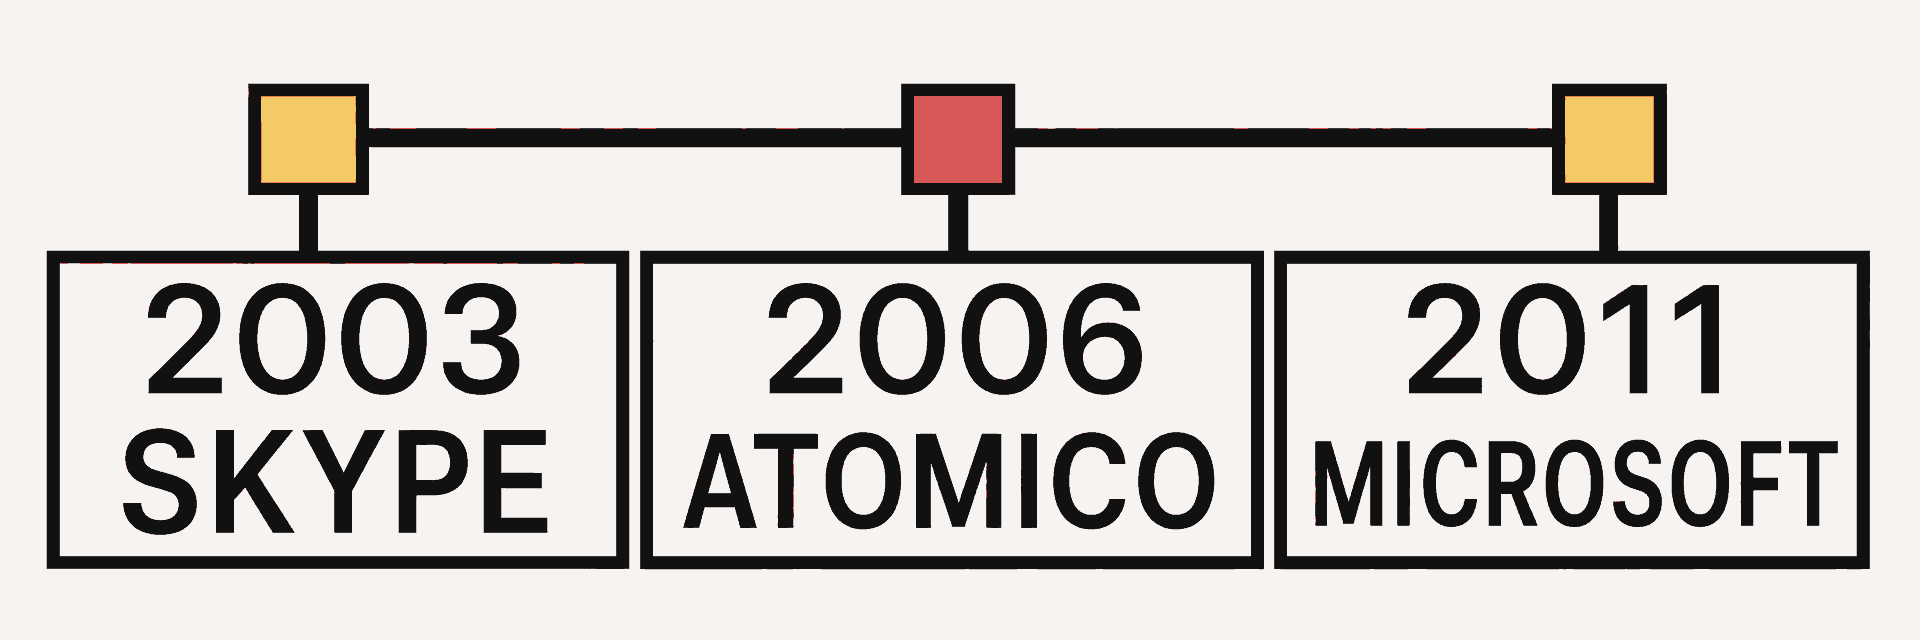
Zennström co-founded Skype in 2003. The internet communications company was based in Luxembourg and made voice and video calls available over an internet connection. That product turned an expensive, geography-bound activity into software with global reach.
Microsoft agreed to buy Skype for $8.5 billion in cash in 2011, according to its acquisition announcement.
That company-level price describes Skype, not Zennström's personal economics. It does not reveal his proceeds, ownership, or return, and it should not be used to invent those numbers.
For Zennström, Skype also became evidence that a global technology company could come from Europe. In a Stanford GSB interview, he argued that Skype and other European successes showed founders did not need to start in Silicon Valley. That was his stated thesis, grounded in his own experience. It was not a guarantee about every European startup.
Why Niklas Zennström founded Atomico
Zennström founded Atomico in 2006. He is now its CEO and founding partner, according to his current Atomico profile. Atomico is the venture firm. Its partnerships and portfolio companies should be described as Atomico's, unless a reliable source specifically identifies a personal investment by Zennström.
His founder history shaped the firm's premise. Zennström has explained that he wanted to build the kind of investor he wished he had when he was running companies. His operating experience gave him a point of view about founders building from outside Silicon Valley, working across borders, and using technology to address large problems.
That perspective is one lens. Our co-founder and general partner Elizabeth Yin writes, “Investors use their life perspective to assess. For this reason, we need more funders with more varied life perspectives.” (Elizabeth Yin, Democratizing Knowledge, Hustle Fund, 2021, p. 43). An investor's background changes the questions they ask, the risks they notice, and the founders they understand early. It does not make their judgment infallible.
What an angel can learn from the founder-to-investor transition
Zennström's path offers three practical lessons for your own investing process.
- Use operating experience as a lens. A founder who has hired across countries, sold to demanding customers, or managed a distributed team may spot risks that another investor misses. A finance leader, engineer, or product operator will bring a different set of useful questions. Start with the areas where you can evaluate substance, then identify the parts of the business where you need outside help. Our profile of CEO founders as angels explores this advantage in more detail.
- Write down the decision process. A compelling founder story can make an investment feel obvious. Memory then edits the reasons after the outcome is known. Before you invest, record the evidence, open questions, main risks, and reason the price and terms fit your plan. Revisit that memo as the company develops. As Elizabeth Yin writes, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” (Elizabeth Yin, Democratizing Knowledge, Hustle Fund, 2021, p. 131).
- Build a portfolio instead of copying a person. Zennström's experience may sharpen how you think about founder empathy, cross-border teams, and markets overlooked by a familiar network. It cannot tell you how much capital you can afford to lock up, which deals fit your goals, or how many losses you can absorb. Your portfolio plan has to match your own finances and constraints.
Early-stage investments are speculative, illiquid, and long-term. Many startups fail, and you can lose your entire investment. Diversification can spread exposure, but it cannot eliminate loss. Our guide to spreading your bets explains why portfolio construction and humility belong together.
Keep the case study in perspective
Skype's later acquisition price does not forecast the outcome of a startup you see today. A famous founder's involvement does not replace diligence either. Team conduct, customer evidence, market structure, financing needs, deal terms, and price all affect the decision.
The public Skype timeline also leaves out details you would need to calculate any individual's return. A company acquisition price alone does not show a person's ownership, dilution, taxes, fees, or timing of liquidity. That is why this case belongs in your library of investing lenses, not in a spreadsheet of assumed personal returns.
An investor's operating history can inform the questions you ask. Your decision still needs evidence you can defend. Luck and uncertainty remain part of early-stage investing, even when the people involved have built successful companies before.
Build your own lens before you borrow someone else's
If you want to practice writing investment rubrics and compare your thinking with other operators and angels, learn about Angel Squad. Our angel-investing community combines peer learning with curated deal review, so you can examine real opportunities without treating any investor's reputation as the answer.











