
Marissa Mayer Investments: A Source-Checked Guide
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Public profiles make Marissa Mayer’s investing history look tidy. It isn’t. They mix confirmed investments, financing announcements, board seats, and operating roles, then turn the result into a neat portfolio thesis. Angel investors need a stricter standard. The useful questions are which Marissa Mayer investments are publicly reported, what each source proves, and where analysis starts.
Start by separating Mayer’s three roles
Mayer’s operating career, board service, and personal investing can inform one another. They are still three different records.
Operating roles. Mayer joined Google in 1999 and later led products including Search, Maps, Gmail, and News. She served as Yahoo’s president and CEO from 2012 to 2017. Today she is the founder and CEO of Dazzle AI. Her previous startup, Sunshine AI, was acquired by Dazzle in 2025, according to her current Walmart biography.
Sunshine began as Lumi Labs before the company adopted the Sunshine name. Both names refer to Mayer’s operating company, not a fund or personal investment vehicle. A founder raising capital for her own company is different from an angel investing personal capital in someone else’s company.
Board service. Mayer currently sits on the boards of Walmart, AT&T, Hilton, and Starbucks. A board seat establishes a governance relationship. It does not, by itself, show that the director personally invested. We exclude those companies from the investment list unless a separate, reliable source names her as an investor.
Angel investments. Mayer has also invested personal capital in startups. Public reporting confirms examples across consumer products, financial technology, health, workplace software, gaming, and hardware. That record is the focus here.
This separation matters because a database may attach every organization in a person’s career to one profile. The resulting page can look comprehensive while answering the wrong question.
A representative set of publicly verified investments
No public source provides a definitive, current list of every Marissa Mayer investment. Investor databases disagree, early rounds can go unannounced, and investors may use entities that public coverage does not identify. The companies below are a representative set with named support in reporting or company financing announcements.
A source naming Mayer in a round establishes participation at that point in time. It does not disclose her check size, allocation, ownership percentage, current holding, or return. A round’s total size is the amount raised from all participating investors, not the size of Mayer’s personal check.
Early investments reported in 2012
The clearest early account comes from a 2012 Fortune interview. Fortune reported that Mayer had invested in “a dozen or so” startups and named One Kings Lane, Minted, Square, Uber, and uBeam. Mayer declined to say how much she had invested. In the same interview, she described committing to uBeam after a brief founder meeting.
Separate 2012 reporting identified Natera, Airtime, Getaround, and Brit + Co alongside several of the same companies. TechCrunch’s Brit + Co financing report names Mayer directly among the investors.
These records are useful because they name the investor. They still leave major gaps. They do not show whether she invested directly or through an entity, how the terms compared across deals, whether she later sold shares, or how any position performed.
A wider set of categories: 2014 to 2019
Later financing coverage expands the public record:
- Wealthfront. TechCrunch named Mayer among the investors joining the company’s 2014 financing.
- Lever. Mayer appeared among the investors in the recruiting software company’s 2014 round.
- Triplebyte. TechCrunch reported that Mayer joined the hiring platform’s 2018 Series A as a new investor.
- Cleo. NEA’s coverage of the family-support platform’s 2019 Series B named Mayer as a personal investor.
- Players’ Lounge. Axios named Mayer among the participants in the esports platform’s 2019 seed round.
That spread is evidence of category breadth. It is not enough to declare that Mayer follows a fixed sector allocation or formal portfolio strategy.
Recent verified examples: 2023 to 2025
In 2023, TechCrunch reported that HiNOTE had raised previously undisclosed capital from Mayer and other angels. Mayer also identified Uber, Square, Minted, and Figma as her other angel investments in comments for the HiNOTE report. That makes the story especially useful: it combines a named financing with direct confirmation from Mayer.
Two later company announcements add recent examples. Marketplace Arcade named Mayer as a new angel investor in its 2025 Series A. Connected gaming platform Scorbit said Mayer participated at pre-seed and converted into its 2025 seed round.
This sample spans more than a decade. It supports a modest conclusion: Mayer has made personal startup investments across several categories and stages. It does not support a precise portfolio count, typical check size, ownership estimate, or performance claim.
What Mayer has said about selecting investments
Mayer has publicly described parts of her decision process, and those comments deserve more weight than a thesis inferred from a logo list.
In the Fortune interview, Mayer said she wanted an idea to address a real user problem and be easy to explain. She also looked for technical competence and paid attention to her impression of the founder.
Her 2023 comments about HiNOTE rhyme with that earlier view. She described Uber, Square, Minted, and Figma as companies that tackled broad consumer problems with an ecosystem approach and made the experience simple.
Those comments show recurring product questions: Is the problem real? Is the concept legible? Can the team build it? Does the product make a broad task simpler? They do not establish a complete or permanent investment thesis. Two interviews, eleven years apart, cannot tell us her required stage, valuation range, ownership target, reserve policy, or current appetite.
Use an evidence ladder before drawing conclusions
An investor profile is a research problem. Start with the source closest to the event, then state only what that source can carry.
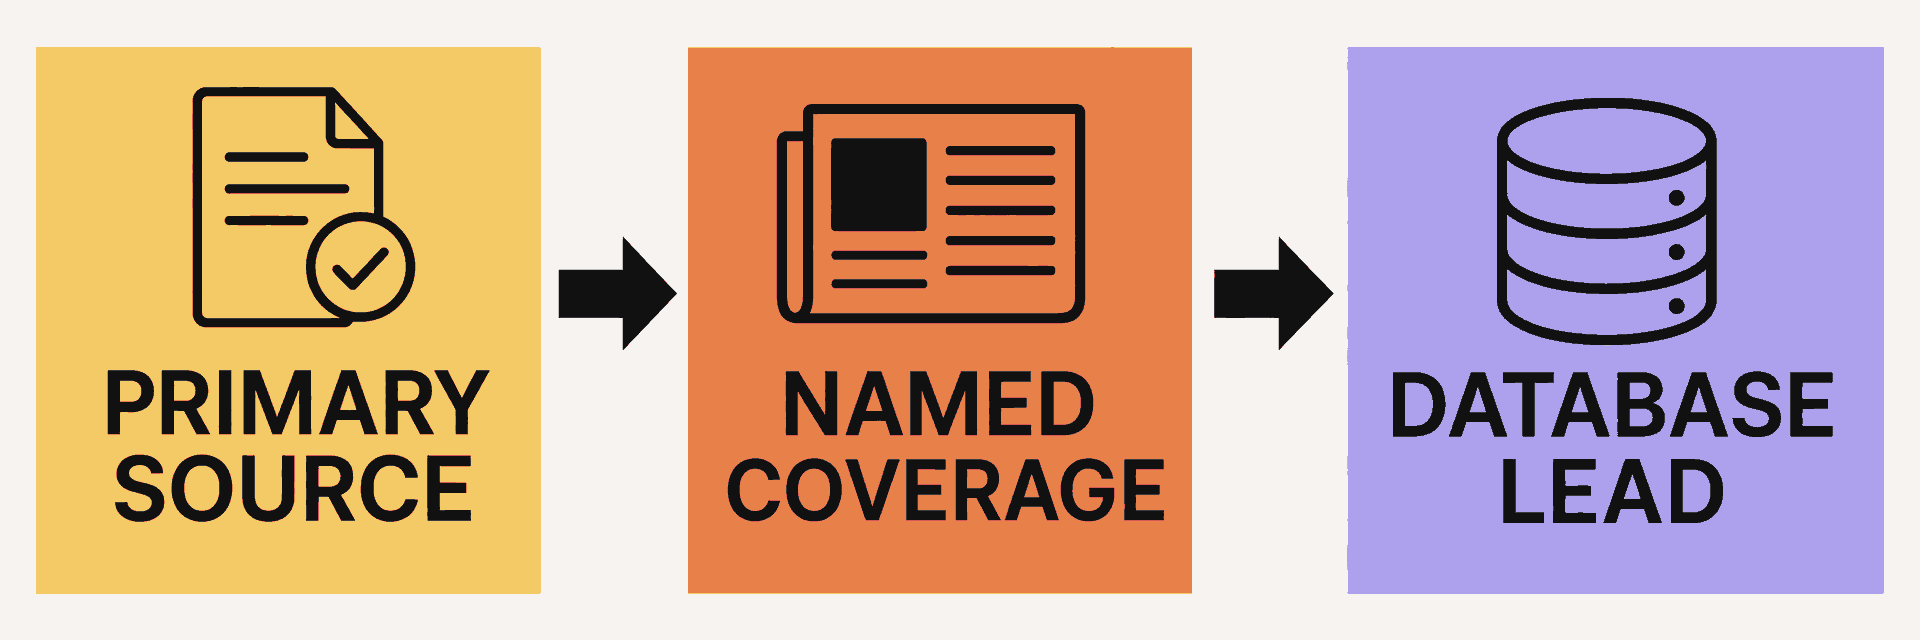
- Primary source. An investor, company, or regulatory filing directly names the participation. This is the strongest public evidence, though it can still omit terms and later changes.
- Named coverage. A reputable publication identifies the investor in a specific financing. This is useful corroboration when the underlying announcement is unavailable.
- Database lead. A profile or portfolio database points toward a company. Treat it as a lead for further research, not proof to repeat.
Keep the claim as narrow as the evidence. “Named as an investor in the Series A” is defensible when that is what the announcement says. “Owns part of the company today” requires later ownership evidence. “Made a great return” requires transaction and payout data that a financing announcement cannot provide.
Apply the same discipline when you assess your own opportunities. Our due diligence checklist separates confirmed facts, founder claims, assumptions, and open questions before social proof can take over.
Investor analysis: three lessons supported by the record
The points below are our analysis for angel investors. They are not Mayer’s stated investment policy.
1. Your operating experience changes what you can see
Mayer’s comments focus on user problems, product clarity, technical ability, and simple experiences. Those are areas where a product operator can ask sharper questions than a generalist seeing the company for the first time.
Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge, “Investors use their life perspective to assess. For this reason, we need more funders with more varied life perspectives.”
Your background can create a diligence edge, but only inside its limits. Write down which customer workflows, technologies, or distribution channels you understand firsthand. Then name the gaps where you need a domain expert, customer reference, lawyer, or another investor.
2. A famous co-investor is a prompt, not a conclusion
Mayer’s name in a round may justify asking what she saw. It cannot answer whether the valuation, security, governance rights, dilution risk, or exit path fits your portfolio.
Reconstruct the decision independently. Define the customer pain, test the evidence of demand, examine the team’s ability to execute, read the deal documents, and record the largest unanswered risk. If the case only works because a well-known investor joined, you do not yet have a case.
3. Earn your place after the check
Investor selection can become competitive when a company has more demand than room in its round. Capital alone rarely explains why a founder chooses one angel over another.
Elizabeth Yin puts the standard plainly: “At the end of the day, money is a commodity.”
Translate your operating experience into a short, credible offer. That might be a customer introduction, help recruiting a specific role, feedback on one product workflow, or context on a regulated market. Promise only what you can deliver, close the loop, and let the founder run the company.
The public record does not show which of these forms of support Mayer provided to each company. That boundary matters. A lesson for your own practice should not become an invented claim about someone else’s behavior.
Build your own evidence-first investing practice
Reading a famous operator’s portfolio can sharpen your questions. Improving your judgment takes repeated work on real opportunities, with people willing to challenge your assumptions.
Angel Squad is our community for aspiring and active angel investors who want to learn Hustle Fund’s approach, review curated deal flow, and compare notes with peers. Apply if you want a repeatable way to practice evidence-aware diligence before your next check.
Disclaimer: This content is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Startup investments are speculative, illiquid, and long term, and you may lose your entire investment. Past results, company outcomes, and current private-company valuations do not guarantee future results. Consider your financial situation and consult qualified independent advisers before investing.











