
John Zimmer Investments: What Investors Can Verify
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
John Zimmer co-founded Lyft, left the President role in June 2023, and resigned from its board in August 2025. For anyone researching John Zimmer as an angel investor, the primary records reviewed here directly disclose one recent angel participation: Jabbr.ai’s 2025 seed round.
Those records also establish his operating history and stated views on mobility and connection. Database-style inference cannot establish a broad portfolio or formal investment thesis.
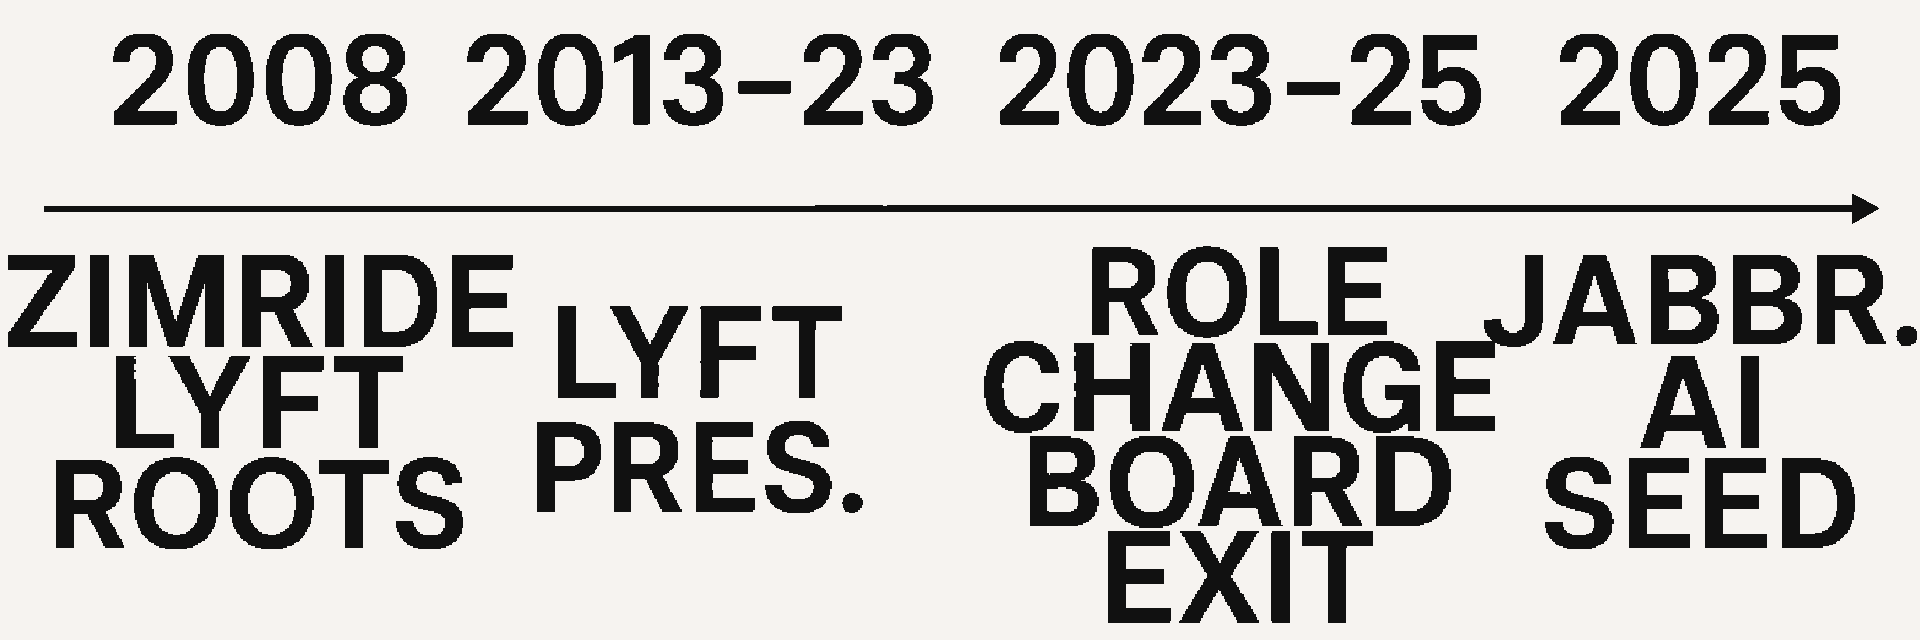
John Zimmer’s verified Lyft timeline
Zimmer’s history as a Lyft co-founder matters because it explains the experience he could bring to an investment decision. It does not prove that he made any particular investment or that a company will succeed.
The public timeline has four useful stages:
- Zimride and the Lyft roots. Lyft’s 2024 proxy says Zimmer served as chief operating officer from July 2008 to March 2013. In his 2023 letter, Zimmer recalled using Zimride to cross the country so he and Logan Green could work together. Lyft’s IPO prospectus says the company launched its on-demand ridesharing marketplace in 2012.
- A decade as President. The same 2024 proxy records Zimmer as Lyft President from March 2013 through June 2023. He had served on the board since June 2010 and became Vice Chair in January 2019.
- The operating transition. A March 2023 filing set June 30, 2023 as the end of Zimmer’s President role. It provided for one year as a non-employee adviser while he remained Vice Chair. That one-year arrangement is historical, so it is inaccurate to call him a current Lyft adviser.
- The board exit. Lyft’s August 2025 filing says Zimmer and Green resigned from the board effective August 14, 2025, completing a two-year transition plan. The filing says the resignations did not result from a disagreement with Lyft.
Precise dates prevent a common diligence error: turning an accomplished operator’s past title into a current credential. A stale title can distort your view of access, influence, and time commitment before you have evaluated the startup itself.
What Zimmer’s writing says about mobility and connection
Zimmer’s operating perspective is well documented. His 2023 letter describes Lyft’s origins as a business built around a real-world social movement. He also emphasizes the human connections created through rides and Lyft’s mission to bring people together.
Lyft’s 2019 prospectus adds the company view. It frames a shift from personal car ownership toward transportation delivered as a service and states a mission centered on improving lives through transportation.
Those sources establish a founder’s worldview and a company’s historical framing. They do not establish a current John Zimmer angel investor thesis. There is no sound basis for turning mobility, community, and connection into a three-part portfolio strategy without Zimmer saying that is how he invests.
Our co-founder Elizabeth Yin writes on page 43 of Democratizing Knowledge, “Investors use their life perspective to assess.” Zimmer’s operating history could help him notice details about marketplaces, trust, city operations, or transportation that another investor might miss. That perspective is a lens. It is still one input among many.
The same distinction applies to profiles of other experienced operators. Our Logan Green analysis starts from related Lyft experience, but each claimed role and investment still needs its own evidence.
The recent participation disclosed in the reviewed records
Among the primary records reviewed here, Jabbr.ai’s announcement is the one that directly names a recent Zimmer angel participation. Jabbr.ai announced on October 16, 2025 that it had secured a $5 million seed round led by Buckley Ventures. Its funding announcement names John Zimmer as a participant alongside Seven Seven Six, Andre Ward, and PSV Tech.
That announcement supports one narrow statement: Zimmer participated in Jabbr.ai’s seed round. Jabbr.ai develops artificial intelligence tools for combat-sports statistics, video production, and scoring, according to the same announcement.
The source does not disclose Zimmer’s check size, ownership, return, lead status, board seat, or advisory role. It also does not show that every database entry attached to his name is an investment by this John Zimmer. One confirmed participation cannot establish a sector pattern or predictable investment behavior.
This evidence boundary is useful. A good investment memo says exactly what a source proves and stops there.
What the public record does not verify
A database profile, search result, or secondary list can give you a lead. It is not confirmation. Namesakes, syndicate participants, advisers, directors, and founders can all be mislabeled as direct investors when the original announcement is missing.
The available primary record does not verify:
- an exhaustive Zimmer portfolio;
- a formal fund, recurring check-size range, or sector allocation;
- a standing three-theme investment thesis;
- advisory or board work connected to Jabbr.ai;
- ownership, valuation, performance, or returns; or
- a causal link between Zimmer’s Lyft experience and his Jabbr.ai decision.
The right label is “unverified,” rather than “false.” Evidence may surface later. Until it does, putting the claim in an investment memo gives it more certainty than it has earned.
Four diligence lessons for early-stage investors
Celebrity-founder investing profiles are tempting because the story feels coherent. Coherence is cheap. Your process should make unsupported claims difficult to smuggle into the decision.
1. Verify each investment at the source
Start with a company funding announcement, founder statement, regulated filing, or direct confirmation. Capture the date, financing round, exact wording, and what the source leaves out.
If the evidence says “participated,” write “participated.” Do not upgrade that to “led,” “backed early,” “advises,” or “owns” without separate support. This is one of the habits that matters when moving from founder to investor: reputation does not replace the work of documenting a decision.
2. Separate facts, hypotheses, and open questions
Use three labels in your memo:
- Verified fact: a dated source supports the statement directly.
- Investment hypothesis: your interpretation of why the opportunity may work.
- Open question: a missing fact that could change the decision.
For Zimmer, Lyft role dates are verified facts. The idea that his marketplace experience shaped the Jabbr.ai investment is a hypothesis. His check size is an open question.
3. Treat expertise as a lens, not proof
Operator experience can improve the questions an investor asks. A mobility operator may see marketplace liquidity, regulation, or local operations more clearly. A combat-sports specialist may judge Jabbr.ai’s workflow and customer pain more sharply.
Expertise can also create blind spots. Familiarity may make a market feel safer than it is, or lead an investor to overrate similarities to a past success. Our specialized investing playbook is most useful when domain knowledge generates sharper tests, not automatic conviction.
4. Use a rubric you can revisit
Our co-founder Elizabeth Yin writes on page 131 of Democratizing Knowledge, “The more disciplined you are in your thought process/rubric…” A practical rubric for an operator-linked deal can ask:
- What primary source proves the person invested?
- Which parts of the operator’s experience are relevant to this company?
- What customer, market, product, team, and financing evidence stands on its own?
- Which attractive claims remain hypotheses?
- What evidence would make us change our mind?
Save the answers with the decision date. Later company updates can then test the original reasoning instead of letting hindsight rewrite it.
No rubric removes startup risk. Early-stage investments are speculative, illiquid, and long-term. Many startups fail, and you can lose your entire investment even when the evidence was carefully checked. Portfolio construction can spread exposure, but it cannot guarantee a return.
Build your own evidence habit
If you want guided practice reviewing real startup opportunities with other aspiring and active investors, apply to Angel Squad.
Educational disclaimer: This material is for educational purposes only and is not investment advice. Startup investments can result in the loss of your entire investment.











