
IPO market for angel investors: From listing to liquidity
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Initial public offering (IPO) headlines make it sound as if a company rings a bell and early investors get paid. A listing can create a path to liquidity, but your security, offering terms, resale restrictions, market price, and investment vehicle determine whether cash reaches you.
Here’s how to read the market and trace a portfolio company from private shares to spendable cash.
The 2026 IPO market looks stronger than angel liquidity
U.S. IPO activity has increased. The U.S. Securities and Exchange Commission (SEC) recorded 208 IPOs raising more than $137 billion in the first half of 2026, up from 180 IPOs and more than $27 billion in the first half of 2025. Those figures cover the U.S. market, including U.S. and non-U.S. issuers, operating companies, special purpose acquisition companies (SPACs), and funds. They do not represent 208 startup exits. The SEC’s IPO statistics are useful only when you keep that denominator in view.
The venture-backed slice is much smaller. The 2026 National Venture Capital Association (NVCA) Yearbook counted 49 U.S. venture-backed IPOs in 2025, compared with 1,396 venture-backed acquisitions. Its data also put the median time from first venture financing to IPO at 7.85 years. An angel may have invested before that first institutional round, so the full holding period can be longer. The NVCA data show why a busy IPO calendar and broad early-investor liquidity are different things.
Our co-founder and general partner Elizabeth Yin names a frustrating portfolio category in Democratizing Knowledge: “the ones that continue to do well but never have liquidity.” A strong company can keep raising private capital, stay independent, and leave early shareholders holding valuable but unsellable securities for years.
An IPO is the start of a liquidity process
An initial public offering is a company’s first registered sale of shares to public investors. Most large IPOs primarily issue new shares so the company can raise capital. An angel gets cash at the offering only if some of the angel’s shares are registered and included as selling-shareholder shares. The final prospectus identifies those sellers and the shares they plan to sell.
If your shares are not included, you still own them after listing. You may have to wait through a contractual lockup, satisfy securities-law resale requirements, and find enough market demand at a price you accept. If you invested through a special purpose vehicle (SPV) or fund, its manager controls the sale and distribution process under the vehicle’s documents.
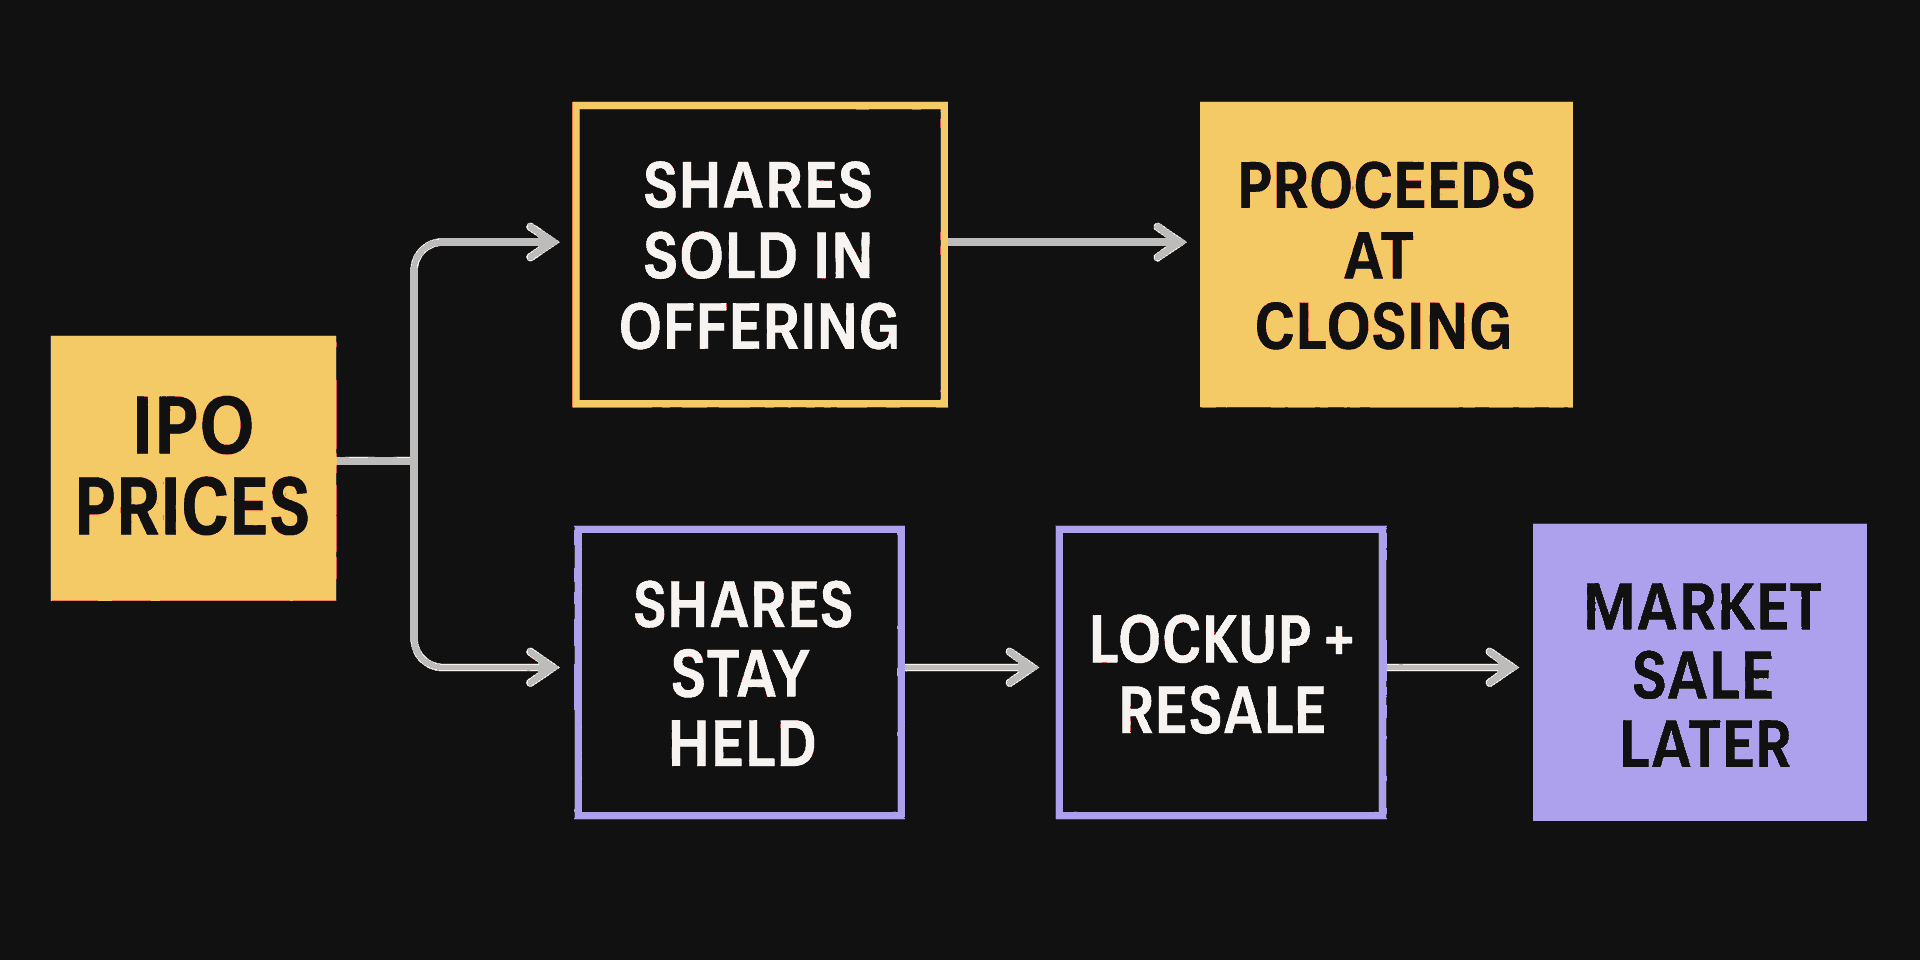
The path has four separate gates:
- The company completes the offering. A filed registration statement is a step toward an IPO. It is not a completed listing, and preliminary terms can change.
- Your security becomes the right kind of share. A Simple Agreement for Future Equity (SAFE), preferred share, common share, or interest in an SPV can follow a different conversion and distribution path.
- The shares become sellable. Selling-shareholder registration, contractual lockups, restricted-security rules, and affiliate status can all affect the date and amount you can sell.
- A sale and distribution happen. The trading price, available volume, manager decisions, fees, carried interest, taxes, and timing can separate a paper value from the cash you receive.
That distinction is visible in historical private-capital data. MSCI studied 2,617 venture and growth investments that were fully exited after an IPO and found a median full exit around 2.5 to three years after listing. The sample was predominantly U.S. positions and excluded investments that had not fully exited, so it is not an angel benchmark or forecast. It is strong evidence that listing day is a poor proxy for cash timing. The MSCI exit study also found wide variation between fast and slow exits.
Check what you own before estimating an IPO outcome
Start with the document that created your economic interest. A cap-table line alone may not tell you enough.
Direct shares
If you hold preferred shares directly, the IPO may trigger a conversion to common shares under the charter. Read the actual conversion terms. Confirm the number and class of shares you would hold after conversion, along with any stock split, recapitalization, or other change disclosed in the latest filing.
A SAFE or convertible note
A SAFE or convertible note usually has to convert before it becomes publicly tradable equity. The conversion terms, later financing rounds, and company charter determine what you receive. A headline IPO valuation does not answer that question.
An SPV or fund interest
An interest in an SPV or fund is one layer removed from the company’s shares. The vehicle may sell shares over time, distribute shares in kind, or distribute cash after expenses and carried interest. Your governing documents control those choices. The company’s IPO lockup and the vehicle’s distribution policy are separate constraints.
Do not confuse the three prices around an IPO
An angel will often see at least three prices attached to the same company:
- The last private-round price reflects negotiated terms for a specific share class and date. Preferences or other rights can make it a poor stand-in for common-stock value.
- The IPO offer price is the price paid for shares sold in the offering. Underwriters and the company set it using investor demand, market conditions, and negotiation.
- The public trading price moves after listing. It can be above or below the offer price by the time your shares become sellable.
The gap is more than a technical detail. NVCA found that 67% of the venture-backed unicorns that went public in 2025 priced below their last private valuation. That does not tell you what any one angel realized. It does show why the latest private mark should not anchor your cash expectation.
The SEC’s IPO bulletin points investors to prospectus sections including selling shareholders, dilution, underwriting, and shares eligible for future sale. Those sections are far more useful than a celebratory valuation headline.
Lockup expiration still does not guarantee a sale
An IPO lockup is a contract that prevents certain existing shareholders from selling for a defined period. About 180 days is common, but it is not a universal legal rule. The issuer’s prospectus and underwriting documents state the actual term, exceptions, waivers, and any staggered release.
Restricted securities create a separate issue. The SEC explains that previously issued restricted shares need an effective resale registration statement or a valid exemption, such as Rule 144, before public resale. Rule 144 conditions vary with facts including the holding period, the issuer’s reporting status, and whether the holder is an affiliate. The SEC’s current guidance is the right starting point for counsel reviewing a specific holding.
Even after the contractual and legal gates open, you still face market risk. A share price can fall before you sell. Low trading volume can limit how much you can sell without affecting the price. An SPV manager may choose a paced sale rather than a single transaction.
Use an IPO filing as a diligence trigger
When a portfolio company files publicly, replace the headline with a document review. Ask these questions:
- What security or vehicle do I own? Pull the SAFE, note, stock purchase agreement, SPV agreement, or fund documents.
- What will it convert into? Confirm the post-conversion share class and quantity against the latest cap table and filing.
- Am I a selling shareholder? Check the preliminary and final prospectus rather than assuming existing holders can sell in the offering.
- What lockup applies to me? Read the duration, exceptions, waiver rights, and release schedule.
- What resale rule applies after the lockup? Contractual release and legal sellability are different questions.
- Who decides when to sell? For an SPV or fund, identify the manager’s authority and distribution policy.
- What reduces the distribution? Review fees, carried interest, taxes, administrative reserves, and transfer costs.
- What remains exposed to the market? Treat any unsold shares as a volatile public position, not cash.
This review also helps you compare an IPO with acquisition, tender-offer, and private-secondary paths. Our broader angel exit strategy guide covers those alternatives without treating an IPO as the default destination.
What IPO conditions should change in your underwriting
A stronger IPO market can improve the odds that a mature portfolio company has another financing and exit option. It can also give private investors fresher public-company valuation benchmarks. Neither effect makes a seed-stage IPO likely or near.
For a new angel investment, use public-market conditions as context for three questions:
- Can this company keep creating value without an open IPO window? A business that depends on a public listing at a specific date has little room for market cycles.
- Are you comfortable holding through multiple financing rounds? Dilution, new preferences, and changing capital needs can reshape the outcome before an IPO is possible.
- Does the portfolio work if this company never lists? Acquisition, secondary liquidity, or no exit at all are credible outcomes.
Yin’s compact advice in Democratizing Knowledge is still the right frame: “Don't try to pick a co. Select a portfolio.” Most startup bets may fail or remain illiquid, so one promising IPO candidate cannot carry your entire strategy.
Build for the wait, not the bell-ringing photo
Good exit judgment develops through repeated deal review, cap-table questions, and honest portfolio conversations. If you want to practice that work with other investors and learn from Hustle Fund’s early-stage approach, apply to Angel Squad.
This material is for informational purposes only and is not investment, legal, tax, accounting, or valuation advice. Startup investing is speculative, illiquid, long-term, and can result in total loss. Outcomes depend on governing documents, share class, cap table, fees, carried interest, taxes, valuation policy, market conditions, and timing. Past results and current marks do not guarantee future results. Review the issuer and investment-vehicle documents and seek independent advice from qualified legal, tax, accounting, valuation, and investment professionals.











