
Angel Networks: How to Vet One Before Writing a Check
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
This is educational information, not legal, tax, or investment advice. Private startup investments are speculative, illiquid, long-term, and can result in total loss. Read the governing documents and seek independent advice from qualified legal, tax, and financial professionals.
An angel network can give you deal flow, sharper judgment, and people who understand the weirdness of early-stage investing. The label alone promises none of those things. Before you pay to join or invest through one, inspect how the network sources deals, makes decisions, charges fees, handles conflicts, and supports members after the pitch.
What is an angel network?
An angel network is an organized group or platform where individual investors share startup deal flow, evaluate companies, and sometimes invest together. Members usually invest their own capital. The network may coordinate screening, diligence, education, events, paperwork, or a special purpose vehicle (SPV), which is a legal entity formed to hold one investment.
Angel networks do not always pool money. In a traditional group, each member may decide and invest independently. In a syndicate, a lead may invite backers into an SPV. On a marketplace, investors may discover and complete deals with little peer interaction.
That distinction matters. The Angel Capital Association describes member-led groups where angels review companies together, conduct diligence, and decide whether to invest. Its directory also includes accredited platforms, which shows how wide the category has become.
Membership and investment eligibility are separate. A community can admit people for education and networking while limiting particular offerings to eligible investors. In the United States, eligibility depends on the offering and its securities exemption. The SEC’s accredited investor criteria include financial and certain professional qualification routes.
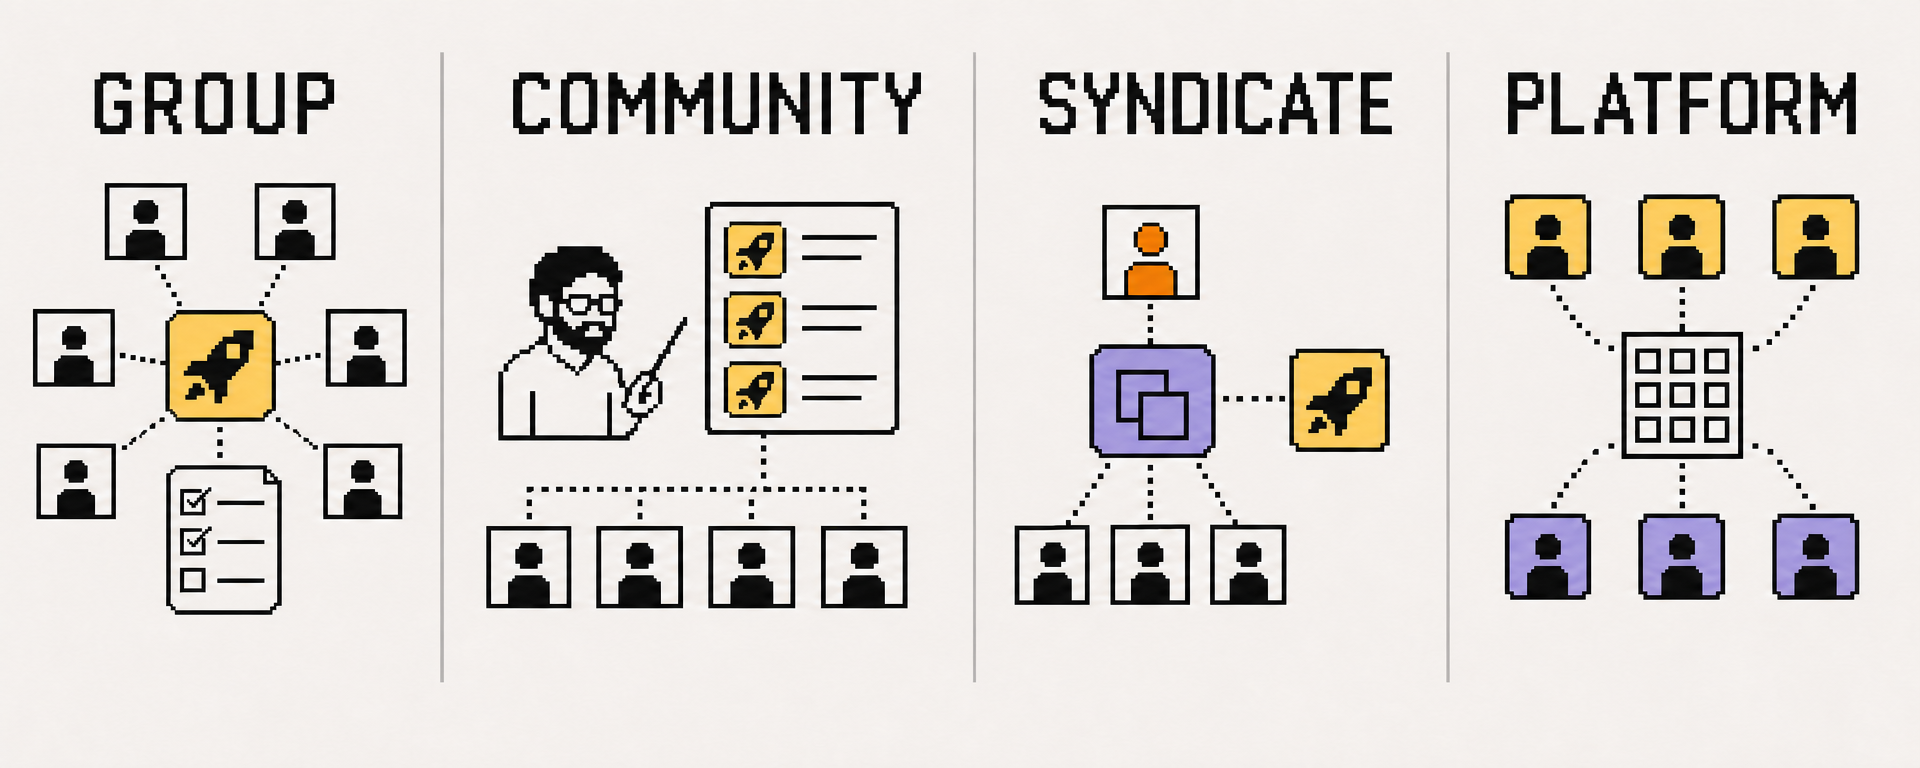
Four models sit behind the “angel network” label
Start with the operating model because it determines who sources deals, who does the work, and what you are buying.
- Traditional angel group. Members often source companies, form diligence teams, hear pitches, and invest separately or together. This model fits experienced local operators who want an active role and can contribute time.
- Managed investor community. A professional team curates opportunities, teaches investing, and runs the member experience. Our Angel Squad community follows this model: Hustle Fund supplies curated deal flow and investing education, while eligible members choose whether to join individual opportunities. This model fits busy operators who want guided learning and optional co-investing.
- Lead-led syndicate. A lead selects a specific company and gathers backers, usually through an SPV. The relationship centers on the lead’s judgment and one deal at a time. It fits investors who want a more delegated process but still need to assess the lead, economics, and underlying company.
- Marketplace or crowdfunding platform. Technology connects companies, investors, and transaction infrastructure at scale. Screening and community depth vary. This model fits self-directed investors who want breadth and are prepared to do more of their own filtering.
Some organizations combine these models. Ignore the name on the homepage and follow the work: Who found the company? Who formed the investment vehicle? Who wrote the memo? Who can decline? Who communicates after the deal closes?
Make two decisions, not one
An angel network puts two products in front of you:
- The membership product: deal access, education, peer learning, events, administration, and relationships.
- The investment product: a particular security in a particular company, with its own price, terms, risks, fees, and conflicts.
A useful community can present a deal that does not fit your thesis. A well-structured deal can appear inside a community that offers little ongoing value. Joining the network should never pre-approve its investments, and passing on one deal does not settle whether the membership is worthwhile.
This separation also prevents borrowed conviction. A polished memo and a respected lead can help you reason, but neither replaces your decision. Our co-founder and general partner Elizabeth Yin puts the habit plainly: “The more disciplined you are in your thought process/rubric, the more you can improve over time.”
How to vet an angel network
Run the network itself through diligence before you evaluate any startup it presents. Eight checks expose most of the difference between a real investing practice and an expensive mailing list.
1. Trace deal flow back to its source
“Curated deal flow” is a claim. The sourcing process is the evidence.
Ask for a source breakdown: founder referrals, portfolio referrals, accelerators, members, the managing team’s network, inbound applications, or public listings. Then ask what happens between intake and presentation. A credible answer names the filters, decision-makers, and reasons a company advances.
Raw volume and a tiny acceptance rate can sound impressive while telling you little about fit. A network can reject hundreds of irrelevant applications and still surface weak deals. Inspect a sample memo and see whether the company matches the network’s stated stage, sector, geography, and check-size focus.
Also ask whether the network has a relationship with the company, the round’s lead investor, or an earlier investor. Warm access can improve context. It can also create conflicts that deserve disclosure.
2. Inspect the diligence process, including its limits
Good diligence does not turn an uncertain startup into a safe asset. It clarifies what is known, what is assumed, and what could break.
Ask who validates founder backgrounds, customer claims, market assumptions, financial data, cap-table information, intellectual property, and financing terms. Find out whether members can review source materials, submit questions, hear founder answers, and read the final diligence summary.
The memo should separate founder claims from independently supported facts. It should also state what the team did not review. “No issues found” is weaker than “we reviewed these five areas, found these two open questions, and did not commission legal or technical diligence.”
Use our startup diligence checklist on each company even when the network supplies a memo. The network’s work is an input to yours.
3. Follow the investment from commitment to ownership
Map the transaction before wiring money. You should be able to name:
- The company issuing the underlying security.
- The instrument the company issued, such as equity, a note, or a Simple Agreement for Future Equity (SAFE).
- Whether you invest directly or receive an interest in an SPV.
- The entity managing the SPV and the platform handling subscriptions, wires, and tax documents.
- Who signs, votes, receives company updates, and decides on amendments or follow-on actions.
- What happens if the allocation shrinks, the round does not close, or the network stops operating.
Private offerings provide less standardized disclosure than registered public offerings. The SEC’s private placement bulletin warns that these investments may involve total loss, indefinite holding periods, and limited information. A familiar network does not remove those conditions.
4. Calculate the full cost of membership and investing
There is no single “angel network cost.” Possible charges include membership dues, setup or administration fees, platform expenses, legal costs, management fees, carried interest, wire or currency costs, and expenses charged to an SPV.
Request the written fee schedule and trace charges across three outcomes: you join but invest in nothing, an investment returns no capital, and an investment produces proceeds. Identify who receives each payment and whether the amount is fixed, percentage-based, recurring, or deducted from investment proceeds.
Compare all-in cost using the number and size of deals you realistically expect to join. Our guide to angel network fees goes deeper on the math and questions behind that comparison.
5. Map incentives and conflicts
Write down how every party gets paid: the network operator, investment lead, platform, SPV manager, service providers, and anyone sourcing the company. Then ask:
- Does the company pay to pitch or appear?
- Does the lead invest personal or fund capital in the same round?
- Does a parent fund receive priority allocation, fees, or other rights?
- Does the network receive referral, placement, consulting, or marketing compensation?
- Are related parties providing legal, administrative, or fundraising services?
- How are scarce allocations divided among the lead, fund, and members?
A conflict can be manageable when it is specific and disclosed. A vague answer such as “we are all aligned” gives you nothing to assess. The SEC also recommends understanding compensation and business ties when an investment professional presents a private placement.
6. Test whether the community changes decisions
Community value is behavior, not a member count. Speak with current members and, where possible, someone who left. Ask what changed in their sourcing, diligence, portfolio process, or founder support after joining.
Attend a real deal review rather than a polished welcome event. Do members challenge the lead? Are dissenting views welcomed? Do people with relevant operating experience contribute? Does the discussion produce sharper questions, or does it mainly create momentum toward a check?
Different judgment is part of the value. As Elizabeth Yin, our co-founder and general partner, writes, “Investors use their life perspective to assess. For this reason, we need more funders with more varied life perspectives.” A room full of impressive resumes still has a blind spot when everyone sees the company the same way.
7. Read the track record with clean definitions
Ask for the complete relevant record, not a highlight reel. The useful version identifies the deals sourced through the network, investment dates, realized exits, active holdings, write-offs, and the basis for any current valuations.
Keep these categories separate:
- Realized proceeds are cash or stock distributed after an exit or liquidity event.
- Unrealized value is an estimate for an investment that the vehicle still holds.
- Company milestones such as a new round or higher headline valuation are context, not member cash returns.
- A parent fund’s portfolio is not automatically the network members’ portfolio.
Ask whether reported performance is gross or net of fees and carried interest, whether follow-on capital is included, and which date the figures use. If the operator will not explain the definitions, the number is marketing copy.
8. Confirm identity, controls, and communication
The network should identify its legal entity, principals, service providers, and a real contact for operational problems. Read the membership agreement, privacy terms, investment documents, wire instructions, and conflict disclosures before payment.
Where a person is acting as a broker or investment adviser, the SEC points investors to FINRA BrokerCheck and the Investment Adviser Public Disclosure database for registration and disciplinary history. Many angel-group members are investing their own money rather than acting as investment professionals, so registration status is one fact about a specific role, not a universal seal for the whole network.
Confirm wire instructions through a known channel, especially after any last-minute change. A network that treats operational controls as boring is doing this correctly. Boring is good when your money is moving.
A 20-point scorecard for comparing angel networks
Score each item from zero to two. Give zero for no evidence, one for a partial or vague answer, and two for specific written evidence.
- Deal sources are named and fit the stated thesis.
- Screening criteria and decision-makers are clear.
- Diligence shows sources, open questions, and limits.
- Members retain independent opt-in authority for each deal.
- The full membership and investment fee stack is written down.
- Conflicts and compensation are disclosed by party.
- The legal entity, investment vehicle, and service providers are identifiable.
- Current and former members describe concrete value.
- Track-record figures use consistent, understandable definitions.
- Post-investment reporting and operational contacts are clear.
Do not let a high total erase a zero on a personal non-negotiable. If independent decision-making matters to you, for example, strong events cannot compensate for pressure to invest. Use the score to compare networks serving the same job, then write down why your preferred option won.
Red flags that should stop the process
Pause when you encounter any of these:
- Promises of high returns, safety, or guaranteed access to “winners.”
- Urgency that blocks reasonable review of documents or questions.
- Secrecy about the network entity, people, fees, or source of deals.
- Missing or sloppy written offering materials.
- A claim that a Form D filing means the SEC approved the investment. It does not.
- Performance claims built only from selected winners or unrealized headline valuations.
- Wire instructions sent from a new address or changed without independent confirmation.
- Testimonials offered in place of current-member conversations.
- An operator who treats reasonable questions as disloyalty.
The SEC’s unregistered-offering alert specifically flags guaranteed returns, aggressive sales tactics, missing written materials, suspicious biographies, and unverifiable business operations. A warm introduction or shared professional circle does not cancel those signals.
Questions people ask about angel networks
Are angel networks legitimate?
Many are legitimate investing groups, communities, syndicates, and platforms. The phrase itself does not identify a registration status or one legal structure. Legitimacy comes from identifiable people and entities, clear economics, written documents, appropriate securities processes, and behavior that survives independent scrutiny.
Do you need to be an accredited investor to join an angel network?
It depends on the network. Education and community membership may be open more broadly, while participation in a specific private offering may require accredited status or another eligibility route. The offering documents should state the applicable exemption and investor requirements.
How do angel networks make money?
Models vary. Revenue can come from membership dues, transaction or administration fees, carried interest, management fees, issuer-paid services, sponsorships, or related service providers. The important question is who pays whom at each stage and how that payment might influence which deals reach members.
What is the difference between an angel network and a syndicate?
An angel network is an ongoing organization for sourcing, learning, diligence, or investing. A syndicate is usually organized around a lead and a specific deal, often through an SPV. A network may use a new syndicate or SPV for every investment, so one organization can be both.
Choose the network that improves your process
The right network should make your thinking more explicit, expose you to informed disagreement, and let you say no without friction. Deal flow matters. The process that turns access into independent judgment matters more.
If you want to learn with operators, study how Hustle Fund evaluates startups, and choose from curated co-investing opportunities, apply to Angel Squad.











