
Angel Investment Terms: Negotiate Without Burning Bridges
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
You’re ready to back a founder. Then the investment documents arrive, and you’re unsure which terms to accept or question. A clumsy counteroffer can sour a relationship you hope will last for years. A thoughtful conversation can clarify the economics, protect your boundaries, and give both sides a clear decision.
1. Start with your role in the round
If you’re joining a round led by another investor, you may have little room to change its overall terms. If you’re leading the financing, you have a different job: agreeing on a structure that works for the company and the investors. Establish which role you’re playing before proposing changes.
A small check still deserves understandable documents. You can ask how your investment works without demanding a board seat or rewriting the round.
Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge (Hustle Fund, 2021, PDF page 121), “At the end of the day, money is a commodity.” Her broader point is that investors can also offer expertise, connections, and support. Be specific about the help you can deliver.
A useful customer introduction gives a founder a reason to want you involved; it doesn’t entitle you to a special price.
Ask who set the terms, whether the round is still being negotiated, and which documents you’ll sign. That gives you a realistic starting point for the conversation.
2. Read the angel investment terms that change your deal
A term sheet summarizes a proposed financing. The signed investment documents spell out your rights and obligations. For some small investments, you may receive the contract directly, without a separate term sheet.
Start with the instrument, meaning the legal structure of your investment. Three structures call for different questions:
- Simple Agreement for Future Equity (SAFE). You invest now under a contract for future equity. The standard U.S. SAFE from Y Combinator (YC) has no interest or maturity date. Identify the cap, discount, or most favored nation provision, then understand the conversion, sale, and shutdown provisions. YC offers separate SAFE forms with different economics; a SAFE doesn’t automatically contain all three features.
- Convertible note. This is debt intended to convert into equity under specified conditions. Along with the conversion price, understand the interest, the financing that triggers conversion, and what happens at maturity if it hasn’t converted. Repayment, conversion, and extension provisions vary, as Cooley’s debt primer explains. A repayment obligation offers little comfort if the company has no cash.
- Priced equity. You buy shares at an agreed price now. Understand the share class, valuation, employee option pool, and investor-rights package. Preferred shares can have payment priority over common shares. The National Venture Capital Association’s model financing documents cover the connected financing agreements. Our term-sheet guide explains the broader package for a priced round.
Across these structures, focus on four questions:
- What determines your ownership? Include other SAFEs and notes, existing shares, and the option pool, which reserves equity for employees. A cap table is the record of the company’s ownership and securities.
- What happens if the company sells or shuts down? Payment priority and the funds available can change what you receive. A liquidation preference describes a preferred shareholder’s priority payment. Under negotiated preferred-share provisions, participation can add a share of remaining proceeds. Non-participating preferred generally receives its preference or what it would receive after converting to common shares, rather than both, subject to the documents.
- Which rights will you receive? Information rights govern access to company reports. Pro rata rights govern opportunities to invest more. Eligibility thresholds can mean you don’t receive every right available to a larger investor.
- Who can change the deal or approve company decisions? Amendment rules and investor consent rights can affect you even when your check is small. Your individual approval may not be required for every amendment.
Our angel investing glossary explains the vocabulary. Your negotiation should focus on what the provisions do in this investment.
3. Turn the headline cap into a concrete scenario
A valuation cap limits the price used to calculate conversion under a SAFE’s terms. It isn’t an agreed current equity valuation or a guaranteed exit value. On a post-money cap SAFE, the cap includes the SAFE financing money, before the new priced-round money.
Consider a hypothetical, simplified direct investment of $25,000 on an unmodified YC post-money cap-only SAFE at a $5 million cap. If the cap determines conversion, $25,000 divided by $5 million gives an estimated 0.5% ownership before dilution from the new priced-round money and its option-pool increase. At a $10 million cap, the corresponding estimate is 0.25%.
That comparison gives you a reason to discuss price. It doesn’t promise permanent ownership. A lower-priced financing can produce a different conversion result, and the capitalization definitions matter. YC’s SAFE user guide explains those limits.
A discount changes the conversion price differently. In another hypothetical, simplified direct investment, a 20% discount applied to a $2 priced-round share price produces a $1.60 conversion price. A $25,000 investment would buy 15,625 shares at that price, compared with 12,500 at $2. This isolates the discount arithmetic and assumes no other adjustment.
If your document includes both a cap and discount, its conversion clause determines how they interact. Don’t assume the discount stacks on top of the cap.
Then connect the terms to the business. What milestones will this funding buy? How much additional capital might the company need? How much dilution could later financings create? Customer traction, financing needs, and plausible outcomes give you more to discuss than “that cap feels high.”
4. Separate clarification from a counteroffer
Before the founder call, sort your concerns into three groups. This keeps a missing explanation from becoming an unnecessary fight over price.
- Clarify an uncertainty. The capitalization definition is unclear, the reporting rights aren’t documented, or you haven’t received the final agreement. Ask for the missing explanation or document. You aren’t asking for better economics yet.
- Negotiate a mismatch. You understand the deal, but a specific change would make it fit your investment plan. A lower cap or a defined follow-on right might qualify. State the change and its reason together.
- Pass on an unresolved deal-breaker. You can’t accept a required future funding obligation, the company won’t explain material document changes, or the economics remain outside your boundaries. A polite pass is a valid outcome.
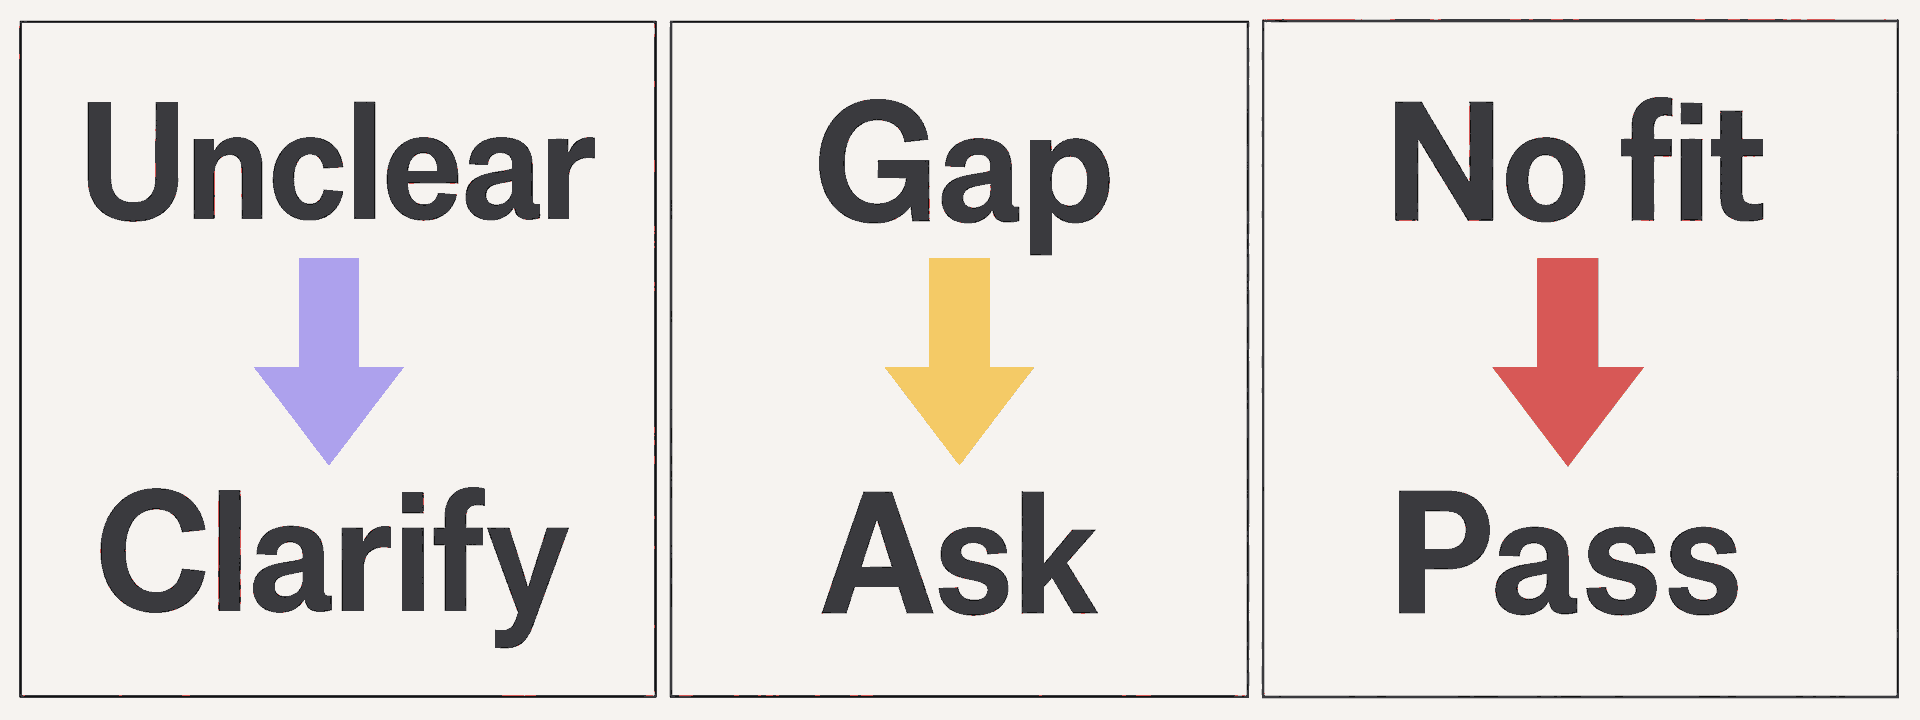
For example, “Can you explain which securities are included in the conversion calculation?” is a clarification. “Would you accept my $25,000 investment at a $5 million cap?” is a counteroffer. “I can’t invest under an obligation to fund future rounds” states a boundary.
Pressure to wire before you understand the documents is a reason to pause. The Securities and Exchange Commission flags high-pressure pitches and the possibility of total loss. A reasonable question deserves an answer; the founder can still decline your proposed change.
5. Make one proportionate, evidence-backed ask
Bundle your material questions into one short conversation. Once you understand the answers, make a clear counterproposal if one change would resolve the mismatch. Avoid a series of small concessions followed by another surprise demand.
For a cap discussion, you could say: “I’m interested in investing $25,000. Given the current customer traction and the additional funding I expect the business to need, I’m comfortable at a $5 million post-money cap. Is there room for that? If the round is fixed at $8 million, I’ll pass.”
The numbers are illustrative. The useful parts are your check size, the evidence behind your limit, the exact request, and a clear response if the founder says no. There’s no need to declare that their valuation is wrong.
Ask for pro rata rights when you have a follow-on plan
Pro rata is an opportunity to invest additional money to maintain a specified ownership percentage, subject to the agreement. It’s a right, rather than an automatic requirement to invest.
In a hypothetical, simplified priced-round example, assume you own 0.5% immediately before the financing and can buy 0.5% of a fixed $4 million total round, including your participation. Your follow-on check would be $20,000. This assumes no other dilutive changes and a right defined on that basis. Reserving only $5,000 wouldn’t fund the full allocation.
Ask for the right when follow-ons fit your budget and strategy. If you intend to invest only once, you may prefer to keep the negotiation focused elsewhere.
For a YC post-money cap SAFE, pro rata rights sit in an optional side letter, a separate agreement accompanying the SAFE. The standard letter covers the equity financing in which the SAFE converts; it isn’t a promise of access to every later round. Pro rata allocations also take space alongside new investors, so the founder has a legitimate reason to consider the request carefully.
A proportionate ask is: “I’ve reserved capital for follow-ons. Would you include the standard pro rata side letter for the conversion round?” If you receive the right, respond promptly when the company asks whether you’ll participate.
Match reporting and control requests to their purpose
If you need information to monitor the investment or meet reporting obligations, explain what you need and why. Ask whether you can receive the same update package as comparable investors before requesting a custom reporting process.
Information rights aren’t a board seat. A board role brings governance responsibilities; a personal veto can add friction to company decisions. We prefer a small angel’s requests to solve an identifiable problem without creating unnecessary work for the founder.
There’s no universal check-size threshold that makes a side letter appropriate. The requested right, its administrative burden, your role, and the rest of the round all matter.
Understand what a most favored nation provision covers
A most favored nation (MFN) provision can let an investor adopt terms from specified later-issued securities. Its scope comes from the contract, rather than a general promise that you’ll always get everyone’s best deal.
Under YC’s uncapped MFN SAFE, qualifying later convertible securities can trigger a notice and election process to amend your SAFE. You generally adopt the later instrument’s package instead of choosing individual favorable clauses. Certain securities and side letters are excluded. If the SAFE reaches an equity financing without an MFN amendment, it converts at the new investors’ price.
Ask which later securities qualify, how notice and election work, and what’s excluded. An MFN doesn’t replace understanding the investment you’re making today.
6. Agree on conditions before you commit
Negotiate while you’re still evaluating the investment and completing diligence, your review of the company and its risks. A founder should know whether you’re expressing interest, making an indication subject to specific conditions, or committing to agreed terms.
In Democratizing Knowledge (Hustle Fund, 2021, PDF page 173), Elizabeth Yin writes, “Because your word in business needs to mean something.” She was advising a founder against changing a promised cap after investor demand increased. We apply the same principle to investors: avoid using a founder’s reliance on your check to extract a late concession.
If your decision is conditional, make the conditions explicit before the founder counts on the money. For example: “I’m interested in $25,000 at the stated cap, subject to completing diligence and agreeing on the final documents. I’ll give you a decision by Friday.”
A clear message still needs to be consistent with your legal obligations. Binding obligations depend on the communications, signed provisions, facts, and applicable law. A term sheet can include binding clauses even when the investment proposal itself is non-binding.
Material new diligence findings deserve a prompt conversation. Explain what changed and involve your independent counsel if obligations or signed documents are affected. A newly discovered problem is different from asking for a lower price because you think the founder is running out of time.
Before funding, reconcile the final documents with the agreed check amount, economics, conditions, and side letters. Keep the fully signed package. An email promise of “we’ll take care of you next round” leaves too much unclear.
7. Pass clearly and preserve the relationship
A founder can decline your counteroffer without being unreasonable. You can decline their terms without being unsupportive. When you’ve reached that point, give a clear answer rather than stretching the process out.
You could say: “Thanks for explaining the round. The economics don’t fit my investment plan, so I’m passing. I appreciate the time you’ve spent with me and would be glad to stay connected.”
If you’d reconsider only at a different cap, say so without implying that the founder owes you another chance. If you’ve already made a binding commitment, address your obligations with counsel rather than treating a polite message as a release.
After investing, deliver the help you promised. After passing, keep company information confidential and avoid criticizing the founder for choosing different terms. Your behavior gives founders evidence of what working with you will be like.
To build this judgment alongside experienced investors, apply to Angel Squad. Our community pairs investing education with curated deal flow and peer learning, so you can discuss the reasoning behind a deal as well as its headline terms.
This is U.S.-focused education, not legal, tax, investment, accounting, or valuation advice. Seek independent review from qualified legal, tax, and financial professionals. Startup investments are speculative, illiquid, long-term, and can result in total loss; most individual bets may fail. All calculations are hypothetical and simplified, not projections. Actual outcomes depend on governing documents, capitalization, debt and preferences, financing and exit timing, valuation assumptions and policies, fees, any manager’s share of profits, and taxes. Past results and current valuations don’t guarantee future results.











