
Non-Accredited Investment Opportunities in Startups
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Accredited status blocks access to many U.S. private startup deals. Several legal pathways still provide startup exposure. The exemption, security, disclosures, and resale terms determine your access and what you would own.
Our scope here is U.S. startup investing, plus public-market choices that provide adjacent exposure without making you a direct angel investor.
Four U.S. routes can provide startup exposure
A non-accredited investor has four relevant routes. The first three can provide shares, debt, a SAFE, or an interest in an investment vehicle, depending on the offering. The fourth provides indirect exposure through securities that trade in public markets.
- Regulation Crowdfunding: You can buy securities in a compliant Regulation Crowdfunding, or Reg CF, offering through a registered online intermediary. A 12-month aggregate investment limit applies.
- Regulation A: You can buy securities in a qualified Regulation A offering. Your personal limit depends on the offering tier and whether the security will be listed on a national exchange.
- A qualifying private placement: A Rule 506(b) issuer may accept a limited number of sophisticated non-accredited purchasers. The issuer controls access, and the offering cannot use general solicitation or advertising. A club, syndicate, or special purpose vehicle (SPV) does not create eligibility by itself.
- Public-market exposure: Listed stocks, exchange-traded funds (ETFs), and other publicly traded vehicles can provide exposure to high-growth companies or investors in private businesses. You do not own the underlying startup directly.
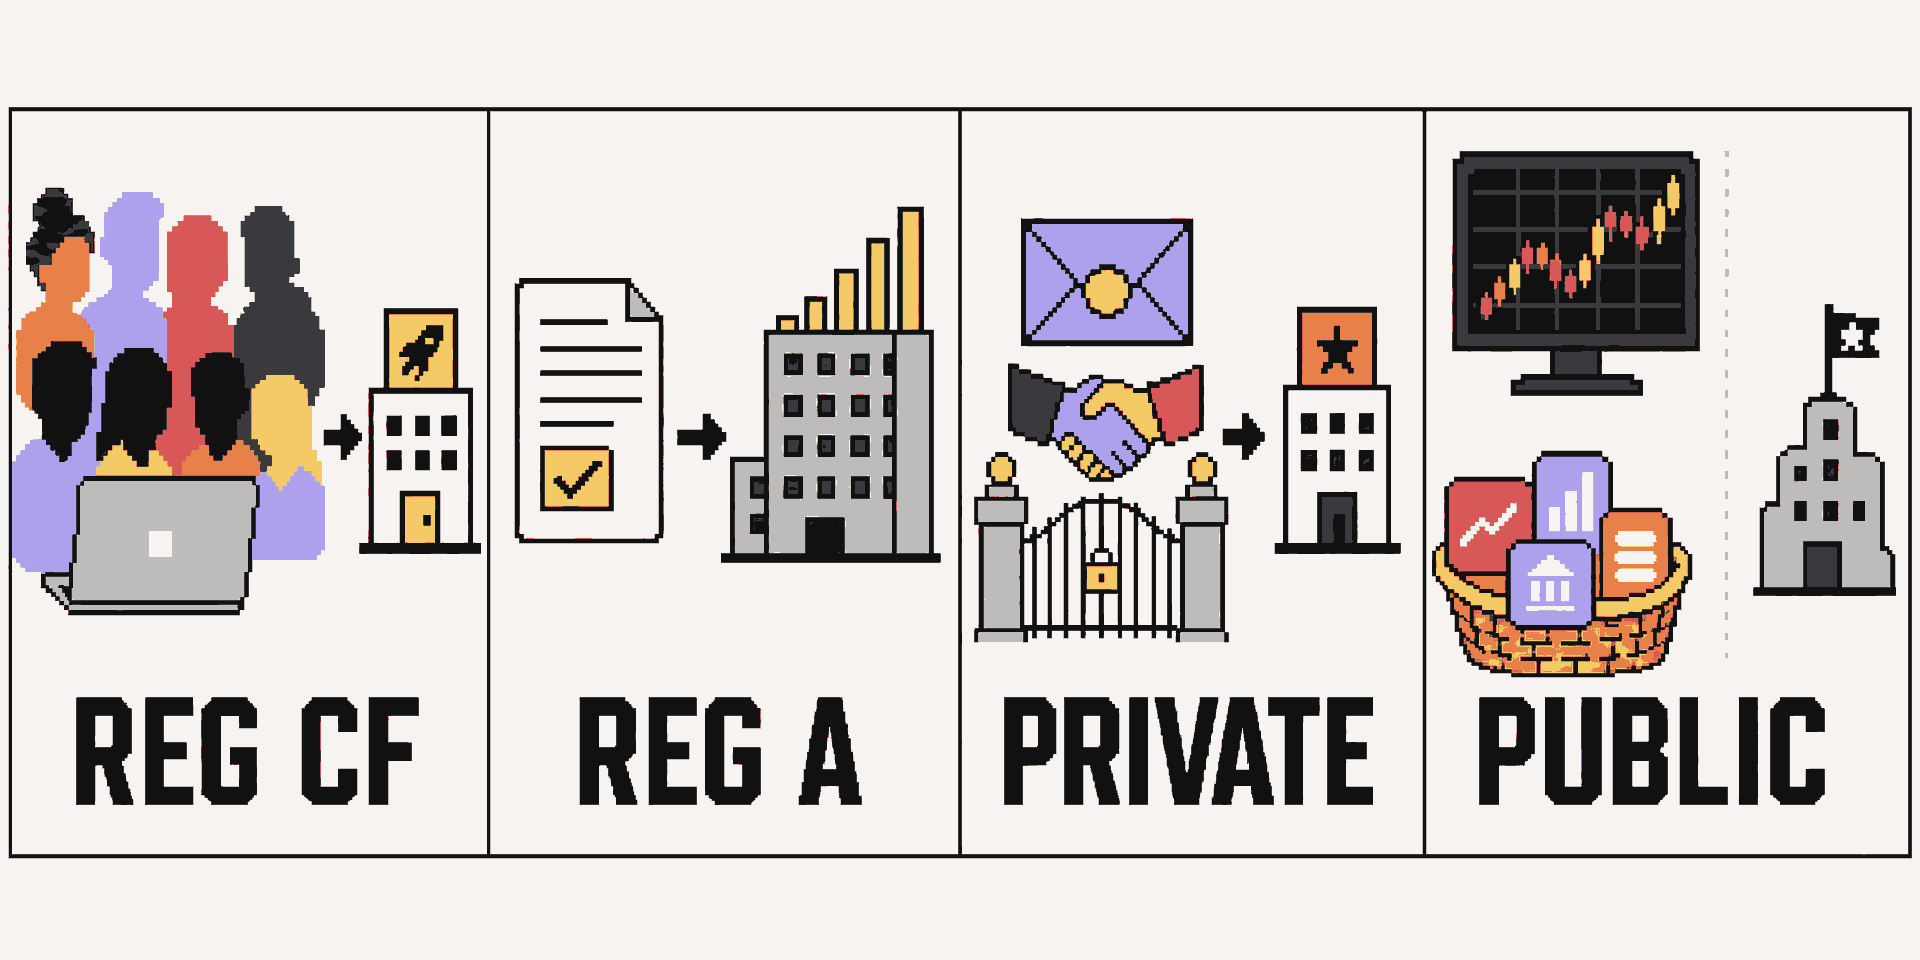
Each route solves a different access problem. None turns startup investing into a liquid or low-risk asset class.
Regulation Crowdfunding provides direct public access
Reg CF is a legal route built for online public participation in startup and small-business offerings. The issuer conducts the offering through one online platform operated by a broker-dealer or funding portal registered with the U.S. Securities and Exchange Commission (SEC) and also a member of the Financial Industry Regulatory Authority (FINRA). The issuer files Form C with business, offering, ownership, use-of-proceeds, risk, and financial information.
Under the current SEC framework, an issuer may raise up to $5 million through Reg CF in a 12-month period. That is the company’s fundraising limit. It is separate from your personal investment limit.
The Reg CF investor-limit formula
Your limit covers all Reg CF investments in any 12-month period, rather than each company or calendar year.
- If either your annual income or net worth is below $124,000, your limit is the greater of $2,500 or 5% of the greater of your annual income or net worth.
- If both your annual income and net worth are at least $124,000, your limit is 10% of the greater amount, subject to an overall cap of $124,000.
For this formula, qualifying net worth generally excludes your primary residence. Debt secured by that residence and joint or spousal calculations follow additional SEC calculation rules.
Suppose your annual income is $80,000 and your qualifying net worth is $50,000. The relevant amount is $80,000, and 5% is $4,000. Your aggregate Reg CF limit for the 12-month period is therefore $4,000, because that exceeds the $2,500 floor.
The $2,500 figure is part of the cap formula. It is not a required minimum check. An offering can set its own minimum.
What you may own
A Reg CF offering can sell common or preferred stock, debt, a Simple Agreement for Future Equity (SAFE), or another security. A SAFE is a contract that may convert into equity after a defined event. It is not necessarily stock when you buy it, and conversion may never occur.
Reg CF securities generally face a one-year federal resale restriction, subject to specified exceptions. The end of that period does not create a market or a buyer. Treat the holding as illiquid unless the documents show a credible route to liquidity.
A platform may host Reg CF and Regulation A deals side by side. The platform name does not determine your eligibility or the legal protections. Read the exemption and security for every offering.
Our equity crowdfunding platform comparison explains the platform-level differences that sit on top of these rules.
Regulation A provides another direct route
Regulation A, sometimes called Reg A+, is a public offering exemption. The issuer files Form 1-A, and the SEC must qualify the offering statement before sales begin. Qualification means the filing process has cleared a regulatory step.
The SEC does not endorse the company or the investment.
The two tiers have different issuer caps and investor rules:
- Tier 1: The issuer may raise up to $20 million in 12 months. Regulation A does not impose a federal individual investment cap, although the issuer’s terms and state law can still limit participation.
- Tier 2: The issuer may raise up to $75 million in 12 months. If the securities will not be listed on a national securities exchange upon qualification, a non-accredited individual may invest no more than 10% of the greater of annual income or net worth. That investor limit does not apply when the securities will be exchange-listed upon qualification.
For the Tier 2 formula, qualifying net worth generally excludes your primary residence. Debt secured by that residence and joint or spousal calculations can affect the result.
Tier 2 requires audited financial statements and continuing SEC reports. Tier 1 reporting is more limited, and its financial statements do not always require an audit. The SEC’s Regulation A guidance explains the filing, disclosure, and limit differences.
Regulation A securities do not generally carry Reg CF’s one-year federal resale restriction. An unlisted security can still be difficult or impossible to sell. Offering minimums, fees, voting rights, redemption programs, and transfer restrictions vary by deal.
Private-placement access is real and conditional
Many startup rounds rely on Regulation D. Rule 506(c) permits broad advertising, but every purchaser must be accredited and the issuer must take reasonable steps to verify that status.
Rule 506(b) works differently. The issuer cannot use general solicitation, but it may sell to up to 35 non-accredited purchasers in a 90-calendar-day period. Those purchasers must have enough financial and business knowledge to evaluate the investment, either alone or with a purchaser representative.
They must also receive specified disclosures and an opportunity to ask questions.
This is an issuer-controlled exception, not a marketplace you can freely browse. Joining an investment club or syndicate does not make an otherwise restricted deal available. An SPV must still rely on a valid exemption, and its investors must satisfy the relevant conditions.
The SEC’s private-placement bulletin covers the 506(b) and 506(c) distinction.
Rule 504 and intrastate offerings can create other narrow routes, with state law and offering-specific conditions. Their existence is another reason to identify the exemption before assuming that every private deal is accredited-only or open to everyone.
What accredited status means
A non-accredited investor is someone who does not meet any applicable accredited-investor category. The SEC accreditation categories include these common individual routes:
- income over $200,000 individually, or $300,000 with a spouse or spousal equivalent, in each of the prior two years, with a reasonable expectation of reaching the same level in the current year;
- net worth over $1 million, alone or with a spouse or spousal equivalent, excluding the primary residence under the SEC calculation; or
- a Series 7, 65, or 82 license in good standing.
Other categories apply to certain insiders, investment professionals, entities, trusts, and family offices. Accreditation is an eligibility status. It is not a measure of investing skill, and it does not make a deal good.
Our accredited investor guide explains the categories and verification methods in more detail.
Public markets provide adjacent exposure
Public-market securities are the practical route when liquidity, standardized disclosure, and easy position sizing matter more than direct startup ownership. Exchange-listed stocks, ETFs, mutual funds, and publicly traded business development companies are generally available without accredited status.
These assets can provide several types of adjacent exposure:
- shares in recently public or high-growth companies;
- a fund holding a group of public technology companies or recent initial public offerings;
- a listed company that owns private-company stakes; or
- a listed business development company that finances private and smaller public businesses.
You are buying the public vehicle, with its management decisions, expenses, other holdings, and public-market price movement. You do not receive the startup’s cap-table rights or the same economics as its early private investors. Exchange trading often provides an easier resale path, but market liquidity and price stability still vary.
Choose the route that matches the job
Start with the outcome you want, then evaluate the available structure.
- Direct early-stage investing with broad legal access: Reg CF provides a purpose-built public route. Your aggregate cap, the security terms, and limited resale remain material constraints.
- A direct security with a qualified offering circular: Regulation A may fit. Tier, listing plans, ongoing reporting, and offering terms determine the real trade-offs.
- An invitation from a founder or private network: Confirm whether the issuer is relying on Rule 506(b) or another exemption and whether you satisfy every condition. Social access is not legal eligibility.
- Liquid, diversified exposure to innovation: A public fund or listed company is closer to that job. It is adjacent exposure rather than angel investing.
Working for a startup can also create equity exposure through compensation. It is not an investment opportunity available to the public, and it concentrates your income and wealth in the same company. Treat it as a separate employment and portfolio decision.
Set a risk budget before picking companies
Startup securities are speculative. A startup portfolio may have more failures than winners, and you can lose the entire investment in any one company.
Even when a company survives, your stake can be diluted, a SAFE may never convert, and a paper valuation may never become cash.
Accreditation does not change any of those facts.
The SEC’s crowdfunding risk guidance highlights total loss, limited disclosure, valuation uncertainty, fraud, and resale limits. Use only capital you can afford to lose and leave untouched for an indefinite period. The legal maximum under Reg CF or Regulation A is a ceiling, not a sensible target.
A portfolio can reduce the impact of one company failing. It cannot remove startup, selection, valuation, or liquidity risk. Timing and luck still shape outcomes.
Our co-founder and general partner Elizabeth Yin gives the useful instruction in Democratizing Knowledge: “Don't try to pick a co. Select a portfolio.”
Decide your total startup allocation before viewing a pitch. Set a per-company check size that lets you spread that allocation without raiding emergency savings or near-term goals. Track direct startup investments separately from public funds so indirect holdings do not create a false impression of diversification.
Use a seven-step due-diligence process
Access answers whether you may buy. Due diligence answers whether the terms and business deserve your risk budget. Elizabeth’s process advice in Democratizing Knowledge is equally direct: “The more disciplined you are in your thought process/rubric, the more you can improve over time.”
- Identify the exemption and security. Find Reg CF, Regulation A, Rule 506(b), or another stated pathway in the offering documents. Write down whether you are buying shares, debt, a SAFE, or an interest in an SPV.
- Read the controlling filing. For Reg CF, read Form C and its amendments. For Regulation A, read the qualified Form 1-A offering circular and continuing reports. For a private placement, read the subscription agreement, company disclosures, and governing SPV documents. Regulators do not approve an investment by accepting or qualifying a filing.
- Confirm the intermediary’s status. A Reg CF transaction must run through a registered broker-dealer or funding portal. FINRA’s funding-portal roster shows current status, including suspensions. Appearance on a roster does not mean FINRA has approved the investment.
- Reconcile the business claims. Compare the pitch with financial statements, customer concentration, revenue quality, cash burn, runway, debt, related-party transactions, and how the new capital will be used. Separate signed revenue from pilots, letters of intent, waitlists, and forecasts.
- Rebuild the ownership economics. Map the valuation or valuation cap, discount, liquidation preference, conversion triggers, outstanding SAFEs and notes, option pool, senior debt, and likely dilution. Confirm which information, voting, pro rata, or repayment rights you receive.
- Count every cost and restriction. Include platform or SPV fees, carried interest, transfer limits, redemption terms, and tax-reporting complexity. A low minimum does not make an expensive or poorly priced security attractive.
- Write the failure case before investing. Record the strongest reason to pass, the evidence that would change your view, and the maximum loss in dollars. Save that note with the documents so later updates can be compared with the original thesis.
Walk away when the issuer cannot explain the security, refuses reasonable questions, pressures you to act immediately, or describes an SEC filing as approval. Scarcity is a sales condition, not proof of investment quality.
Build judgment before access expands
If you want to get better at evaluating startup deals before you invest, apply to Angel Squad to learn our approach, review curated deal flow, and compare notes with other investors. You do not need accredited status to join. Eligibility to participate in a specific investment depends on that offering’s rules.
This material is for educational purposes only and is not investment, legal, tax, accounting, or valuation advice. Startup investments are speculative, illiquid, and long-term, and you can lose all invested capital. Past results and current marks do not guarantee future results. Read the governing offering documents and seek independent review from qualified legal, tax, and financial professionals before acting.











