
How to Handle Investor Rejection: Turning "No" into Future "Yes"
Brian Nichols is the general manager of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
An investor pass can sting, especially after a good meeting or encouraging questions. It also creates an operating decision. Do you close the conversation, ask for feedback, follow up, or return later with new evidence? No follow-up, update, traction milestone, or community can guarantee that an investor will change a decision or invest. A clear answer protects your time, respects the investor’s boundary, and helps you improve the next pitch.
Why investors pass without making it personal
Techstars’ rejection guide lists thesis, fit, and timing as possible reasons for a pass. Those reasons do not amount to a verdict on the founder or business.
Fund selection adds another constraint. A venture fund has limited capital and must choose among many opportunities. Return on investment (ROI) is one lens in that choice. Our co-founder and general partner Elizabeth Yin writes, “Investors are looking for THE VERY HIGHEST ROI opp. NOT great businesses.” That is her perspective on fund selection, rather than a rule that describes every investor.
Your job is to identify what kind of pass you received. You can also learn more about how investors make a pass decision. One investor’s decision is still one decision, made through that investor’s particular lens.
Classify the response before you act
Put the response into a category before sending another message. Each category has a different next step and stop rule.
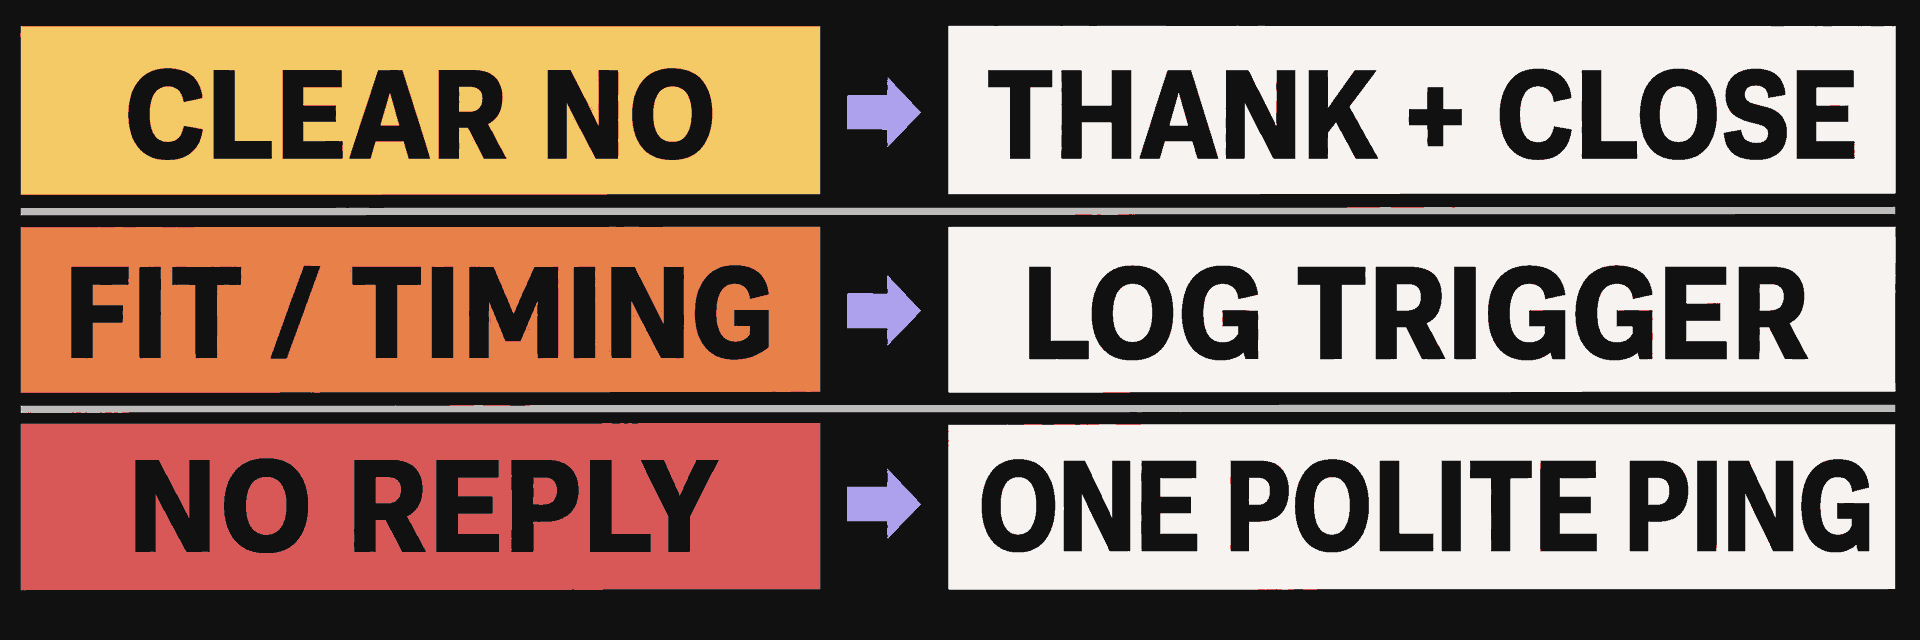
- Clear no: Thank the investor and close the active pursuit. Send future updates only if the investor explicitly invited them.
- Fit or timing pass: Record the stated constraint and the condition that would make a future conversation relevant. Revisit it only after that condition changes in a material way.
- No reply: Send one respectful follow-up with a direct question and an easy way to decline. If that gets no response, close the active sequence.
- Repeated feedback: When the same concern appears independently across several conversations, treat it as a hypothesis to test. Change the pitch, gather better evidence, or examine the business itself. Test the recurring concern in later conversations, and leave the individual pass closed rather than debating it.
Silence is ambiguous. It is not permission for unlimited outreach. A fit pass is also different from a promise to reconsider later.
Ask for one useful piece of feedback
Ask for feedback when the investor has enough context to give it. Someone who joined a substantive meeting, reviewed your materials, or discussed the company with partners is more likely to have a concrete answer than someone who declined a cold email.
Use one narrow question: “What was the main issue that kept you from moving forward?” First Round’s partner-meeting guidance recommends asking what held the firm back after a substantial process. The investor may still decline to answer, and that is fine.
If you receive an answer, thank the investor and record the wording. Do not use the response as an opening to rebut the decision. You are collecting a signal for the next conversation.
Suppose an investor says they could not see evidence of repeat usage. Your next step might be to clarify the retention slide, interview customers, or measure retention over a longer period. Reopen that investor conversation only when you have relevant new evidence and continued contact is welcome.
Follow up without crossing a boundary
The best follow-up starts before the meeting ends. Agree on the next step and timing. If you promised a deck, customer reference, or data-room answer by Friday, send it by Friday and state what happens next.
When no timeline was agreed, send one message that adds value or asks for a decision. Name the company, remind the investor of the relevant discussion, share the promised item or material change, and ask one direct question. Give the recipient a graceful way to close the loop.
An explicit decline ends the active sequence. A second no after re-engagement does too. Use the time to prepare for the next investor call, rather than pushing past a stated boundary.
Use updates to show material progress
Investor updates can keep an invited relationship current. Ask before adding a passing investor to a distribution list when permission is unclear, and honor any request to stop. Share only information appropriate for that audience.
A useful update includes:
- the period or date covered;
- one material win;
- one material challenge;
- the evidence or metric most relevant to the company now;
- the next focus; and
- one specific ask.
NFX uses monthly updates as a default and recommends off-cycle notes for material changes. That cadence is practitioner guidance, not a universal schedule. Uncork’s update structure also includes highlights, lowlights, metrics, next focus, and asks, with a boundary around proprietary information.
Our co-founder and general partner Elizabeth Yin writes, “Rejections are not forever.” Her point applies when you have relevant new evidence and the investor welcomes future contact. It does not turn every pass into a pending yes. If updates are part of your fundraising process, report real progress and real challenges as part of modern investor relations.
Keep a simple pass log
Customer relationship management (CRM) software can track investor conversations, but a spreadsheet works too. The useful part is the record, not the tool.
For each investor, capture:
- contact and conversation date;
- source of the introduction;
- response type;
- the investor’s concern in their own words;
- promised materials;
- next step and date;
- permission to send updates; and
- do-not-contact status.
Review the log for recurring concerns. One vague opinion may not deserve a change. The same precise concern from several independent investors deserves a closer look. The log should also prevent accidental over-contact by making a closed conversation visible to everyone on your team.
Move the fundraising pipeline forward
A useful pass can improve the next conversation. It does not have to reopen the old one. Keep meeting relevant investors while you test repeated feedback and build the evidence your company needs.
Y Combinator recommends recognizing a turn-down, parting on good terms, and staying truthful and professional. You control the accuracy of your pitch, the quality of your follow-through, your records, and your tone. You do not control whether an investor replies or changes their decision. No process can guarantee capital or turn a specific pass into an investment.
See the decision from the other side
If you want to understand how early-stage investors evaluate opportunities, learn with Brian Nichols, general manager of Angel Squad, alongside aspiring and active angels. Apply to join the community.
This material is educational and is not legal, fundraising, or investment advice. Startup fundraising outcomes are uncertain.











