
How to evaluate market size for a startup
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Every pitch deck seems to have a giant market number. That number can tell you whether the founder is aiming at a pond or an ocean. It cannot tell you whether the startup has a boat, a route, or customers willing to climb aboard.
Investors need a repeatable way to evaluate reachable demand, customer acquisition, market pull, expansion, and timing. No diligence process removes early-stage risk, and many startups fail even when the market math looks reasonable.
Start with TAM, SAM, and SOM
The standard market-size terms describe three different boundaries:
- Total addressable market (TAM): the annual revenue opportunity if the company could serve every potential buyer in the broad category.
- Serviceable addressable market (SAM): the part of that market the product and business model can serve now, given geography, customer type, regulation, and delivery constraints.
- Serviceable obtainable market (SOM): the share the company could plausibly win within a stated period, given its sales capacity, channels, competition, and current evidence.
Treat TAM as a boundary check. A $20 billion TAM can hide expensive distribution and weak willingness to pay. A modest starting market can grow through new products, customer segments, or behavior changes.
A quick bottom-up check is more useful: multiply the number of plausible buyers by realistic annual revenue per buyer. Andreessen Horowitz’s market-sizing guidance favors this approach because it forces the analysis to include the target customer, willingness to pay, and route to market.
Keep that calculation compact during deal screening. Our guide to doing a legit market analysis covers the detailed top-down and bottom-up mechanics, source gathering, and market model. Here, the job is to decide whether the founder’s number survives investor diligence.
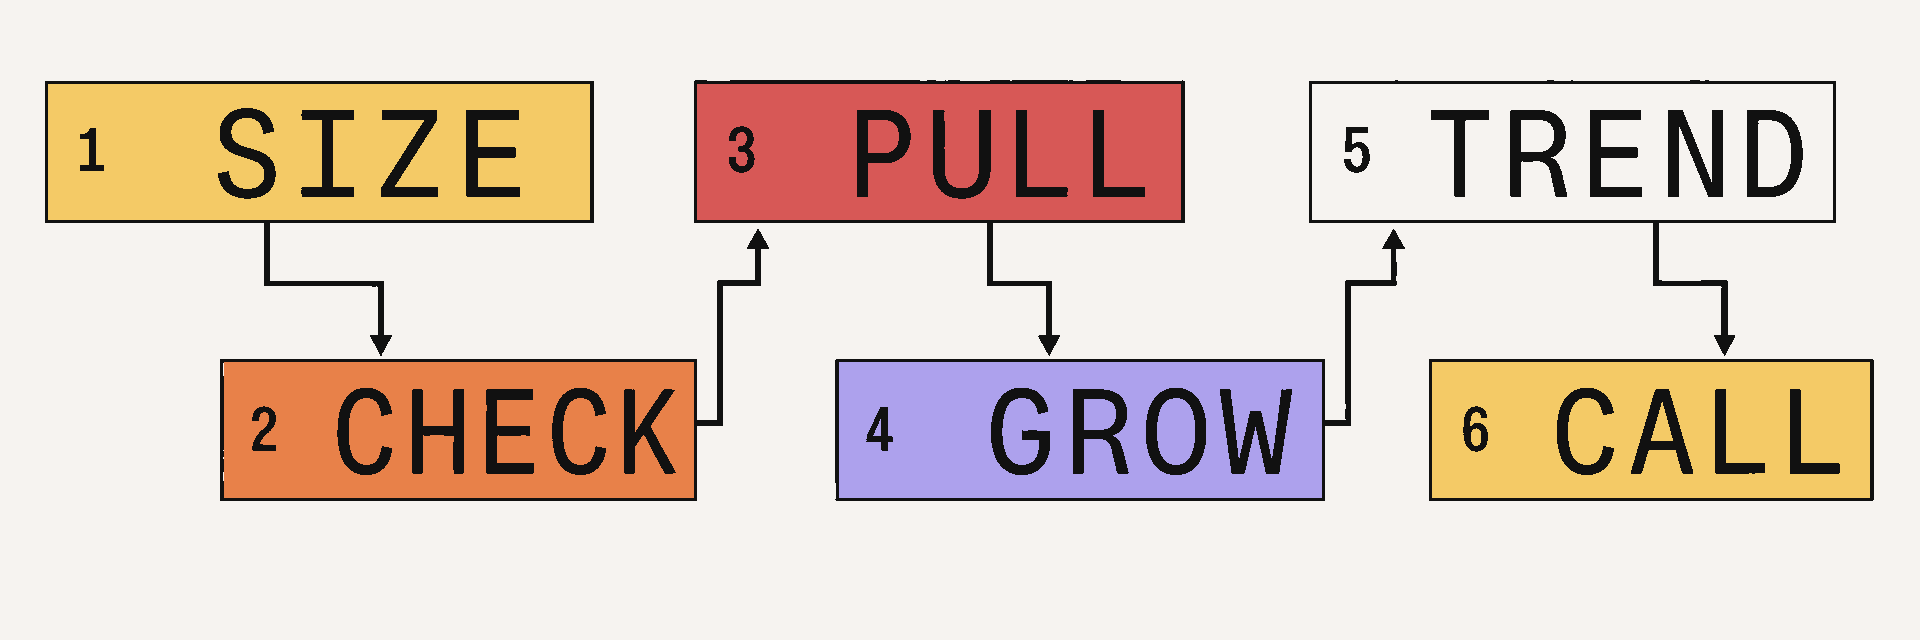
A six-step process for evaluating startup market size
Work through the steps in order. A broad estimate is useful only after its inputs survive verification, and verified demand matters only if the startup can reach and expand from it.
1. Size the reachable customer pool
Write down the specific buyer, geography, use case, and time horizon. “Healthcare” is an industry. “Independent U.S. clinics with 20 to 100 employees and no dedicated scheduling system” is a segment you can count.
Then run the bottom-up sanity check by multiplying the number of plausible buyers by realistic annual revenue per buyer to estimate the serviceable annual market.
Use the right unit for the model. A marketplace may need transaction volume multiplied by its take rate. A usage-based product may need annual units multiplied by price per unit. The result is still a boundary, not a sales forecast.
For U.S. business markets, County Business Patterns provides establishment counts by industry, geography, and employment size. The Quarterly Census of Employment and Wages can help you examine industry employment and wage trends. Trade associations, regulator records, procurement databases, and public-company filings may be better for specialized markets.
2. Verify the count, price, and buyer behavior
Ask where every important input came from. Look for customer interviews, signed contracts, pilots, invoices, cohort data, and source records that can be checked.
The founder should be able to explain:
- which potential users control the budget;
- what buyers use or pay for today;
- why the proposed price fits the value created;
- which buyers are excluded and why;
- how many customer conversations informed the assumptions.
MIT’s New Enterprises course recommends building a bottom-up estimate from primary market research, then using top-down reports as a complement. Customer evidence exposes constraints that a broad industry report can miss.
3. Test acquisition friction and repeatability
A startup does not own its SAM. It must reach prospects, win their attention, close them, and deliver enough value to retain them.
Map the path from prospect to paying customer. Ask which channel produced each current customer, how long a sale takes, who performs the work, what the channel costs, and whether the result can repeat beyond the founder’s network. Our customer acquisition thesis explains why distribution belongs in the investment case rather than in a later marketing plan.
This is where market pull enters the decision. Our co-founder and general partner Elizabeth Yin wrote, “Loosely, I define it as how quickly customers adopt your product.” Look for customers who move through the funnel faster, tolerate an early product’s rough edges, return without repeated prompting, refer peers, or expand usage.
One enthusiastic design partner is useful evidence. A repeatable pattern across unrelated customers is stronger.
4. Test expansion paths
The first wedge does not need to contain the company’s whole future. It needs to create a credible base for growth.
Examine each expansion path separately:
- More spend from the same customer: extra seats, higher usage, payments, analytics, services, or another workflow.
- More customers in the same segment: a repeatable channel reaches similar buyers without acquisition costs rising out of control.
- Adjacent segments: the product solves a related problem with limited new development and a realistic route to buyers.
- New geographies: demand travels, while language, regulation, support, and distribution remain manageable.
Ask what the current product earns the right to sell next. A list of possible markets is not an expansion plan. Evidence might include customer requests, usage across departments, paid add-ons, or a partner channel already reaching the adjacent segment.
5. Judge trajectory and “why now”
Current size is a snapshot. Investors also need the direction and speed of change. Elizabeth’s conclusion is direct: “Trajectory matters more than TAM.”
Look for a technology shift, cost curve, regulation, new distribution channel, or behavior change that makes adoption easier now. Then ask whether the startup’s own data moves with that shift. Growth in qualified inbound demand, shorter sales cycles, faster activation, better retention, and rising expansion revenue are stronger signals than a category growth rate copied from a report.
In the same market-pull discussion, Elizabeth sketched a simplified annual revenue path of $1 million, $6 million, $15 million, $40 million, and $100 million over five years. This is an illustration of acceleration, not a required trajectory or projection. The real question is whether the company’s evidence supports a pace that fits your investment thesis.
Timing still involves judgment. Bill Gross compared five factors across hundreds of startups and found that one factor stood out in his sample. Use the “why now” explanation as a hypothesis, then test it against customer behavior and industry data.
6. Triangulate the estimates and decide
Build at least two views of the market. One can start with industry or government data and narrow to the target segment. Another can start with observed customers, prices, conversion, and channel capacity and work upward.
The estimates do not need to match. You need to understand why they differ. A World Bank market-mapping guide notes that cross-checking estimates from different sources can reduce bias and improve the conclusion.
Finish with a short decision record:
- the market estimate or range you believe;
- the three assumptions carrying the most weight;
- the evidence for market pull;
- the most credible expansion path;
- the event or data that would change your view;
- the main unresolved risk.
Thoughtful investors can reach different conclusions from the same evidence. Writing the assumptions down gives you something concrete to compare with later results.
Hypothetical example: the giant market and the reachable wedge
Consider a fictional company, RosterFox, that sells scheduling software to independent veterinary clinics. This is a hypothetical, simplified market-size example, not a forecast.
The pitch deck cites a $12 billion global “animal health technology” TAM. That number is too broad to support an investment decision because it includes products, buyers, and geographies RosterFox cannot serve.
The investor rebuilds the first market from the bottom up:
- The founder identifies 18,000 potential U.S. clinics from an industry directory.
- Interviews and current customer data suggest that 40% fit the product’s staffing, system, and budget requirements. That leaves 7,200 plausible buyers.
- The current annual contract price is $6,000. The serviceable annual market is therefore $43.2 million.
- A channel partner can introduce the company to 1,500 of those clinics over two years. Applying the startup’s 12% introduction-to-paid conversion rate yields 180 customers and $1.08 million in obtainable annual revenue if the assumptions hold.
The smaller number is more useful because each input can be tested. The investor now knows what must be true: the directory count is accurate, 40% of clinics fit, the channel reaches qualified buyers, the 12% introduction-to-paid conversion rate survives at a larger scale, and customers continue paying $6,000.
The market can still support a large outcome if RosterFox shows fast adoption, efficient repeatable acquisition, and credible expansion into payroll or multi-location clinic groups. If those paths depend on buyers, products, or channels the team has never tested, they belong in the risk section rather than the base case.
Market-size red flags
Pause when you see any of these:
- “We only need 1%.” The founder applies an arbitrary share to a giant category without explaining who buys or how the company reaches them.
- Industry revenue presented as software TAM. The money a customer’s industry earns is not the amount it will spend on this product.
- Users and buyers treated as the same group. The person with the pain may lack budget authority or willingness to pay.
- A market report with no source trail. The deck cites a headline number but omits the year, geography, segment definition, or original dataset.
- One estimate presented as certainty. No range, alternate method, or sensitivity check appears.
- SOM disconnected from capacity. The obtainable market ignores sales headcount, channel reach, sales cycle, conversion, implementation, or competition.
- Expansion by wish list. The plan names new products and countries without customer evidence or a distribution path.
- Growth that depends on endless paid acquisition. Customer economics and retention do not leave room for rising channel costs.
- A stale “why now.” The cited trend is old, slowing, or unrelated to the startup’s customer behavior.
Questions to ask the founder
Use a few focused questions rather than debating the TAM slide line by line:
- Which customer segment can you serve today, and how many buyers are in it?
- Which source supports that count, and what did you exclude?
- What do those buyers pay now, and what evidence supports your price?
- How did your last ten customers find you, and which channel can repeat?
- What customer behavior shows pull rather than founder push?
- What can you sell to the same customers next, and who has asked for it?
- Which market change makes this possible now?
- Which assumption would shrink the opportunity most if it were wrong?
These questions fit naturally into a broader set of pitch meeting questions. The goal is to expose the model’s load-bearing assumptions while the founder is available to explain them.
A useful market is reachable, responsive, and expanding
Market size still matters. It sets the outer boundary of a startup’s opportunity. Investment judgment comes from the path between today’s customer and that boundary.
The strongest market cases connect a countable starting segment to demonstrated willingness to pay, repeatable acquisition, visible market pull, and credible expansion. That evidence will not make the investment safe. It will make your reasoning specific enough to challenge, record, and improve.
See how investors put the questions together
Take the free, interactive Angel Squad demo to see how our community reviews early-stage deals. It takes two minutes and requires no signup.
This material is for educational purposes only and is not individualized investment advice. Early-stage startup investments are speculative, illiquid, long-term, and may result in a total loss. Make investment decisions based on your own circumstances and with qualified independent advisers.











