
How to Start Angel Investing: The Unfiltered Truth
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Becoming an angel investor means putting your own money into private startups. Before the first check, you need an honest assessment of the risk, workload, and long wait, plus a practical way to move from learning about companies to signing a deal you understand.
The Legal Requirements Depend on the Offering
In the U.S., accredited-investor status is a legal category based on income, net worth, credentials, or other qualifying criteria. Some startup offerings require it; others admit non-accredited investors. A small check doesn't bypass an offering's rules.
Startups raise money by selling securities, such as shares or contracts for future shares. The company or vehicle selling the investment is the issuer. Its securities-law exemption, an exception to registration requirements, determines who can participate.
The U.S. Securities and Exchange Commission (SEC) has different rules for these common offering types:
- Rule 506(c): All purchasers must be accredited investors, and the issuer must take reasonable steps to establish that status. This route permits broad advertising under the SEC’s 506(c) rules.
- Rule 506(b): An issuer may sell to accredited investors and up to 35 non-accredited investors in any 90-calendar-day period. Non-accredited purchasers must have sufficient financial and business knowledge, alone or with a purchaser representative, to evaluate the investment. Additional disclosures apply, and general solicitation is prohibited under the SEC’s 506(b) rules. An issuer can still choose to accept only accredited investors.
- Regulation Crowdfunding: Accredited and non-accredited investors can participate through an online platform operated by a registered broker-dealer or funding portal. Non-accredited investors have aggregate investment limits across these offerings over a 12-month period under the SEC’s crowdfunding rules.
For individuals, common accreditation routes include income exceeding $200,000 individually, or $300,000 with a spouse or spousal equivalent (a partner in a relationship generally equivalent to a spouse), in each of the prior two years with a reasonable expectation of the same in the current year; net worth exceeding $1 million excluding the primary residence; or a Series 7, 65, or 82 license held in good standing. The SEC’s accreditation criteria include other categories and rules for calculating net worth.
These are U.S. examples. Your location, the investment vehicle, and the offering documents can add requirements. Legal eligibility and financial readiness are separate decisions.
The Capital Reality Check
You need capital you can genuinely afford to lose completely. Its loss shouldn't delay a home purchase, undermine retirement savings, drain an emergency fund, or create financial stress.
Imagine every angel investment returning zero. If that would materially change your life, reduce the allocation or stay in learning mode. An account balance that helps you qualify as accredited isn't automatically money available for startup investing.
Our co-founder and general partner Elizabeth Yin gives a blunt warning: “Most of your investments will return $0.” Treat that as a reason to plan for losses across a portfolio, rather than a precise forecast for your own investments.
There is no universal starting budget or safe percentage of your net worth. The relevant amount depends on your obligations, other investments, offering minimums, fees, and plans for later checks. If you're stretching to find the money, you're probably allocating too much.
Startup investments are illiquid, meaning you usually can't sell when you need cash. You may hold them for many years or indefinitely, and a company that survives may never produce a cash return. The SEC describes these private-placement risks, including total loss and limited disclosure.
The Time and Emotional Commitment
Most of the work is routine evaluation and maintenance. You'll review opportunities you pass on, attend educational sessions, read documents, and follow updates from companies making uneven progress. Celebrating exits is a much smaller part of the job.
The workload depends on your route. Investing directly and helping with diligence takes different effort from reviewing a syndicate lead's work. Neither removes your responsibility to understand the investment.
Before committing money, be candid about whether you can sustain these habits:
- Recurring attention: You can make room for learning, deal evaluation, recordkeeping, and portfolio updates without neglecting work, family, or health.
- Patience through uncertainty: You can live with long stretches of ambiguous progress, failed investments, and no dependable date for getting money back.
- Limited control: You can support founders while accepting that a small investment usually gives you little control over hiring, pivots, or the company's eventual outcome.
Genuine interest in startups helps make that work worthwhile. Learning and relationships can have value, but they don't reimburse a financial loss.
The Knowledge Requirements Are Learnable
You need to understand portfolio construction, startup business models, common securities, and basic evaluation frameworks. You don't need a business degree, a finance background, a job in venture capital, or a ready-made founder network.
Professional expertise can give you a useful starting lens. Someone who has sold software to hospitals may understand procurement delays and buyer incentives that a pitch deck glosses over. Turn that experience into specific questions, while recognizing where you need another person's expertise.
Thoughtful participation also builds relationships. Share relevant knowledge, ask clear questions, and follow through on introductions you offer. Virtual communities can reduce geographic barriers, although investment eligibility and access still vary.
Judgment takes longer than learning terminology. As Elizabeth Yin puts it, “Investing requires practice like everything else.” Seeing companies, recording decisions, and following what happens afterward gives that practice a feedback loop. No investment count automatically makes you good at this.
The Steps to Start Angel Investing
The time windows are illustrative. Move forward when the work is done; a calendar doesn't make you ready or set an exit date.
1. Establish Eligibility and Choose a Route (First Weeks)
Start with a route whose offerings can admit you. Ask the issuer or platform which exemption applies and what investor documentation it requires. Complete that process before committing funds.
Also decide how you'll hold the investment. A direct investment means buying the startup's security yourself. A syndicate is a group investing alongside a lead; it often uses a special purpose vehicle (SPV), a separate entity that pools investors' money to invest in the company. In that case, you generally own an interest in the SPV, and the SPV holds the startup investment.
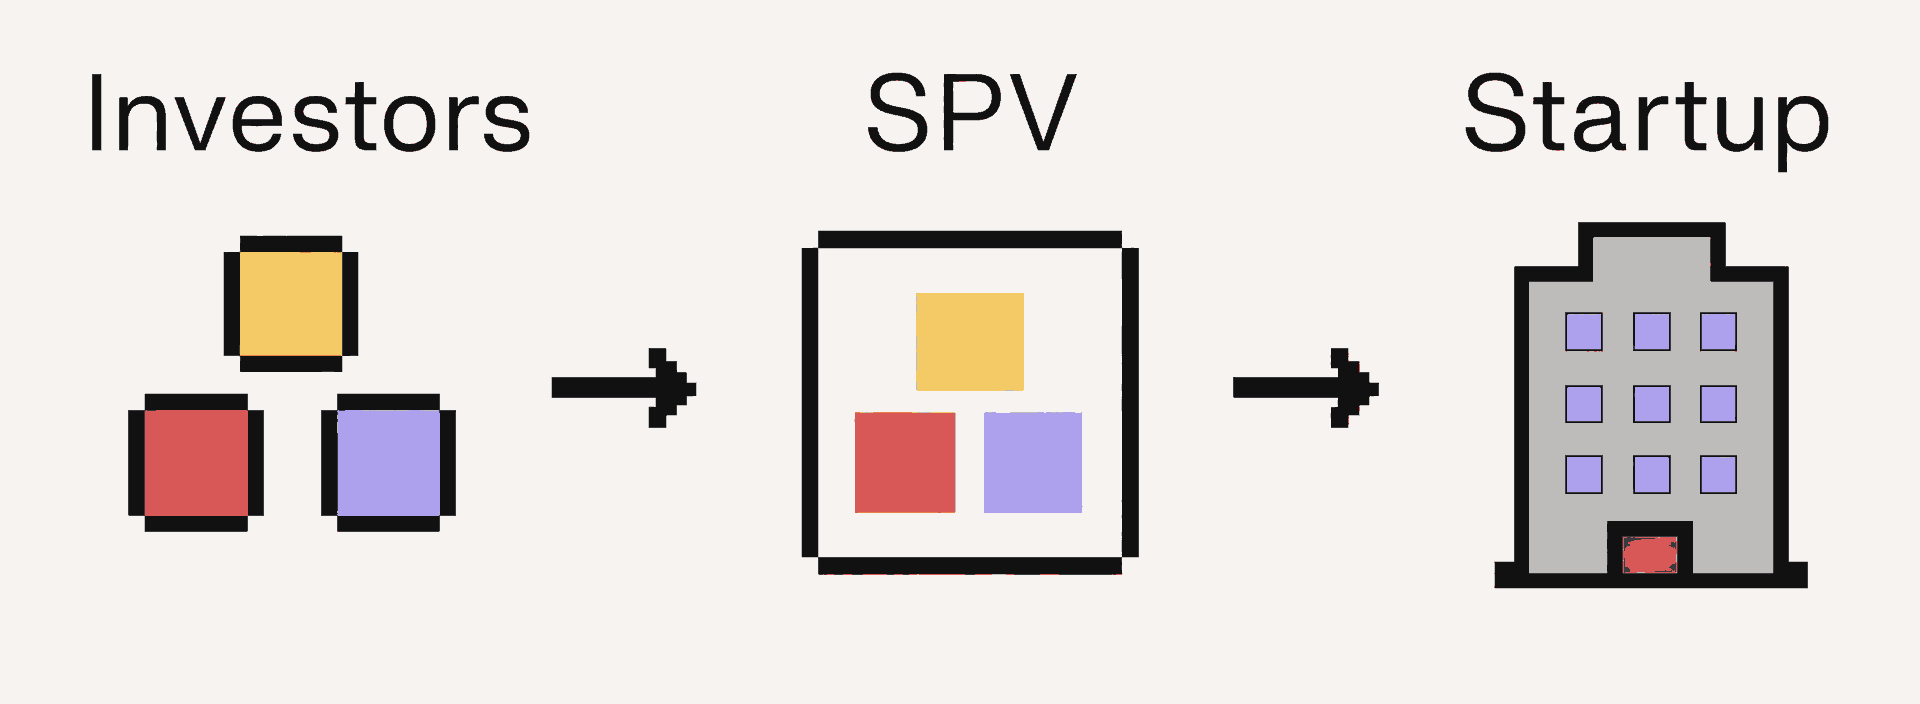
An SPV adds a layer of documents, fees, administration, and potentially its own eligibility requirements. It doesn't automatically create access to a deal or make the underlying startup safer.
2. Set a Capital Plan Before Seeing Deals (First Weeks)
Write down your total startup-investing budget, a maximum initial check size, and any money reserved for possible follow-on investments in later rounds. Include transaction costs and fees in the plan.
Choose a check size that leaves room for other investments. If one offering's minimum would consume most of your budget, pass or choose another route. A compelling pitch doesn't expand the amount you can afford to lose.
3. Learn the Fundamentals (First Weeks)
Learn how a startup makes money, how future fundraising can dilute ownership, and how investment terms affect what you receive. Practice explaining a company's customer, business model, and use of the new funding in plain language.
Our startup evaluation framework gives you a starting set of lenses: team, target market, technology, traction, and terms. Use a framework to organize questions and evidence, without treating a score as proof that a company will succeed.
4. Select a Community and a Deal-Flow Source (Following Weeks)
Deal flow is the stream of investment opportunities you see. A learning community, angel group, syndicate, or crowdfunding platform can help you see companies and hear other investors' reasoning. Choose support that fits your experience and schedule.
When comparing communities, focus on four things:
- Deal access: Relevant companies, clear eligibility and allocation rules, and an explanation of how opportunities are selected.
- Education: Practical teaching about evaluation, terms, portfolio construction, and risk.
- Peer support: Members who answer questions, disagree constructively, and share useful experience.
- Operational help: A clear process for documents, payments, updates, and tax records, with responsibility and fees explained.
Ask current members how those things work in practice and what they wish they'd understood before joining. Consider whether the community's online discussions or local meetups give you a realistic way to participate.
In Angel Squad, you can learn from Hustle Fund's investing approach, review curated opportunities and their investment memos, and discuss them with peers. Membership doesn't require accreditation; investing in our relevant offerings does. There is no obligation to invest, so you can use the community for learning before putting money at risk.
5. Observe and Keep a Decision Log (Following Months)
Review opportunities without investing first. Record the date, company, reasons you'd invest or pass, evidence behind those reasons, and the uncertainty most likely to change your mind. A dated investment tear sheet can keep the facts, assumptions, and open questions together.
For example, you might like a founder's hospital-software experience but pass because you don't yet understand whether pilot customers will become paying buyers. Later updates can teach you something about that assumption even though you didn't write a check. Keep the same log for actual investments.
6. Evaluate a Deal Independently (After Observation)
Read the memo and founder materials, then form your own view. A lead investor's participation gives you context; it doesn't guarantee a good investment.
Look for evidence of customer demand, founder execution, a credible business model, and a specific plan for the money being raised. Ask about cash needs, the next milestone, competition, and risks that could prevent progress. Customer conversations and founder references can help where available and appropriate. Missing evidence belongs in your decision log.
Our co-founder and general partner Shiyan Koh describes our belief that “great founders can look like anyone, and come from anywhere.” Assess relevant insight and execution without treating pedigree as a substitute for evidence.
7. Understand the Documents, Fees, and Rights (Before Signing)
Know what you're buying. Priced equity gives you shares now. A Simple Agreement for Future Equity (SAFE) is a contract for future equity under specified conditions; a convertible note is debt that may convert into equity under its terms.
Read the actual investment and subscription documents, plus the vehicle agreement for an SPV. Identify the purchase price or conversion terms, transfer restrictions, information rights, and provisions affecting payouts. A valuation cap sets a limit used in calculating a SAFE's conversion price; it doesn't promise an eventual company value.
For pooled investments, identify management or administration fees and carried interest, the manager's share of investment profits. Understand who receives company updates, who makes vehicle decisions, and what tax documents you can expect.
Have qualified independent legal and tax professionals review your investor entity, rights, and reporting obligations as needed. Entity choices, deductions, and tax benefits depend on your facts and the governing rules.
8. Make the First Investment Only When It Fits (When Ready)
Proceed when the opportunity fits your eligibility, capital plan, and written rationale, and you understand the documents and unresolved risks. Passing remains a valid outcome.
Complete the issuer's or platform's onboarding and signing process, then fund through its established payment process. Resolve changed payment instructions through an independently established contact. Save executed agreements, funding confirmation, fee details, and the final decision memo together.
9. Build a Portfolio at a Sustainable Pace (Subsequent Years)
Repeat the process within your budget. Spread exposure across companies and investment periods, and consider whether your holdings depend on the same sector, customer base, or market conditions.
Diversification can reduce dependence on one company's outcome. It can't prevent losses or guarantee a return. There is no compulsory number of checks per quarter or magic portfolio size.
Treat a follow-on round as a new decision about the company, terms, and your remaining capital. Access to later rounds isn't assured, and having invested once doesn't obligate you to invest again.
10. Manage the Investments and Stay Patient (Many Years)
Keep a record of each investment's cost, security or vehicle, documents, fees, updates, and any cash distributions. Calendar the reporting and tax tasks relevant to your holdings.
Compare company progress with your original rationale. Offer help with hiring, customer introductions, or a focused project when the founder wants it. Respect confidentiality and avoid creating work for the team.
A new fundraising valuation can change an investment's estimated paper value. It doesn't put cash in your account. Companies can take much longer than expected to exit, remain private indefinitely, or fail. Keep learning without building your personal spending plans around an anticipated payout.
You Can Start Learning Before You Start Investing
If risk capital or time is scarce, keep your money out of startups for now. Observe pitches, maintain a decision log, or contribute relevant expertise as an accelerator mentor. You can learn about teams and businesses without buying a security.
If one offering excludes you, that doesn't mean every route does. Choose an eligible route only if the financial and practical fit also holds. Becoming an angel investor is optional, and waiting is a reasonable decision.
If you're ready to learn with other investors and build that process, apply to Angel Squad.
This content is educational and does not constitute investment, legal, or tax advice. Startup investments are speculative, illiquid, and long-term, and you can lose your entire investment. Seek independent advice from qualified legal and tax professionals about your circumstances and the governing investment documents.











