
The Democratization of Angel Investing
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Angel investing once depended heavily on who you knew. Education traveled through private conversations, deal flow came through trusted networks, diligence required context that beginners rarely had, and practical check sizes kept many qualified people on the sidelines.
Access is wider now. The word “democratization” can still hide as much as it explains. The useful question is which barriers fell, which only moved, and what a new investor must still decide for themselves.
Wider access has three separate gates
The U.S. angel market is large, active, and hard to measure because many private transactions are not publicly reported. The University of New Hampshire’s Center for Venture Research estimated $17.9 billion in angel investment during 2024, from 445,535 active angels funding 55,346 ventures.
Broader participation operates at different levels. Three gates often get blurred together:
- Community access: You may be able to join a learning community, attend workshops, discuss deals, and build a network without being an accredited investor.
- Offering eligibility: Your legal ability to invest depends on the offering, your status, your location, and the applicable securities rules. Passing the Series 65 exam by itself is not enough to qualify through that route. The U.S. Securities and Exchange Commission (SEC) says you must hold the relevant state investment-adviser-representative license in good standing.
- Investment judgment: Legal eligibility says nothing about whether the company, price, terms, or portfolio fit is good for you.
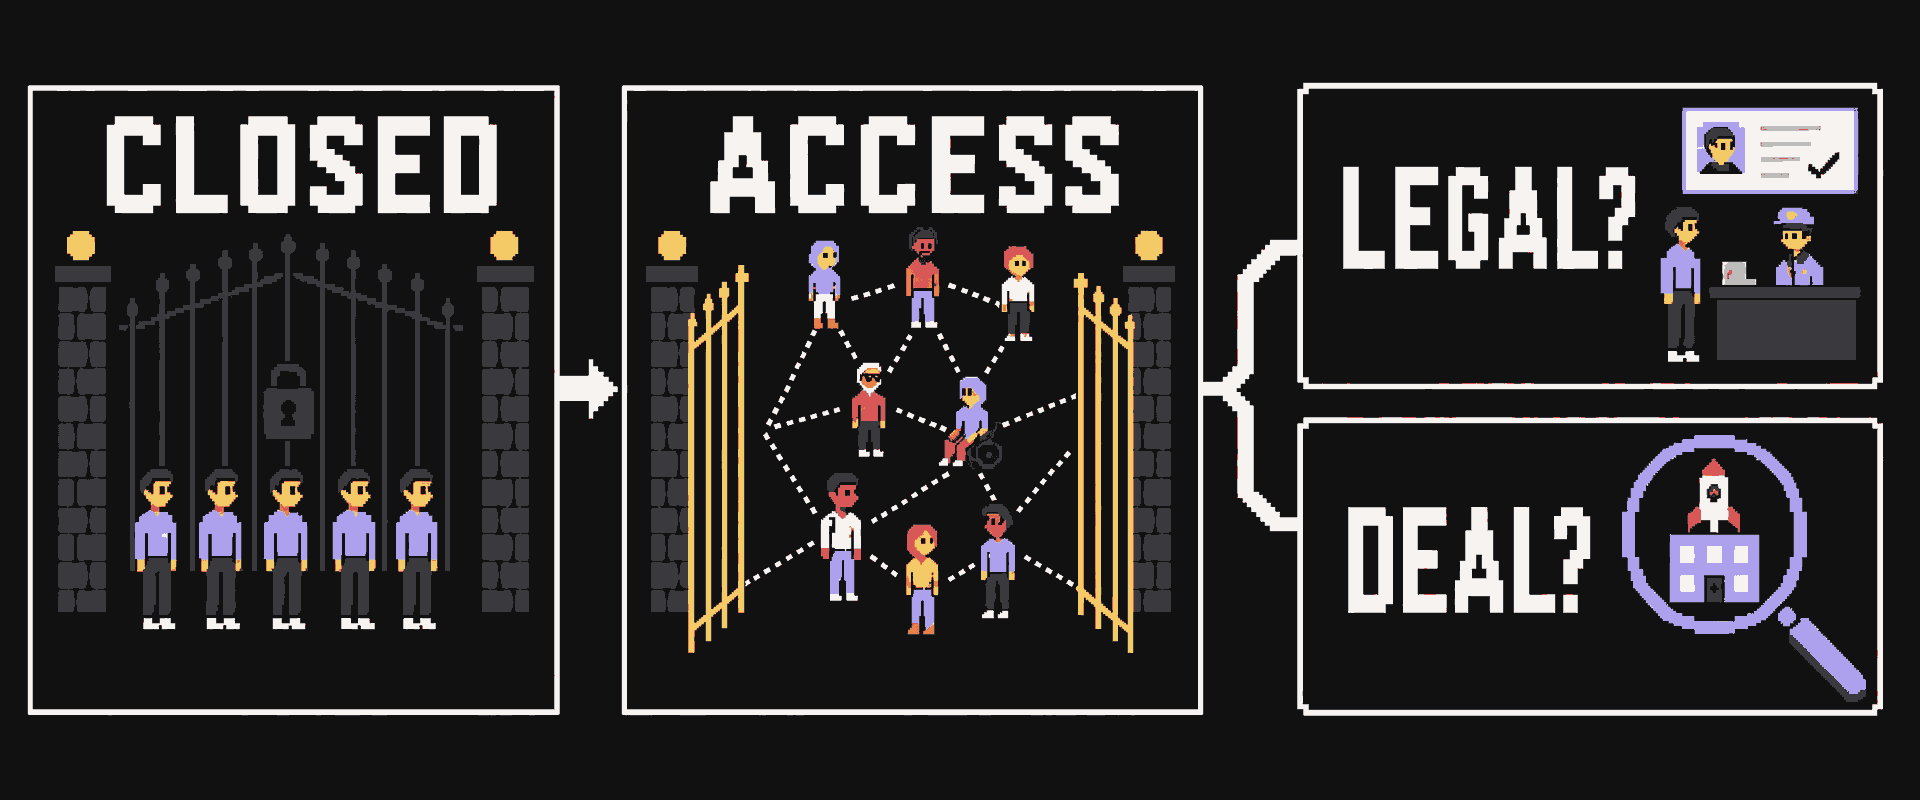
Those gates are independent. A community can help you learn. A platform or special purpose vehicle can make a smaller check workable. Neither one turns an ineligible investor into an eligible one or a weak deal into a strong one.
Five changes widened angel-investing access
Education, community workflows, investment infrastructure, securities rules, and remote participation changed different parts of the process.
1. Education became repeatable
Formal angel education predates today’s online communities. In 2005, the Wisconsin Angel Network held four Kauffman Foundation seminars in person. The Angel Capital Association now offers formats ranging from instructor-led workshops to a one-hour on-demand webinar. Those formats carry lessons beyond one local group and let learners revisit them on their own schedule.
Static explainers can teach vocabulary. A stronger program shows how people question founders, read deal terms, write an investment memo, and revisit a decision after new evidence arrives.
Our co-founder Elizabeth Yin made that last point after reviewing her own 2014–2017 angel portfolio: “Like everything else, investing requires practice. And the only way to practice is if you have a feedback loop.” Her feedback loop was specifically post-investment. She advised working lightly with founders after a check to compare the original judgment with what happened inside the business. Workshops and deal reviews provide a different loop, letting newcomers state a view and hear informed disagreement before committing capital.
2. Communities made diligence less solitary
Early-stage diligence depends on many kinds of context. A product leader may spot an adoption problem. A doctor may see a clinical workflow issue. A finance operator may question cash assumptions. A community can put those views in the same room and distribute the work.
Communities can add a shared diligence process to networking. Angel groups have long used memos, committees, and syndication to pool knowledge. The Golden Seeds playbook, hosted by the Angel Capital Association, includes an agreement for sharing diligence while warning that neither side guarantees the information’s accuracy or completeness.
That caveat matters. Peer diligence gives you more questions and evidence. You still own the decision. If you want the mechanics of education, deal flow, and peer learning in more depth, our angel investing community guide covers them separately.
3. SPVs made some smaller checks practical
A special purpose vehicle (SPV) is a legal entity formed to make a specific investment. Instead of adding every participating investor directly to the startup’s capitalization table, the company can record one SPV while the vehicle tracks the investors behind it.
An early online example shows how pooling changed the practical minimum. In April 2013, contemporaneous reporting described AngelList and SecondMarket grouping accredited investors in one limited liability company. Individual commitments could be as low as $1,000, while the whole vehicle initially needed $150,000 and later $200,000. Aggregation made those small commitments workable without placing every investor directly on the startup’s capitalization table.
That historical example doesn’t establish a universal SPV minimum. The lead, platform, issuer allocation, administrative cost, and vehicle documents determine the minimum for a specific deal. An SPV can also add setup or administration fees, carried interest, reporting layers, and vehicle-specific rights. Those economics belong in the decision, not in the fine-print pile you promise yourself you will read later.
SPVs changed how a deal can be assembled. They didn’t erase offering rules. If the underlying offering is limited to accredited investors, joining the SPV doesn’t make a non-accredited investor eligible. Our explanation of groups, syndicates, and funds goes deeper on who chooses deals and how the structures differ.
4. Regulation Crowdfunding created a separate route
Regulation Crowdfunding, often shortened to Reg CF, allows eligible companies to offer securities online through an SEC-registered broker-dealer or funding portal. Anyone may invest in a Reg CF offering, although non-accredited investors face annual investment limits. An eligible issuer may raise up to $5 million in 12 months.
Reg CF is a distinct part of the private market. SEC staff identified 3,869 offerings that reported about $1.3 billion in proceeds from May 2016 through December 2024. The report calls that a likely lower bound because filing practices vary.
Reg CF widened legal participation for eligible offerings. It didn’t make private securities liquid or startups predictable. Securities bought through Reg CF are generally restricted from resale for one year, and the company may provide much less continuing information than a public company. Our guide to startup-investing access routes compares community, syndicate, and direct-access paths.
5. Geography became less important for learning and sourcing
Virtual workshops, video pitches, shared data rooms, and online investor discussions let people participate without living near a startup hub. Our own Angel Squad community includes more than 2,500 members across 50-plus countries. That reach shows how far education and relationships can travel.
Investment access remains more constrained than community access. A member in one country may be able to review a company and learn from the discussion while being unable to join that offering because of local rules, the issuer’s process, or the vehicle’s requirements.
In a 2025 retrospective on our community’s first four years, Elizabeth Yin described the original launch goal: “break down the barriers that have traditionally kept most people out of angel investing – education, check size, dealflow, and networks.” She was describing what we had set out to reduce. Offering eligibility and investment risk still apply.
Seven barriers still shape outcomes
A larger deal inbox can create false confidence. Every check still ties up capital in a company with a limited operating history and many ways to fail.
The barriers that remain are the ones most likely to affect your outcome:
- Selection risk: A polished pitch, respected lead, or lively community discussion can’t prove product demand, founder execution, or a future exit.
- Verification: Private-company disclosures are limited. You need a process for checking claims, references, ownership, financial information, market assumptions, and the actual security terms.
- Illiquidity and time: You may be unable to sell for years, even when the company appears to be doing well. There may never be a buyer or exit.
- Dilution and rights: Later financings can reduce your ownership. Share classes, preferences, pro rata rights, conversion terms, and the SPV’s own documents determine what you hold.
- Fees and carry: Administration expenses and carried interest can change the economics of a vehicle. Compare the gross company outcome with what the structure could leave for you after its terms apply.
- Allocation: Seeing a deal doesn’t guarantee that you can invest, receive your requested amount, or join a later round.
- Loss and concentration: Startups often fail, and a total loss is possible. Smaller checks help only if they support a portfolio plan rather than a string of unrelated impulses.
The SEC investor bulletin on Reg CF makes the risk concrete: early-stage investments are speculative, may have limited disclosure, can be hard to resell, and can result in the loss of your entire investment. Those are useful warnings for startup investing well beyond crowdfunding.
Judge the quality of access before you use it
The number of deals in an inbox is a weak measure of access. Useful access helps you form a view, understand the terms, and say no without pressure. Use these questions to evaluate a community, platform, syndicate, or other route:
- Does the education show real decisions? Look for live examples, investment memos, term explanations, and post-investment reviews. A vocabulary library alone won’t build judgment.
- Is there a feedback loop? You should be able to ask questions, state your thesis, hear informed disagreement, and learn what happened after the original decision.
- Where does deal flow come from? Understand who sources and screens companies, how incentives shape that filter, and whether you can review enough information to make your own choice.
- What does diligence include? Look for named owners, a repeatable process, clear open questions, founder references, and room for specialists to challenge the lead investor’s view.
- Are the economics visible before commitment? You should be able to identify the security, valuation or cap, fees, carried interest, expenses, allocation process, follow-on rights, reporting, and transfer limits.
- Are eligibility checks specific to each offering? A credible process distinguishes joining the community from qualifying for a deal. The SEC’s exempt-offering overview says Rule 506(c) sales are limited to accredited investors. Its crowdfunding guidance permits non-accredited participation subject to annual limits. The exemption, offering documents, and issuer or intermediary checks control. A community label doesn’t establish eligibility.
- Does the model support portfolio discipline? Decide your annual budget, target number of checks, maximum check size, sector exposure, and reserve policy before an exciting deal creates urgency.
Access is useful when it improves your process. More opportunities without clearer judgment, transparent terms, and a portfolio plan can increase risk faster than skill.
See whether the community fits your process
Take our free, interactive two-minute demo to see how workshops, deal reviews, and investor resources fit together. No signup is required.
Disclaimer: This content is for educational and informational purposes only. It is not investment, legal, or tax advice. Private investments are speculative, illiquid, long-term, and may result in total loss. Eligibility, fees, carry, tax treatment, rights, and transfer restrictions depend on governing documents and personal circumstances. Review the offering documents and consult qualified independent legal, tax, and financial professionals.











