
Founder Referrals for Deal Flow: An Investor Guide
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A founder you trust sends an introduction with one line. “You two should meet.” That message can carry useful context, but it can also tempt you to skip steps. Founder-referral deal flow works best when you understand what the referral signals, earn the trust behind it, and evaluate the company on its own merits.
What founder-referral deal flow means
Founder-referral deal flow is a startup opportunity introduced by a founder who knows the company, the investor, or both. The introduction usually includes a reason the match may work, such as sector knowledge, stage, geography, or a specific way the investor can help.
It differs from three nearby channels:
- An earned founder referral comes from a founder who has seen how you behave and chooses to put their reputation behind an introduction.
- A one-off warm introduction gives you a shared contact, although that contact may have limited knowledge of either side.
- Generic inbound arrives through an email, form, event, or public profile without a trusted connector.
Founder referrals also sit inside a broader deal-flow mix that includes other investors, communities, accelerators, content, events, and direct outreach. Treating one channel as the whole pipeline can leave you exposed to one network’s blind spots.
The National Bureau of Economic Research (NBER) paper How Do Venture Capitalists Make Decisions? is by Paul Gompers, Will Gornall, Steven N. Kaplan, and Ilya A. Strebulaev. Its survey covered 885 institutional venture capitalists.
Portfolio companies generated 8% of sourced opportunities. Professional networks, other investors, proactive sourcing, and inbound management contacts supplied the rest.
The sample covered institutional venture capitalists rather than angels, so the exact mix won’t map to every angel portfolio. It does show why a healthy pipeline usually has more than one source.
What a founder referral can tell you
A useful referral carries three kinds of information.
- Relationship signal. The referrer is willing to connect two people and be associated with the introduction.
- Fit signal. The referrer sees a match between the company and your thesis, experience, network, or temperament.
- Context signal. The referrer may know why the founder is raising, what the team does well, and why the conversation is timely.
Those signals can improve your first conversation. They do not prove that the startup fits your portfolio or that its claims are correct. They can also reproduce a network’s limits. If the same small circle supplies every opportunity, you may keep seeing similar founders, markets, and assumptions.
Hustle Fund general partner Elizabeth Yin writes in Democratizing Knowledge, “Investors use their life perspective to assess. For this reason, we need more funders with more varied life perspectives.” A wider mix of investors cannot remove every network bias. It can expose a referred company to questions and experience that one circle lacks.
Research on investor-to-investor referrals offers a useful parallel. Ron Rabi and Jeffrey S. Petty report in Deal referrals and fund strategy in venture-capital networks, a 2026 referral study, that referrals improved information about deals, yet did not reduce venture firms’ involvement in formal governance.
The finding does not prove the same effect for founder referrals. It supports one cautious rule. Use the context to sort the opportunity, then keep independent evaluation and oversight.
Earn referrals by being useful to founders
Founders refer investors whose behavior they are comfortable endorsing. Your website and thesis may make you discoverable. Your actions give a founder a reason to introduce you.
A check alone rarely makes an investor memorable. The founder remembers whether you understood the business, kept a confidence, gave a clear answer, or followed through when you offered help.
Use this five-part practice:
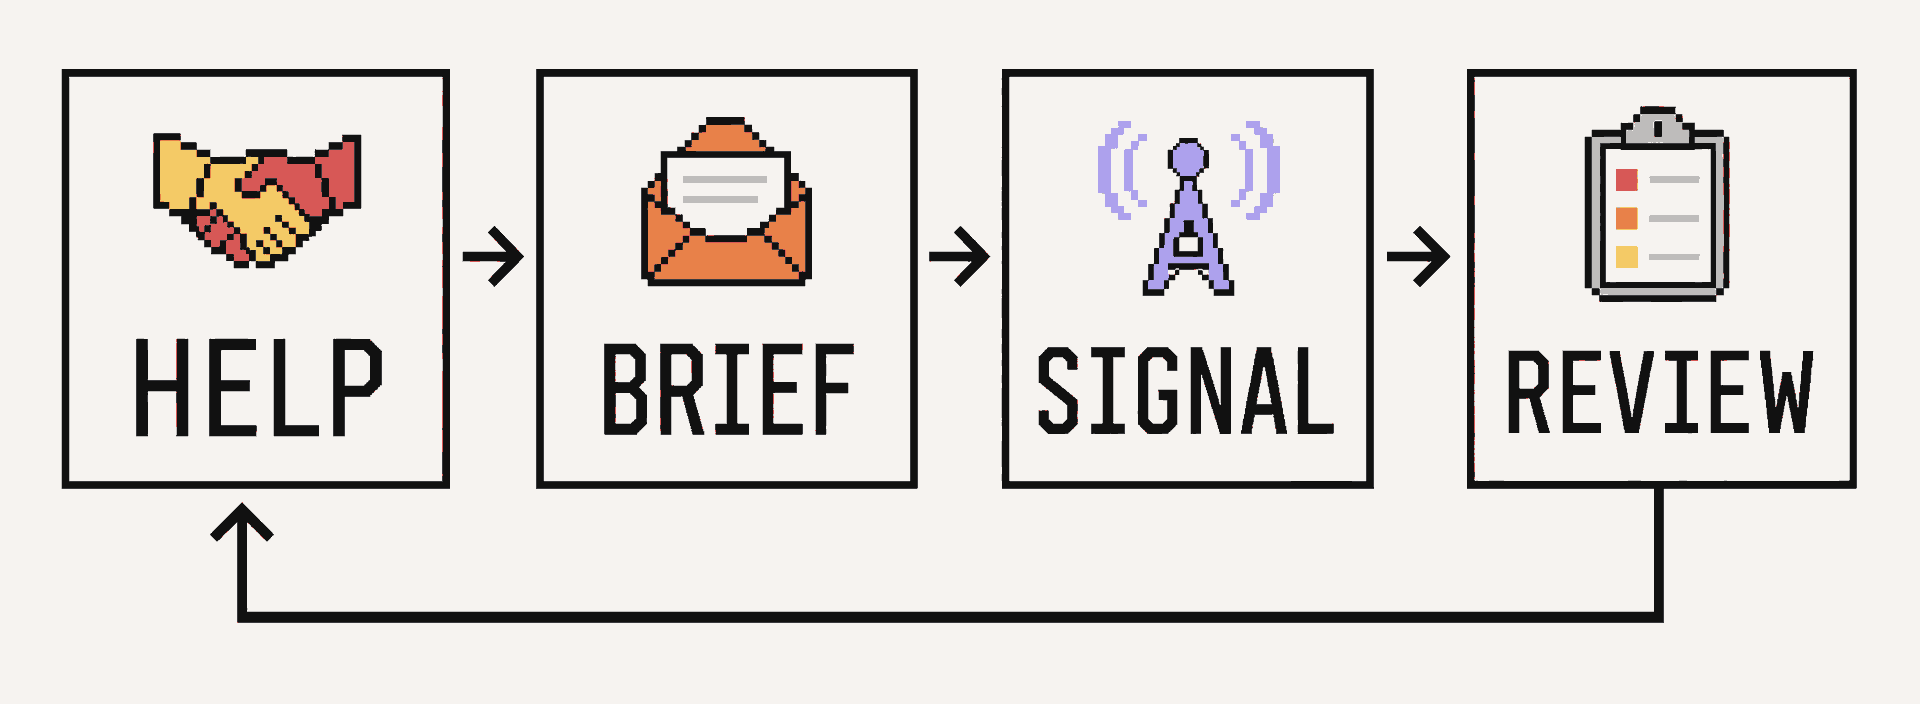
- Ask about a real priority. “Where are you stuck this month?” is more useful than a standing offer to help with anything.
- Offer one specific action. Review a pricing page, share relevant hiring context, make a customer introduction with both sides’ permission, or give focused feedback in an area you know.
- Make small promises. A promised introduction by Friday is better than five vague offers that disappear.
- Respond clearly. Give a timely yes, no, or date for your answer. A respectful pass is more helpful than silence.
- Stay useful after the check. Keep the same reliability after the financing closes. Trust comes from repeated behavior.
Let the founder define what help means. Unrequested advice can become another task. An introduction should require consent from both parties, and useful support never creates an obligation to send you deals.
Give your network a clear referral brief
People make relevant introductions when they can remember what you do. A focused thesis acts as a routing label for your network.
“I invest in software” is too broad to route well. “I look at pre-seed workflow software for independent healthcare practices, and I can help founders think through early distribution” gives the referrer a stage, customer, product type, and reason to connect you.
A usable referral brief contains four pieces:
- Stage: where you are prepared to invest.
- Problem or market: the area where you have a point of view.
- Evidence you want to see: customer learning, a product in use, unusual distribution, or another early signal that fits your process.
- Your useful edge: a skill, operating background, or network that is relevant to the founder.
Sector knowledge can make the brief sharper and help you contribute more during diligence. Geography can be useful when local customers, regulation, or a regional ecosystem matters. Neither needs to become a universal restriction.
Community participation can add perspectives outside your immediate circle. A well-run community should make its sourcing and review process clear so you can distinguish the source of an opportunity from the work done to evaluate it.
Make a referral request easy to decline
Your founders are building companies. They are not an extension of your sourcing team. Keep requests light, relevant, and permission-based.
A useful message sounds like this.
I’m spending more time with pre-seed tools for restaurant operators. If a founder asks you who they should meet and you think we’re a fit, I’d be glad to talk. No need to search on my behalf. Here’s a two-sentence description you can forward.
That request works because it is specific, situational, and easy to ignore. It also gives the founder a forwardable note, which removes the work of explaining your thesis.
Use a light cadence instead of a recurring referral quota:
- Share a short thesis update when your focus changes.
- Ask about impressive people when the topic comes up naturally in a portfolio conversation.
- Thank the referrer promptly and keep them out of confidential follow-up.
- Close the loop with a simple outcome, such as “we spoke” or “the fit wasn’t right for this round.”
- Record the source in your deal log so you can see which relationships produce relevant conversations without turning people into a leaderboard.
Never pressure a founder to vouch for someone they barely know. A clean introduction can state its limits directly. “I know both of you, but I have not evaluated the company.” That is still useful context.
Separate the referral from the investment decision
Warm context deserves a place in your notes. It does not deserve a free pass through your process.
Start by writing down what the referral adds:
- How does the referrer know the founder?
- What have they observed directly?
- Why do they believe the company fits your thesis?
- What would they want you to examine closely?
Then reset and evaluate the company as if the warm introduction were absent. Use the same criteria you apply to other opportunities. Review the team, market, product, customer evidence, competition, financing terms, references, and material risks. State what you know, what you infer, and what remains unanswered.
Run references beyond the introduction path when possible. A referrer may be accurate and still have only one view of the founder or market. Independent customer, former colleague, and domain references can reveal different evidence.
Elizabeth Yin gives the operating principle in Democratizing Knowledge, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” Apply the rubric consistently, record the reasons for your decision, and revisit those reasons as you learn. That practice improves judgment even when the eventual outcome takes years to appear.
Know the limits of referred deal flow
A referral can improve access and context. It cannot guarantee allocation, investment performance, or a return. Referred companies can fail, and a strong referrer can be wrong.
Early-stage startup investments are speculative, illiquid, and long-term. An investor can lose the full amount invested. Build a process that accounts for those risks and judge every opportunity within your own goals, expertise, and portfolio plan.
Practice the judgment behind the referral
The hard part is turning warm context into a disciplined decision. If you want to learn from Hustle Fund’s approach, review curated deal flow, and compare notes with peers, apply to Angel Squad.
This is general educational information, not investment advice. Consider your circumstances and seek advice from qualified independent professionals before making an investment decision.











