
ESG Due Diligence: An Angel Investor Checklist
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A founder says their startup treats workers well, protects customer data, or reduces waste. At pre-seed, there may be little evidence behind those claims. Environmental, social, and governance (ESG) due diligence helps you assess the risks through founder questions and operating records, without demanding a public-company reporting package.
What is ESG due diligence?
ESG due diligence is the assessment of a company’s environmental, social, and governance risks, practices, and claims before investing, with follow-up as the business changes. For an angel investor, it belongs alongside product, people, financial, and legal diligence.
The three categories give you a starting point:
- Environmental: Energy and resource use, emissions, waste, pollution, and environmental claims about the product.
- Social: Worker treatment, safety, customer welfare, privacy, accessibility, and effects on communities or people in the supply chain.
- Governance: Who makes decisions, controls spending, discloses conflicts, maintains ownership records, and responds when something goes wrong.
Look through two lenses. An issue can threaten the business, such as a customer-data incident that interrupts sales. It can also harm people or the environment, such as unsafe conditions at a supplier. Serious harm deserves attention even when the immediate cost to the startup is unclear.
We treat this as part of understanding how a company operates. A positive ESG review doesn't make a startup a safe investment. Most of the startups you back may fail, and you can lose your entire check despite careful diligence.
ESG review and impact investing have different purposes
Exclusionary screening uses defined ESG criteria to rule investments out. ESG integration means considering relevant environmental, social, and governance factors in the investment decision. Neither establishes that a company has produced a positive social or environmental outcome.
Impact investing adds an intention to generate measurable positive outcomes alongside a financial return, as the Global Impact Investing Network defines it. Investors can have different financial-return objectives; accepting lower returns isn't a defining requirement.
If impact is part of your thesis, name the intended change, who benefits, the starting baseline, the measurement method, and the timeframe. “We serve underserved customers” describes a market. Evidence that those customers are better off requires more work.
Run ESG due diligence in five steps
The output is a short record of relevant risks, supporting evidence, unresolved questions, and actions. Keep it with your investment memo. Our broader angel investing diligence checklist covers the other workstreams that an ESG review won't replace.
1. Map the startup's actual exposure
Start with what the company does today and what the next milestone changes. Map its product, customers, workforce, operating locations, suppliers, data, and public claims.
The priorities will differ by business:
- Software handling sensitive data: Start with data access, customer consent, security responsibilities, incident handling, and potentially harmful product uses.
- A physical-product startup: Start with materials, manufacturing partners, worker safety, waste handling, and the evidence behind environmental marketing.
- A lending business: Start with pricing transparency, collections, customer complaints, how decisions affect borrowers, and applicable regulatory obligations.
These examples are prompts. A software startup running energy-intensive infrastructure may also have substantial environmental exposure. A manufacturing startup can have customer-data risks.
The Sustainability Accounting Standards Board (SASB) Standards offer an industry-specific risk lens for sustainability issues likely to affect a company's financial prospects. Use relevant topics to inform your questions, then add or remove topics based on the actual business.
For adverse effects on people and the environment, the Organisation for Economic Co-operation and Development (OECD) recommends a risk-based approach that accounts for severity and likelihood in its due diligence guidance. A small company can still have a severe risk. Limited headcount changes how the work gets done, rather than removing the need to address it.
Prioritize the issues that could materially change your decision or cause serious harm. For lower-exposure topics, record why they're lower priority. A reporting framework doesn't establish which laws apply to a specific startup; company activities and jurisdictions need separate legal analysis.
2. Ask focused questions and request usable evidence
Use this ESG due diligence checklist selectively. A founder's answer should explain the current practice, its limits, and who owns it. Request records the startup already uses, with redacted or aggregated information where appropriate.
Environmental questions
- What creates the company's main environmental exposure? Ask about energy, materials, waste, pollution, and dependence on particular sites or suppliers. Relevant evidence may include utility records, material specifications, supplier agreements, or waste-handling records. Identify activities outsourced to someone else.
- What environmental benefit does the product claim? Ask what is being compared, which product or process is covered, and what is excluded. Request the underlying measurements, assumptions, and reports. A prototype result may support a narrow finding while leaving commercial-scale performance unresolved.
- How are environmental problems handled? Ask about incidents, complaints, relevant permits, and corrective actions. Request the records that exist and identify any missing information that needs specialist review.
Environmental marketing deserves its own attention. The Federal Trade Commission's Green Guides summary cautions against broad, unqualified claims such as “eco-friendly.” It also explains that third-party certification doesn't remove the need to substantiate the claims communicated. The Guides concern environmental marketing; they aren't an ESG score or a certification of the whole business.
Social questions
- How are workers treated in practice? Ask about pay arrangements, working hours, safety, complaints, and departures, including contractors and relevant supplier workers. Useful evidence may include redacted agreements, aggregate payroll information, safety records, or examples of how complaints were resolved.
- Who could be harmed by the product or its incentives? Ask about vulnerable users, fees, cancellation, misleading interfaces, discrimination, and foreseeable misuse. Request customer terms, complaint summaries, product flows, and records of changes made after a problem surfaced.
- What happens to customer and employee data? Ask what is collected, why, who can access it, how long it is kept, and who handles incidents. Request a data-flow explanation, access-control records, relevant vendor arrangements, and incident documentation where available. Have a qualified specialist assess material technical or legal gaps.
A concerning employee review or customer complaint is a lead to investigate. Record the allegation, context, and company response separately. Avoid treating one uncorroborated account as a finding, or a founder's denial as a resolution.
Governance questions
- Who can spend money and approve important decisions? Ask how payments, major commitments, and exceptions are authorized. Request the current approval process, accounting records relevant to the concern, and examples of actual decisions. In a tiny team, a founder may own several responsibilities; the control still needs a clear explanation.
- Are ownership and obligations understood? Request the current capitalization table, which records company ownership, along with financing documents and relevant intellectual-property agreements covering company code, inventions, and branding. Material inconsistencies belong with qualified startup counsel. Custom documents or cross-border entities need an explanation and appropriate review; their existence alone isn't evidence of misconduct.
- What conflicts, disputes, or incidents should an investor know about? Ask about transactions with founders or other connected parties, founder disagreements, complaints, and past corrections. Request supporting records and a specific account of what changed. Compare material facts across documents and founder conversations.
For people-related concerns, our management due diligence process adds structured founder conversations and references. Arrange sensitive employee or customer contact with consent, and keep confidential material within the agreed diligence group.
3. Separate statements from evidence
A policy records what a company says it intends to do. An operating record can show what happened. Independent corroboration adds another perspective, but only within the scope of what that person or document can establish.
Label each important claim by its current support:
- Founder statement: Explained in conversation or a pitch, with no supporting record yet.
- Documented: Supported by relevant operating records or data, with the period and scope identified.
- Independently corroborated: Supported by a relevant third party, such as a customer, former colleague, specialist, or laboratory.
- Unresolved: Material information is missing, contradictory, or outside your ability to assess.
An independent report about one supplier doesn't cover every supplier. A certification may cover a specific product, location, or period. Record those boundaries rather than giving the startup an overall “good ESG” label.
“No data yet” establishes an unknown. Decide whether that unknown is tolerable at this stage or needs resolution before you invest. A pre-product company may have no customer-incident history; it can still explain its design choices, foreseeable harms, and response plan.
4. Decide what the findings change
Write a short risk note for every priority issue. Include the issue, who could be affected, the business consequence, the evidence and its date, the remaining uncertainty, and the action. Give the action an owner and a deadline or milestone.
Our co-founder Elizabeth Yin writes that “The best startup investors are constantly re-evaluating their approach and thesis.” A written note makes that practice concrete. You can revisit the evidence and identify what changed your judgment.
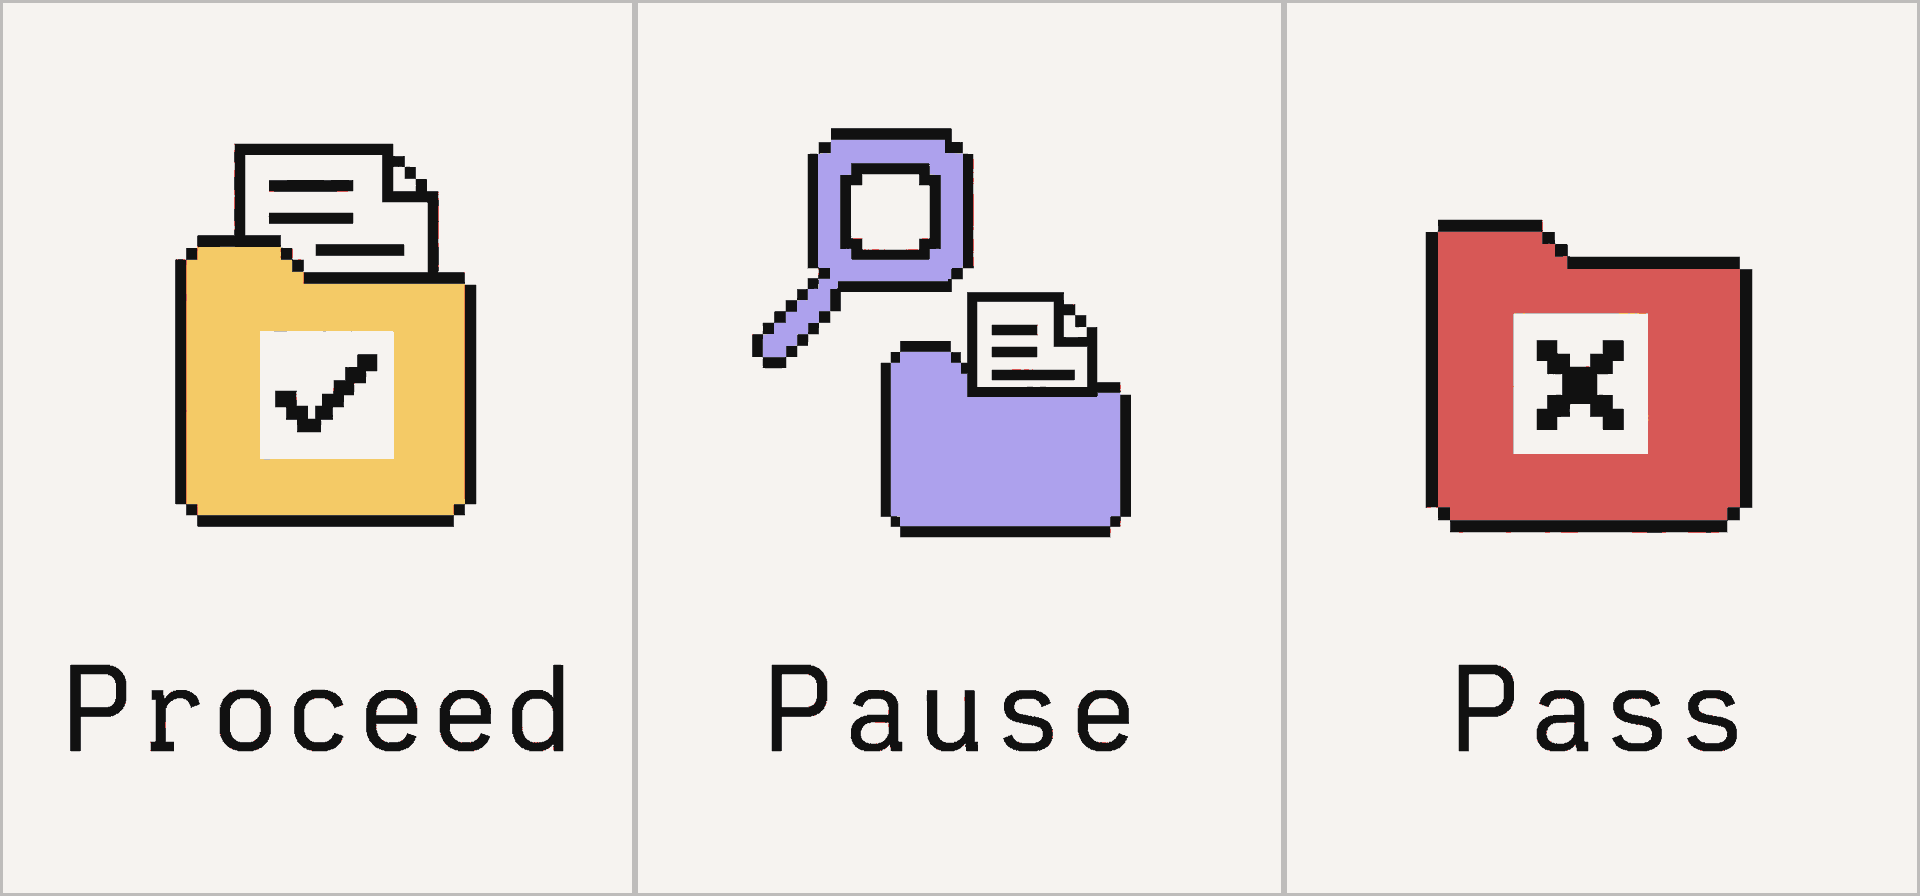
Use three possible decisions:
- Proceed: The relevant evidence supports your investment case, and you accept the remaining risks. Any ongoing actions have an accountable owner and realistic timing.
- Pause: A material unknown, conflicting record, or unresolved harm needs more evidence, corrective work, or expert review before you commit.
- Pass: The risk falls outside your criteria, serious misconduct is substantiated, or the company refuses a reasonable path to addressing a material concern.
Distinguish an immature process from an integrity problem. A missing formal policy can be a manageable gap. Fabricated records, concealed conflicts, or repeated contradictions in material facts require a different response. An imminent round close doesn't resolve them.
A founder who names a limitation, supplies records, and takes responsibility provides useful evidence of how they work. A reassuring pitch or a certification alone leaves the underlying question open. Avoid averaging a serious unresolved issue into a comfortable overall score.
5. Agree on proportionate follow-up
Before investing, establish what updates you'll receive and how material incidents will be communicated. Your influence and access depend on your role and the investment documents. A small angel check doesn't give you the oversight powers of a board member.
Keep follow-up focused on the risks you identified. That might mean a product-safety milestone, a supplier correction, or progress on access controls. Add a new topic when the company enters a new market, handles more sensitive data, or changes its operating model.
Our co-founder Eric Bahn says, “So, for us, hustle is defined as great execution meets high velocity.” Apply that founder-assessment lens to follow-through: what did the team commit to, what did it do, and what changed after it learned more?
Inside Angel Squad, our investing education, deal context, and peer community help you practice forming questions and discussing investment reasoning. Peer discussion can surface a missing question; material technical and legal issues still need qualified specialists.
A worked example: the claim is broader than the evidence
Consider a hypothetical pre-seed packaging startup that describes its product as “eco-friendly” and says it reduces waste. The founders share a laboratory report on one material and results from a small customer pilot.
The report covers material behavior under specified conditions. The pilot records packages returned by participating customers. Neither, on its own, establishes the product's overall environmental benefit or what happens across the intended customer base.
A useful diligence note could read:
- Issue: Environmental benefit claims exceed the current evidence.
- Evidence: A laboratory report for one material, plus return records from a limited pilot. The report's date, test conditions, and pilot period are recorded in the memo.
- Unknown: Full-package performance, disposal routes in intended markets, and whether customers outside the pilot return packaging.
- Decision: Pause if the unsupported benefit is central to your investment thesis or the company won't address the claim.
- Action: The product lead owns the evidence plan before the next commercial launch. Qualified counsel assesses marketing claims, and a relevant technical specialist assesses the performance evidence.
A narrower claim and a credible evidence plan may change your judgment. They still leave commercial execution and other investment risks to assess. The founder's willingness to correct the claim is useful behavior; it doesn't prove future impact or financial success.
To practice this kind of judgment with curated startup opportunities and fellow investors, apply to Angel Squad.
This material is educational and isn't investment, legal, or tax advice. Seek independent review from qualified legal and tax professionals for company-specific obligations and transaction questions. Startup investments are speculative, illiquid, and can result in a total loss.











