
Cross-Border Angel Investing: A Practical Deal Checklist
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
An investor in California gets an allocation in a startup selling software in Mexico. The term sheet looks familiar, the founders are impressive, and the round closes Friday. The investor still cannot name the legal entity they will actually own.
Cross-border angel investing adds a second layer of execution to normal startup diligence. Use this sequence to identify the issuer, screen the jurisdictions involved, inspect the documents, plan the wire and tax work, and preserve the right records after close.
1. Map what counts as a cross-border startup deal
A startup can feel local in a pitch and become international once you map its legal entities, operations, investors, and money flows. Most early-stage cross-border deals fall into one of three structures.
A foreign operating company with a U.S. parent
The team and customers may sit outside the United States while a Delaware corporation owns the operating subsidiary. The investor usually buys a security issued by the U.S. parent. The foreign subsidiary still creates local legal, tax, labor, banking, and currency exposure.
Confirm that the parent owns the subsidiary and the intellectual property the founders say it owns. Then match the investment documents to the parent’s exact legal name.
A direct investment in a foreign issuer
The investor buys shares, a convertible instrument, or another security directly from a company formed outside the United States. The foreign company is the issuer, and the investor or nominee appears in its ownership records according to local practice.
A foreign company offering securities into the United States still needs a registered offering or an available exemption under U.S. securities law. The issuer’s home country can impose its own offering, ownership, filing, and transfer rules.
An investment through an SPV, including a syndicate that uses one
A special purpose vehicle (SPV) pools investors into one entity. The SPV buys the startup security, and the angel receives an interest issued by the SPV. The startup’s cap table may show one vehicle rather than every backer.
Some syndicates use an SPV, while others let participants invest directly in the startup. A syndicate describes how a lead coordinates a deal. It does not, by itself, identify the entity or security an investor owns.
An SPV can reduce administrative work for the startup, though it adds a manager, vehicle documents, fees, and a separate reporting layer. Our SPV explainer shows how the ownership chain works.
If the opportunity came through a syndicate, first determine whether you are a direct participant or an SPV subscriber. Then complete the matching sentence:
Direct investment: I am investing [amount and currency] in [startup issuer], formed in [jurisdiction], and will receive [startup security] issued by that company.
SPV investment: I am subscribing [amount and currency] to [vehicle issuer], formed in [jurisdiction], for [vehicle interest]. That SPV will hold [startup security] issued by [startup issuer], formed in [jurisdiction].
If the deal team cannot complete the right sentence, pause. Every later review depends on it.
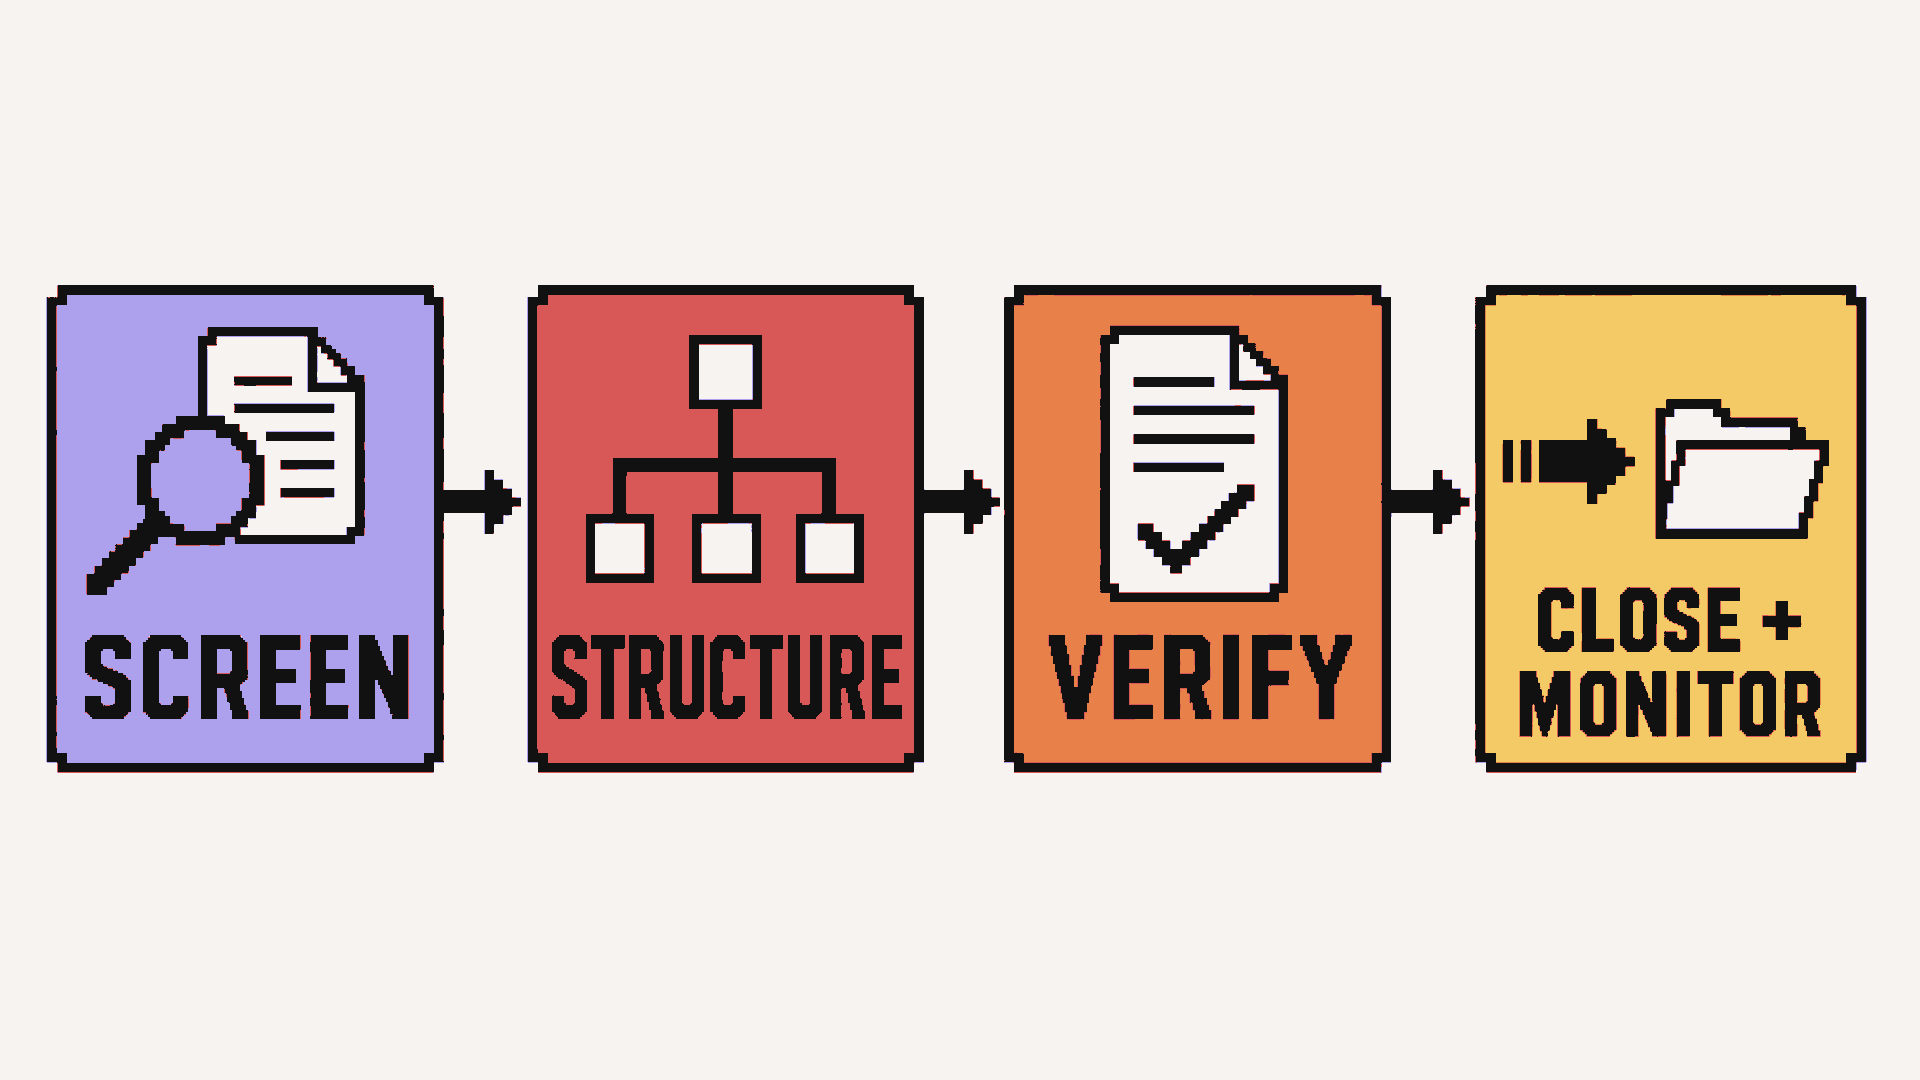
A disciplined deal moves through four stages: screen, structure, verify, then close and monitor.
2. Run a fast screen before deep diligence
A fast screen is a stop gate. It should reveal whether the opportunity is eligible for you, whether the transaction path makes sense, and which advisers need to be involved.
Investor eligibility and offering path
Ask the issuer or lead which securities-law exemption the round relies on and what investor eligibility it requires. In the United States, private rounds often use Regulation D. Rule 506(b) and Rule 506(c) have different rules for solicitation, purchaser eligibility, and verification. The SEC’s exempt-offering overview explains those paths.
Confirm where you reside, where the issuer and any SPV are formed, where the offer was made, and where the founders and main operations sit. That map helps securities counsel identify every relevant jurisdiction.
Sanctions, ownership, and outbound-investment rules
The U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) requires U.S. persons to comply with its sanctions regulations wherever they are located. Screen the issuer, subsidiaries, founders, major owners, directors, banks, and intermediaries. Under OFAC’s 50 Percent Rule, an entity is considered blocked when one or more blocked persons own 50% or more of it, individually or in the aggregate, directly or indirectly, even when the entity’s name is absent from the main list.
Also ask whether the destination country limits foreign ownership or requires approvals in the company’s sector. Defense, financial services, telecommunications, media, transportation, and regulated infrastructure often deserve an early local-law check.
Some U.S. investments tied to China, Hong Kong, or Macau and involving advanced semiconductors, quantum information technologies, or certain artificial intelligence systems can trigger the Treasury Department’s outbound-investment program. Give specialist counsel the underlying company facts for this screen.
Adviser plan
Identify independent U.S. securities counsel, qualified counsel in the issuer’s home market, and a cross-border tax adviser before the deadline compresses the review. A vehicle manager’s counsel represents the manager or transaction, depending on the engagement. It does not automatically represent each investor.
Stop if the issuer refuses to identify the offering path, cannot produce an entity chart, asks for funds to an unrelated account, or treats sanctions and ownership restrictions as paperwork to solve after the wire.
3. Decide whether you are investing directly or through a vehicle
The direct-versus-vehicle choice changes what you own, what you pay, what information you receive, and who controls decisions after the investment.
With a direct investment:
- You receive and hold the startup security yourself.
- Your name or nominee may appear in the startup issuer’s ownership records.
- You receive documents and distributions from the company or its paying agent.
- You handle your own tax records and any investor actions.
A direct syndicate participant follows this path even when a lead coordinates the allocation. The syndicate lead does not become a vehicle issuer unless a separate entity sits in the ownership chain.
With an SPV, including a syndicate that uses one:
- You receive an interest issued by the vehicle.
- The vehicle holds the startup security and appears on the startup’s cap table.
- The manager may control voting, consents, follow-on decisions, transfers, and distributions.
- Management fees, carried interest, expenses, and vehicle-level tax reporting can affect your outcome.
Request two diagrams: the company entity chart and the investment ownership chain. Then ask four blunt questions:
- Which exact startup entity issues the underlying startup security?
- Which exact entity issues what I receive? In a direct deal, it is the startup issuer. In an SPV deal, the vehicle issuer creates a separate vehicle interest.
- Whose name appears on the startup’s cap table, and who controls votes, waivers, amendments, and exit approvals?
- What fees and expenses can be charged now or later?
The words “direct,” “nominee,” “feeder,” “SPV,” and “syndicate” sometimes get used loosely. The signed documents and ownership records control.
4. Diligence the company in its local context
Normal startup diligence still applies. Review the founders, market, product, traction, economics, cap table, financing terms, and use of funds. Our full due diligence checklist covers that core work.
Cross-border diligence adds a local-context test. Evidence that looks familiar in one market can mean something different in another.
- Customers: Speak with customers in the company’s main market. Confirm who signed, who pays, the billing currency, renewal behavior, and whether a founder relationship drove the sale.
- Competition: Ask local operators which alternatives buyers actually consider. A U.S. competitor grid can miss regional incumbents, distributors, informal substitutes, and procurement habits.
- Founder references: Seek references from former colleagues, investors, customers, and employees in the founders’ operating market. Check names and work histories in the original language where relevant.
- Intellectual property: Trace code, patents, trademarks, domains, and contractor work to the investing entity or its subsidiary. Review invention-assignment agreements under the law that governed the work.
- Financial claims: Reconcile the deck to bank statements, invoices, contracts, tax filings, and management accounts. Note which currency and accounting standard each figure uses.
- Use of funds: Identify which entity receives the investment, which entity employs the team, and how cash moves between parent and subsidiaries.
- Governance: Review the board, reserved matters, local directors, shareholder approvals, related-party transactions, and the process for resolving disputes.
Local perspective is part of the evidence, especially when the investor and founders have different reference points. Our co-founder Elizabeth Yin puts the broader case plainly: “For this reason, we need more funders with more varied life perspectives.”
Invite those perspectives into the diligence process. Seek a local angel or operator through international investing communities when you need market context. They can challenge assumptions without replacing independent verification.
5. Read the rights and restrictions before you wire
A familiar instrument name does not guarantee familiar economics. A simple agreement for future equity (SAFE), convertible note, or preferred share issued under foreign law can differ from the version an investor has seen in a U.S. deal.
Review the complete document set, including the signed or execution-ready versions of:
- The security purchase, subscription, SAFE, note, or share agreement
- The startup issuer’s charter, bylaws, shareholder agreement, and current cap table
- Any SPV issuer’s operating agreement, subscription agreement, private placement memorandum, and manager disclosure
- Side letters that change information, follow-on, most-favored-nation, fee, or transfer rights
- Board and shareholder approvals authorizing the round
Focus on the provisions that determine your actual position:
- Startup security and issuer: legal name, jurisdiction, class, price, valuation cap, discount, interest, maturity, and conversion mechanics
- Vehicle interest and issuer: for an SPV, the vehicle’s legal name, jurisdiction, interest issued to you, and subscription mechanics
- Ownership: fully diluted capitalization, option pool, outstanding convertibles, senior securities, and the entity recorded as holder
- Information rights: what you receive, how often, in what language and currency, and whether the rights sit with you or the SPV manager
- Transfers: resale restrictions, rights of first refusal, company or manager consent, lockups, and permitted transfers to trusts or affiliates
- Governance: voting thresholds, manager authority, drag-along terms, protective provisions, and amendment mechanics
- Exit: who can approve a sale, how proceeds move from the startup through a vehicle, and which fees or taxes can be withheld
- Disputes: governing law, court or arbitration forum, service of process, language, and enforceability where assets and people are located
The SEC warns that private placements can involve limited disclosure, indefinite holding periods, restricted securities, and loss of the entire investment. Treat enforcement as a practical question too. A contractual right has less value when exercising it across borders would be slow or uneconomic.
6. Trace every currency and funds-transfer step
Cross-border deals can expose an investor to three different currencies:
- Subscription currency: the currency you wire.
- Operating currency: the currency in which the startup earns revenue and pays costs.
- Exit or distribution currency: the currency in which proceeds may eventually reach you.
A U.S.-dollar subscription does not remove currency exposure when the company earns and spends in another currency. Exchange-rate moves can change runway, margins, valuation comparisons, and the dollar value of future proceeds.
Before wiring, document:
- The beneficiary’s legal name, bank, country, account currency, and relationship to the issuer or vehicle
- Conversion spreads, transfer fees, intermediary-bank deductions, and who bears them
- The amount that must arrive for the subscription to be complete
- Any local capital controls, central-bank filings, or limits on moving money into or out of the country
- Potential withholding taxes on dividends, interest, sale proceeds, or vehicle distributions
- How the company expects to move cash between parent and subsidiaries
- How future distributions will be converted and remitted
Currency controls can restrict or delay moving funds, and a foreign market can limit an investor’s legal remedies. The SEC summarizes these issues in its international-investing guidance.
Confirm wire instructions through a trusted channel using previously verified contact details. Keep the instructions, transfer confirmation, exchange-rate record, and proof that the issuer or vehicle received the funds.
7. Flag U.S. tax and reporting questions early
U.S. citizens and resident aliens generally report worldwide income. Cross-border startup holdings can add information returns before they produce cash.
Give your cross-border tax adviser the entity chart, investment documents, ownership percentage, transfer amount, dates, tax classification of any vehicle, and financial statements. Ask which of these topics applies:
- Foreign tax credit: A credit may be available when foreign income tax and U.S. tax apply to the same income, subject to detailed limits. The IRS explains the basic foreign tax credit framework.
- Form 8938: Certain U.S. taxpayers report specified foreign financial assets above thresholds that vary by filing status and residence. Foreign stock and interests in foreign entities can count. See the IRS Form 8938 summary.
- Report of Foreign Bank and Financial Accounts (FBAR): A U.S. person may need to report financial interests in or signature authority over foreign financial accounts when aggregate value exceeds $10,000 at any time during the year. This filing is separate from Form 8938. A foreign company share certificate is different from a foreign bank account, though a vehicle or related account can change the analysis. See the FBAR rules.
- Form 5471: Certain U.S. officers, directors, and shareholders of foreign corporations have reporting duties based on ownership and control categories. The Form 5471 instructions define them.
- Form 8621 and PFIC status: A passive foreign investment company, or PFIC, is a foreign corporation that meets statutory income or asset tests. Direct and indirect U.S. shareholders can face annual reporting and special tax rules. Review the Form 8621 instructions.
- Form 926: Certain transfers of property or cash to a foreign corporation can require reporting. Ownership after the transfer and aggregate cash transferred during a 12-month period matter. The IRS lists the Form 926 triggers.
- Qualified small business stock: Foreign company stock does not automatically qualify for the qualified small business stock exclusion. Section 1202 starts with stock in a domestic C corporation and imposes other requirements.
Entity classification and indirect ownership can change the answer. Get the analysis while records and advisers are accessible, then calendar every filing and document request.
8. Work through a hypothetical deal before committing
Hypothetical example: A U.S. angel is offered a $25,000 allocation in a software company whose team, customers, and operations are mainly in Mexico. A Delaware corporation owns the Mexican operating subsidiary. A Delaware SPV will invest in the parent, and the angel will subscribe to the SPV in U.S. dollars.
The investor maps the ownership first:
- The Delaware SPV is the vehicle issuer, and the angel owns an interest issued by it.
- The SPV holds the startup security.
- The Delaware parent is the startup issuer and appears in the financing documents.
- The Mexican subsidiary employs the local team and serves customers.
The fast screen confirms the U.S. offering path, investor eligibility, sanctions review, foreign-ownership rules, and adviser responsibilities. Diligence then checks that the Delaware parent owns the Mexican subsidiary and relevant intellectual property, and that reported customer revenue reconciles to contracts and bank records.
Document review covers the SPV’s fees and manager authority, the startup security, information flow, transfer restrictions, conversion terms, governing law, and exit approvals. The wire goes to the SPV account named in the subscription agreement after an independent confirmation of the instructions.
The investor also records the three-currency picture: a U.S.-dollar subscription, Mexican-peso operating exposure, and an uncertain future distribution currency. A tax adviser reviews the SPV’s classification and the investor’s reporting position. This sequence identifies questions and owners for each answer. It does not determine that the deal is suitable or resolve the legal and tax analysis.
Keep the check size in the context of a portfolio. As our co-founder Elizabeth Yin says, “Don't try to pick a co. Select a portfolio.”
Diversification cannot eliminate startup risk, currency exposure, or jurisdiction risk. It can reduce the damage one failed company does to the overall angel portfolio.
9. Build the post-close file before the round closes
Closing is the start of the holding period. Save a complete, searchable record while everyone is responsive.
Keep:
- Final signed investment and vehicle documents
- Wire instructions, transfer confirmations, receipts, and exchange-rate records
- The entity chart, cap table, approvals, and security certificate or ledger entry
- Tax forms, adviser memos, withholding statements, and annual vehicle reports
- Contact details for the issuer, vehicle manager, counsel, tax adviser, and paying agent
- A log of information-rights deadlines, annual filings, conversion events, and follow-on rights
At least annually, update the entity chart, jurisdiction map, cap table, sanctions screen, valuation support, and tax classification. Track whether the company moves intellectual property, changes its parent, creates new subsidiaries, opens a new financing vehicle, or shifts its main market. Each change can affect documents, reporting, and the path to future proceeds.
When a follow-on round arrives, repeat the screen. A previous approval does not cover a new issuer, vehicle, jurisdiction, or security.
Cross-border angel investing pre-wire checklist
Use this list as a final stop gate:
- Ownership: I can name the startup-security issuer and, for an SPV investment, the vehicle-interest issuer, plus what each entity issues and my place in the ownership chain.
- Entity maps: I have the company entity chart and investment ownership chain.
- Offering path: The issuer or lead identified the offering exemption and investor eligibility rules.
- Legal review: U.S. and local counsel covered the relevant jurisdictions, ownership limits, and approvals.
- Sanctions: The issuer, founders, major owners, subsidiaries, vehicle, manager, and banks passed applicable sanctions screening.
- Outbound investment: Any U.S. outbound-investment issue received specialist review.
- Local diligence: Customer, competition, founder-reference, intellectual-property, financial, and governance diligence is complete.
- Final documents: The documents match the entity, security, economics, rights, restrictions, governing law, and dispute forum I reviewed.
- Vehicle economics: I understand every fee, expense, carried-interest term, and manager power.
- Currencies: The subscription, operating, and potential distribution currencies are documented.
- Wire: Bank instructions were confirmed independently, and I understand conversion and transfer costs.
- Funds movement: Capital controls, withholding, and repatriation mechanics were reviewed.
- Tax: A cross-border tax adviser reviewed the likely U.S. and local filing questions.
- Position size: My check fits a portfolio that can withstand a total loss and a long, illiquid holding period.
- Records: My post-close file and reporting calendar are ready.
Build this review habit with curated deal flow and experienced peers when you apply to Angel Squad.
This material is for education only. It is not legal, tax, accounting, financial, or investment advice, and it is not an offer or recommendation to buy or sell any security. Startup and private-placement investments are speculative, illiquid, long-term, and can result in total loss. Before any cross-border investment, seek advice from your own independent U.S. securities counsel, qualified counsel in each relevant foreign jurisdiction, and a cross-border tax adviser.











