
Chris Dixon Investments: Thesis and Lessons
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Lists of Chris Dixon investments often mix his personal angel checks, Founder Collective activity, and investments made by Andreessen Horowitz funds. That blur makes the list look more complete than the public record supports.
A more useful approach is to study Dixon’s stated thesis, examine a few investments tied to his documented involvement, and separate the evidence from our interpretation. That gives angel investors a repeatable process without pretending that someone else’s portfolio is a blueprint.
Who is Chris Dixon?
Chris Dixon is the founder and managing partner of a16z crypto, where he leads the firm’s crypto and blockchain investing, according to his official a16z crypto bio. Before a16z, he co-founded the startups SiteAdvisor and Hunch, co-founded the seed fund Founder Collective, and made personal angel investments. Those career details come from Dixon’s a16z author profile and establish why searches for his investments span several different roles.
Even the start date needs care. Andreessen Horowitz announced Dixon’s hire as a general partner in November 2012, according to the contemporary announcement. The firm’s general bio says he has been at a16z since 2012, while its crypto bio says 2013. The safest reconciliation is that his hire was announced in 2012 and his tenure began around the 2012–2013 transition.
This distinction matters. A company announcement can document Dixon’s board role or his authorship of an investment case. It does not automatically establish that he invested personal capital, led a round, or made every decision attributed to his firm.
The Read/Write/Own thesis in plain English
Dixon divides the internet’s development into three design eras. In his own summary, the first democratized information, or “read.” The second democratized publishing, or “write.” The third aims to democratize ownership, or “own.” He argues that software and network design choices determine who controls a digital service and who participates in its economics. That is Dixon’s stated thesis, laid out in his Read Write Own announcement.
The “own” stage centers on blockchain networks. Dixon believes these networks can give users and developers stronger property and participation rights than a service controlled by one company. His longer Read Write Own manifesto contrasts open internet protocols with corporate networks that can change access, fees, and distribution rules.
The thesis becomes an investment filter through four questions:
- Control: Who can change the network’s rules?
- Ownership: What can users, creators, or developers keep and move?
- Participation: Can outside builders add products without asking one gatekeeper?
- Incentives: Does the network reward the people who contribute to its growth?
These questions do not prove that a startup will work. They turn a broad view of technology into claims an investor can test.
Three documented investment examples
The examples below are a small, deliberately limited set. Each has a primary source that connects Dixon to the company through a board role, advisory work, or authorship of the investment case. They are a16z investments. We do not treat them as verified personal checks or as a complete portfolio.
Coinbase, 2013
In December 2013, Coinbase announced an a16z-led funding round and said Dixon would join its board. The company’s announcement documents both the date and his role.
The factual record is narrow: a16z invested and Dixon took a board seat. Our interpretation is that Coinbase fit the thesis because it gave users an entry point to blockchain-based assets. The announcement alone does not show every reason for the investment or isolate Dixon’s decision from the firm’s process.
Dapper Labs, 2021
In March 2021, a16z announced further financing for Dapper Labs. The post, co-authored by Dixon and David George, says the firm had first invested more than three years earlier while Dapper was working on CryptoKitties. The authors focused on digital ownership, third-party development, and the Flow blockchain in their Dapper Labs investment case.
Here the connection to Read/Write/Own is explicit in the source. Users could hold and trade digital items, while developers could build related experiences. The source documents Dixon’s authorship of the follow-on case. It does not say he personally led every Dapper investment.
OpenSea, from 2021
OpenSea co-founder Devin Finzer says he met Dixon in 2021 when a16z first expressed interest in investing. Finzer also says Dixon became a regular adviser and later took over the firm’s board seat. That OpenSea account documents sustained involvement beyond a name on a portfolio page.
Our interpretation is that a marketplace for user-held digital assets matched the ownership thesis. The source supports Dixon’s advisory and board roles. It does not establish that he led the original investment.
What these examples can and cannot tell you
The examples show consistency between a public thesis and several disclosed company relationships. They cannot establish the quality of the entire portfolio or prove that the thesis caused any company outcome.
Four limits matter:
- Public records are incomplete. A16z says its published investment list may omit investments when the issuer has not given the firm permission to disclose them publicly. The firm explains that limit in its investment disclosures.
- Firm and individual decisions overlap. A board seat or authored announcement documents involvement. It rarely reveals how an investment committee divided the work.
- Selection creates bias. Publicly discussed examples are easier to study than quiet or undisclosed investments. A few recognizable names cannot represent every decision.
- Outcomes arrive late. Early-stage companies can take years to mature. A mark, headline, or fundraising round is not cash returned to investors.
Missing good deals is part of the job. Elizabeth Yin, Hustle Fund co-founder and general partner, puts it plainly: “You accept that you will miss some.” A thesis improves consistency, but it does not remove uncertainty, luck, or the need for portfolio discipline.
Startup investments are speculative, illiquid, and long term. Many fail, and any single check can go to zero. A compelling thesis should make your reasoning clearer. It should never make the risk feel smaller than it is.
A practical thesis process for angel investors
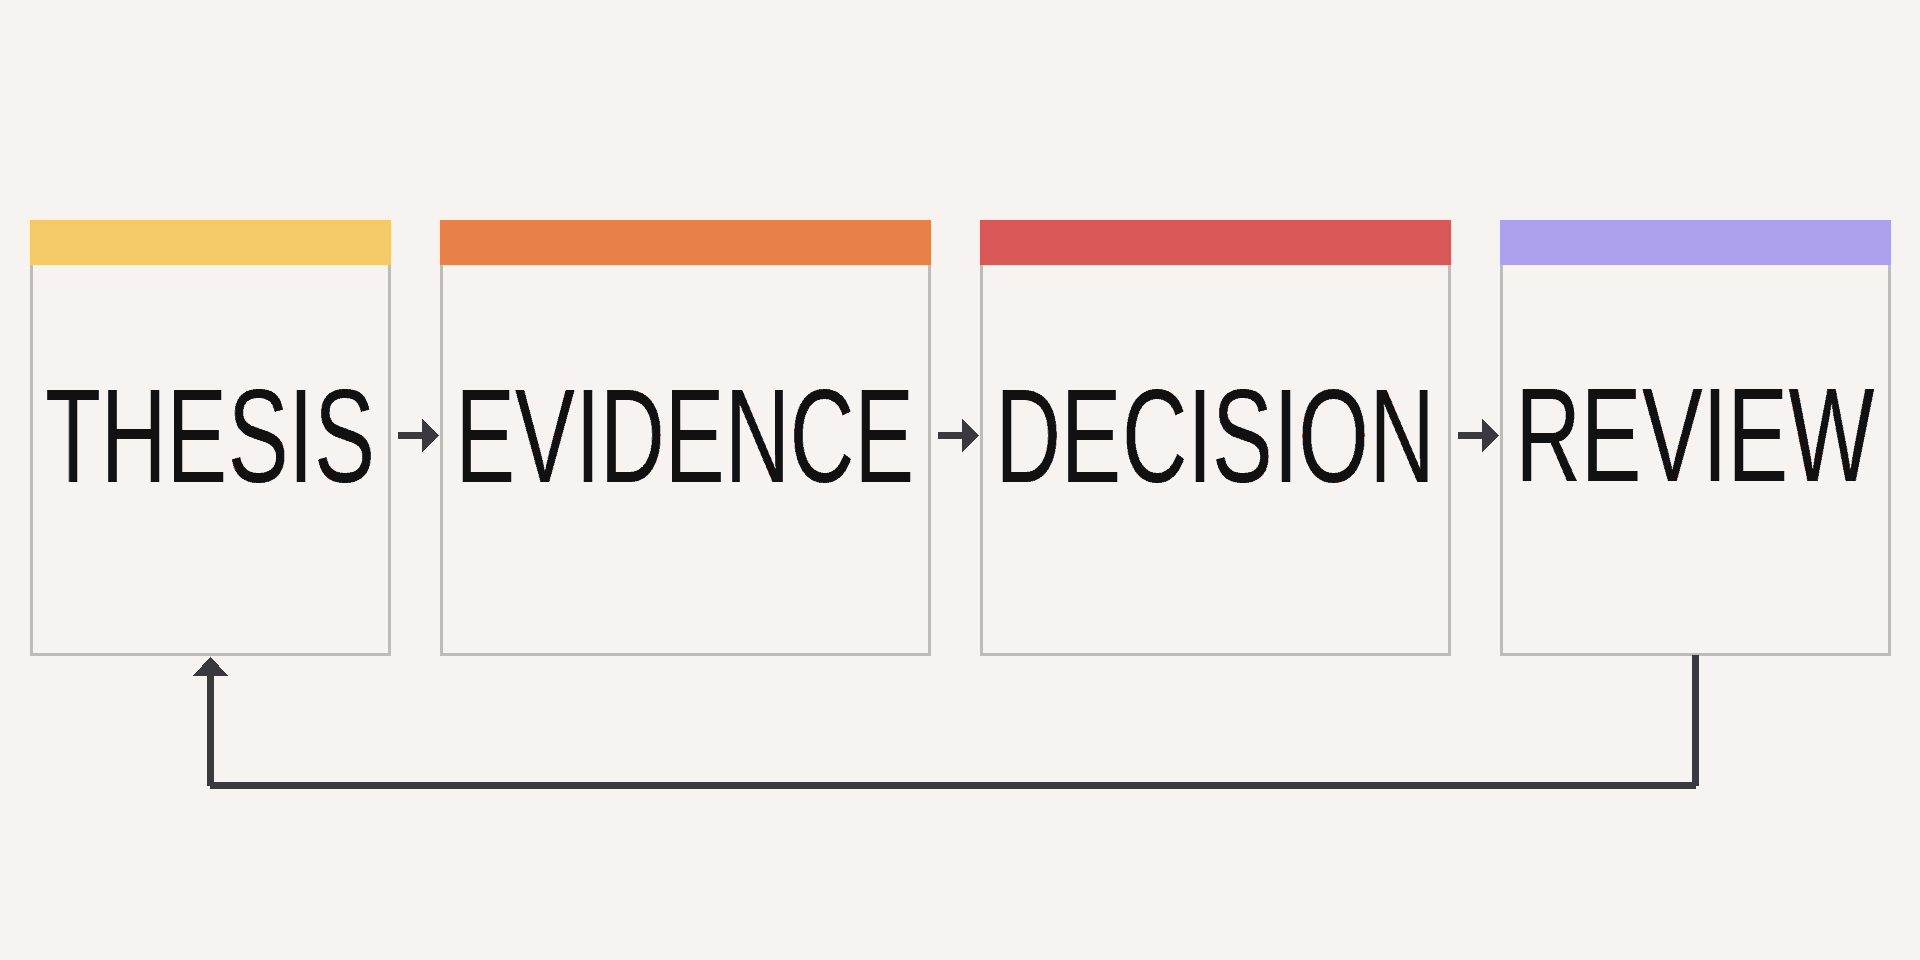
You can borrow Dixon’s method without borrowing his sector view. The useful behavior is writing a claim, turning it into observable tests, recording a decision, and reviewing what the evidence later showed.
1. Write one claim that could be wrong
Start with a sentence tied to your experience. For example: “Independent dental practices will adopt software that saves front-desk staff at least five hours a week.”
Then write what would disprove it. If buyers will not change workflows, cannot measure time saved, or refuse the likely price, the thesis needs revision.
2. Turn the claim into deal questions
Use the same short questions for every company in the category:
- Who feels the problem often enough to act?
- What behavior proves the product is useful?
- Which distribution channel can reach buyers?
- What advantage improves as the company grows?
- Which fact would make us pass?
This is where a thesis becomes usable. Hustle Fund co-founder and general partner Eric Bahn defines hustle as “great execution meets high velocity.” The value is in the next step: he looks for observable signs such as exceptional productivity, rapid learning, and focus on metrics.
3. Label fact, interpretation, and unknown
For each deal, keep three separate notes:
- Fact: a number, customer statement, product behavior, or document you can trace to a source.
- Interpretation: what you think that fact means.
- Unknown: the question the current evidence cannot answer.
This simple separation prevents a persuasive founder story from quietly turning into “proof.” In Angel Squad, peer discussion is useful because another investor can challenge the interpretation while the underlying fact stays fixed.
4. Record the decision before the outcome
Write a one-page memo with the thesis fit, strongest evidence, main risk, open questions, and reason for investing or passing. Date it. Later, review whether the original claim was sound or whether luck, timing, and new information changed the result.
Do this for passes too. A disciplined pass log shows which filters save time and which cause you to miss companies you would have wanted to back.
5. Set portfolio boundaries first
Decide your total startup-investing budget, check size range, number of planned investments, and follow-on policy before a deal creates urgency. Only commit capital you can afford to lose and leave unavailable for a long period.
The thesis chooses which opportunities deserve more work. Portfolio construction limits how much any one judgment can hurt you.
Your thesis improves when other investors can challenge it
A written thesis gets better through repeated deal review, dissent, and honest post-decision notes. If you want to practice this process on curated startup opportunities with other aspiring and active angels, apply to Angel Squad.
This content is for educational purposes only and is not investment advice. Startup investments are speculative, illiquid, long term, and may result in total loss.











