
How First-Time Founders Build Investor Credibility
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
First-time founders often enter a raise without a famous employer, a prior exit, or investors on speed dial. You can still give an angel a sound reason to take the meeting. The work starts before outreach, with specific evidence that you understand the problem, can earn customer commitment, and follow through on what you say.
What credibility means to a pre-seed investor
Credibility is the fit between your claims and the evidence behind them. An investor should be able to trace each important statement in your pitch to an observation, action, result, or informed reference.
At pre-seed, that evidence will be incomplete. A randomized field experiment published in The Journal of Finance found that the average early-stage investor responded strongly to information about the founding team, while information about traction or an existing lead investor did not produce the same average response. The lesson is narrower than “traction does not matter.” Early numbers need a team story that explains why the numbers exist and what the founders learned from them.
Different investors will also read the same evidence differently. Our general partner Elizabeth Yin writes in Democratizing Knowledge, “Investors use their life perspective to assess.” Your job is to present accurate evidence to investors who understand the customer, market, or problem. You cannot make every investor interpret it the same way.
A useful credibility unit has four parts:
- Claim: What you believe or have accomplished.
- Proof: What you observed, built, sold, or measured.
- Limit: What the evidence does not establish yet.
- Next milestone: What you will learn or prove with the capital.
Build your investor evidence stack
First-time founders do not need every form of proof at once. Use the strongest evidence your stage allows, then state its limits. Five sources tend to matter in a pre-seed conversation.
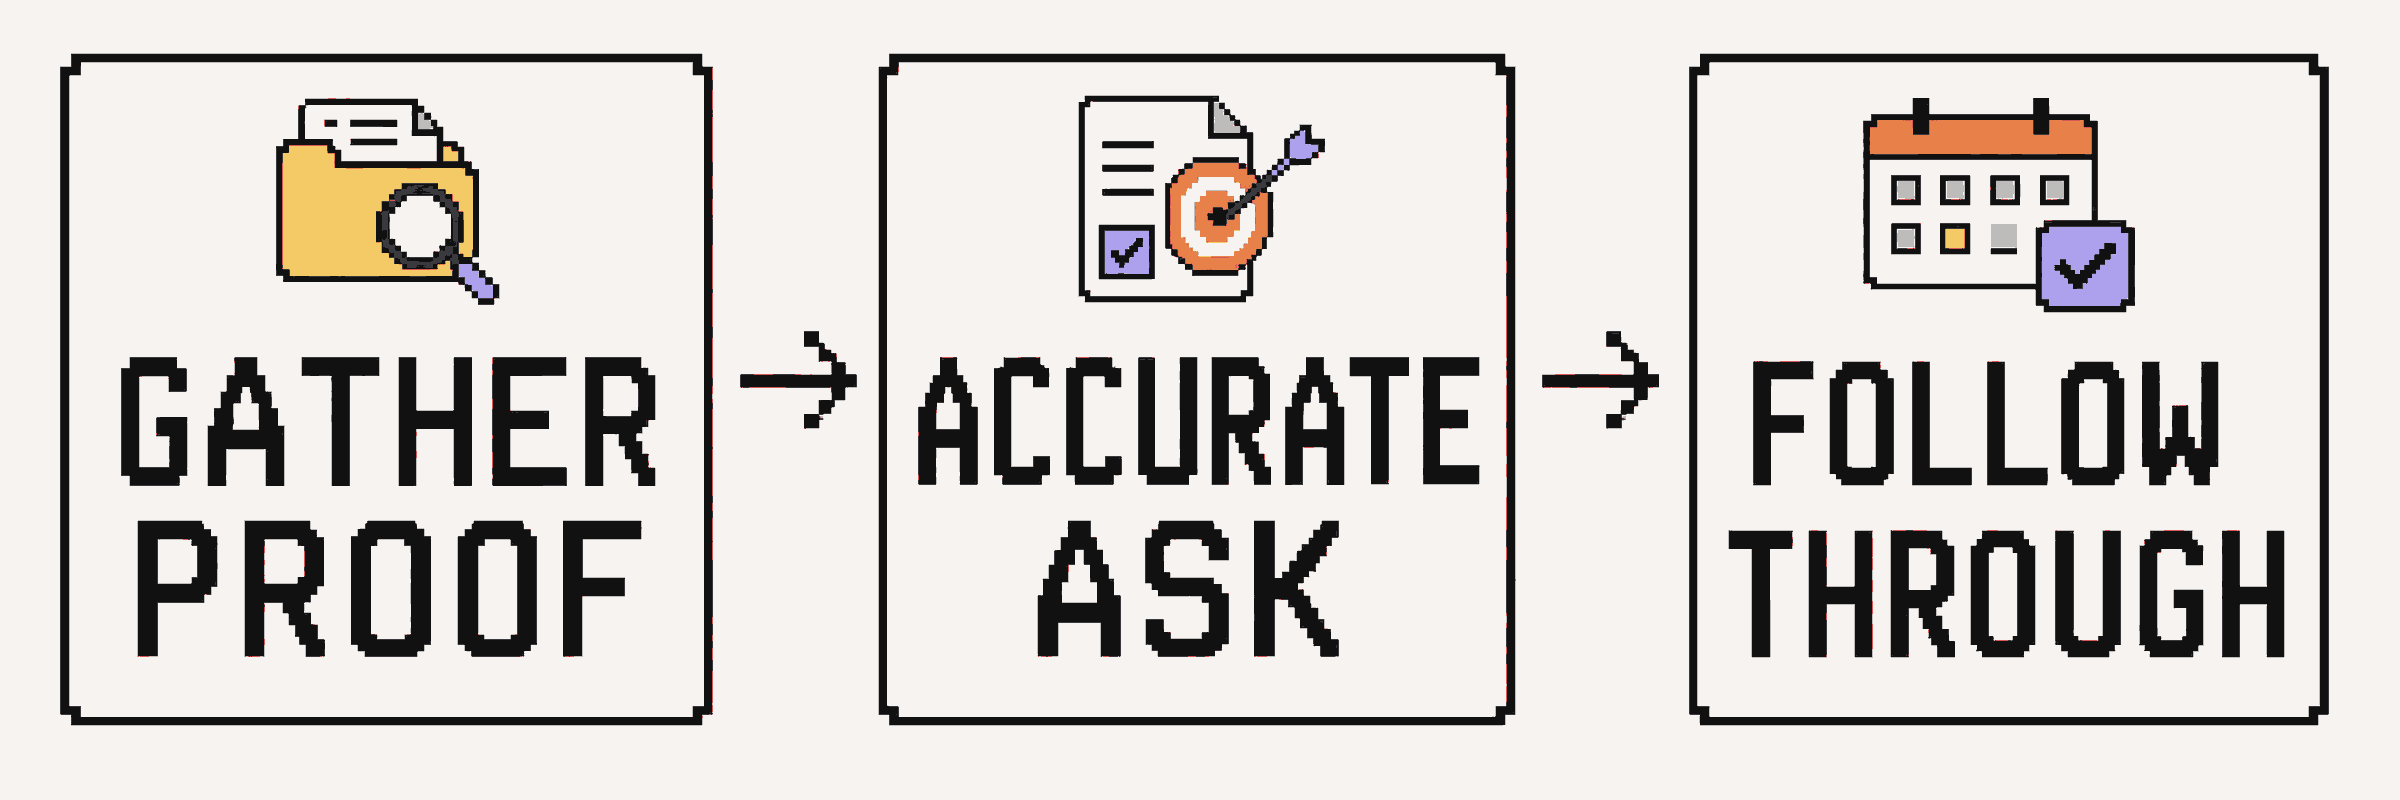
Those five sources feed a simple path from gathered proof to an accurate ask and then consistent follow-through. Your domain edge can strengthen the insight behind that proof.
1. Show firsthand problem knowledge
Generic market statistics rarely prove that you understand a customer. Bring the details you learned through interviews, observation, or your own work in the industry.
Useful evidence includes repeated descriptions of the same painful workflow, examples of how customers solve the problem today, and the cost of leaving it unsolved. Keep interview notes and record how your thesis changed. A founder who can explain which assumption was wrong sounds more credible than one who claims every conversation confirmed the original idea.
Imagine a founder building scheduling software for home-care agencies. “Scheduling is inefficient” is a broad claim. A stronger version explains that coordinators at the agencies interviewed rebuild the schedule after every same-day cancellation, shows the current spreadsheet workflow, and names the next assumption the prototype will test.
2. Turn customer interest into commitment
Compliments are weak proof. Commitment costs the customer time, money, data, access, or reputation.
For a pre-revenue company, that could mean a design partner who attends recurring product sessions, a pilot with a named start date, or users who return without being chased. Revenue is useful when it exists, but one payment does not prove retention or a repeatable sales process. For pitch purposes, present a typical unsigned or non-binding letter of intent as evidence of interest and label its status, rather than calling it booked revenue. A waitlist is evidence of sign-ups, not product use.
Document the exact commitment and ask permission before naming a customer. If you are still finding those first commitments, our guide to landing early customers goes deeper on narrow targeting and direct outreach.
3. Prove that you can build and learn
Execution evidence shows the loop between insight and action. Bring the prototype, the shipped feature, the test result, or the decision you made after users behaved differently than expected.
Avoid a feature tour. Pick one customer problem, show how the product handles it, and explain what the latest version taught you. A rough working flow can carry more weight than polished mockups if a real user has tried it. Founders who need help planning that conversation can use our guide to product demos for investors.
4. Make your domain edge concrete
Domain expertise is useful when it changes what you can see or do. Ten years in an industry is biography. Knowing why buyers reject the obvious solution, having access to a hard-to-reach user group, or understanding a regulated workflow is an edge.
Explain the connection in two sentences:
- Experience: The customer, system, or technical problem you know firsthand.
- Consequence: The insight, access, or execution advantage that experience gives this company.
A prestigious logo without the consequence is still a logo. An unconventional background with a sharp consequence can be far more relevant.
5. Earn a referral with firsthand basis
A warm introduction transfers a small amount of the referrer’s trust to you. It works when the referrer can explain how they know you and why the investor should care.
Build that basis before asking. Share a product, customer insight, or short progress update with people who know your work. Ask for feedback. When someone offers to help, give them a two-sentence forwardable note with the company, the proof point, and the reason this investor fits.
Do not ask a near-stranger to vouch for you, and do not collect introductions to investors whose focus does not match your company. Our playbook for an initial investor network explains how to map relevant relationships without pretending you already have insider access.
Turn your evidence into a credible pitch
Evidence becomes persuasive when an investor can inspect it quickly. Use one clear thread from problem to proof to next milestone.
Consider this illustrative pre-seed pitch:
Independent clinic administrators told us that prior-authorization follow-up takes hours each week. We reviewed 18 workflows, six administrators shared their current process, and three now use our prototype weekly. One clinic has signed a paid pilot that starts next month. We have only tested independent clinics, so the next milestone is learning whether the workflow holds across five organizations before we expand the product.
The numbers are hypothetical, but the structure is practical. The claim is specific. Each number has a denominator or status. “Signed pilot” is separated from current usage. The founder names the narrow sample and the next test.
Use the same standard across your deck:
- Label status precisely. Separate a conversation, verbal yes, signed agreement, active pilot, and paying customer.
- Add time and context. “Thirty percent growth” needs a period, starting value, and metric definition.
- Show the source. Keep interview notes, product logs, contracts, and calculations organized for follow-up.
- Explain the change. Tell investors what you learned and what you did because of it.
- Name the gap. State what remains uncertain before an investor has to drag it out of you.
- Make one ask. End outreach with a clear request for a meeting, introduction, or feedback.
Avoid credibility shortcuts
Social proof can support your case, but borrowed prestige cannot replace company evidence. These shortcuts tend to create more questions than confidence:
- Displaying customer logos without permission or a clear relationship.
- Calling an advisor “active” when they have attended one meeting.
- Describing unsigned interest as a partnership or committed revenue.
- Reporting downloads, waitlist names, or press mentions as customer traction.
- Showing a percentage without the starting number, period, or cohort.
- Claiming that a round is almost full when soft interest is the only support.
- Dodging a hard question instead of saying what you do not know.
Calibrated confidence is a strength at this stage. As Elizabeth Yin writes, “it's near impossible to tell at the early stages who is going to knock it out of the park.” Your evidence should support a reasoned bet. It cannot remove early-stage risk, and thoughtful angels can still pass.
Use follow-through to compound trust
An investor will remember whether you did what you said between conversations. If you promise a metric definition, customer reference, or revised forecast on Friday, send it on Friday. If the result changed, send the changed result with an explanation.
A short follow-up can cover three things:
- The material you promised.
- The progress or setback since the meeting.
- The next dated milestone.
This pattern should continue after the raise, when regular, candid communication becomes part of building investor trust. During fundraising, it also gives an undecided investor fresh evidence of how you operate.
Audit your deck before you send it
Open your deck and mark every substantive claim with proof, limit, and next milestone. Add the missing support, qualify the statement, or cut it. Then ask one person who knows the customer to challenge the evidence before the first investor sees it.











