
Bridge Round: A Due Diligence Guide for Investors
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
This content is educational and does not constitute investment, legal, tax, accounting, or valuation advice. Startup investments are speculative, illiquid, long-term, and carry a risk of total loss. All examples are hypothetical and simplified, and past results or current marks do not guarantee future results. Outcomes depend on the governing documents, fees, carry, taxes, cap table, valuation policy, and timing. Review the governing documents and seek advice from qualified, independent legal, tax, accounting, investment, and valuation professionals.
A portfolio company asks you for another check. The email calls it an “extension,” gives you two weeks to decide, and says a larger round is just one milestone away. Is that a smart bridge round or expensive borrowed time?
That answer lives in the gap between the company’s cash plan and its next fundable milestone. Here’s how to find it.
What is a bridge round?
A bridge round is interim startup financing raised after one funding round and before a planned larger round, exit, or business milestone. Its job is to extend the company’s runway, the time before it runs out of cash.
Founders may also call it an extension round, interim round, seed extension, or Series A extension. The label describes timing and purpose. It does not tell you the security, price, size, or health of the company. A bridge can use a Simple Agreement for Future Equity (SAFE), convertible note, preferred equity, or an add-on to an earlier round.
Bridge rounds have become a meaningful part of startup financing. In Q2 2025, 16.6% of the venture capital raised by startups on Carta came through bridge rounds, up from 11.8% one year earlier. The share reached 22.5% among Series A companies, while the median interval between primary funding rounds across stages stretched to 696 days, according to Carta’s private-market data.
Those figures explain why the word “bridge” is no longer an automatic distress signal. They do not make every bridge attractive. Investors still need to ask what sits on the other side.
Why startups raise bridge rounds
Most bridge rounds fit into one of three buckets. A single deal can contain elements of all three.
- Milestone bridge. The company needs more time and capital to launch a product, prove retention, reach a revenue target, secure regulatory clearance, or complete another concrete milestone that could support the next round.
- Market bridge. The business is progressing, but the financing or exit market has slowed. The company extends its runway rather than running a rushed priced round with weak leverage.
- Rescue bridge. Growth missed plan, costs ran high, or a prior strategy failed. The new capital keeps the company operating while management attempts a turnaround.
“Rescue” does not make a round uninvestable, and “milestone” does not make it safe. The real distinction is whether the capital funds a credible change in the company’s risk. A bridge that buys a measurable result can create new evidence. A bridge that only buys calendar time leaves the central problem untouched.
Start with the bridge math
Ask the founder to tie the amount raised to a dated operating plan. At minimum, the plan should show:
- cash available now;
- monthly net burn and the assumptions behind it;
- one-time costs required to reach the milestone;
- the month the milestone should be achieved;
- the time needed to prepare, run, and close the next financing; and
- a downside case for slower revenue, higher costs, or a delayed fundraise.
A simple starting equation is:
Bridge need = one-time milestone costs + monthly net burn × (months to milestone + months to close the next financing + contingency months) − current cash.
Hypothetical, simplified company-level bridge-budget example as of September 12, 2026: A startup has $450,000 of cash and burns $150,000 per month, giving it three months of runway. It raises $1.5 million and spends $100,000 on one-time product and closing costs. It would then have $1.85 million, or about 12.3 months of runway at a constant burn. If the next financing could take four months to close, the bridge plan should reach its milestone near month eight rather than month twelve. This illustration assumes an immediate close, flat net burn, no financing fees, no taxes, no working-capital swings, and no change in revenue.
That final buffer matters. A company that reaches its milestone with only a few weeks of cash remaining may have proof, but no negotiating room.
Monthly burn can also hide lumpy annual contracts, overdue payables, debt service, severance, inventory purchases, or hiring plans. Reconcile the headline figure to the company’s bank balance and cash forecast. Our guide to startup burn rate goes deeper on that review.
Ten due diligence questions for a bridge round
Bridge-round diligence starts with the original plan. You are underwriting what the company learned and what this new tranche of capital can change.
- What did the company plan to achieve with the last round? Compare the prior deck, budget, and investor updates with the current result.
- Why did the plan miss or the timeline move? Separate an external shock from a forecasting error, an execution problem, or weak demand. Then ask what management changed.
- What exact milestone will the bridge fund? “Get ready for Series A” is too vague. A product launch, retention threshold, signed contract, gross-margin target, or regulatory event can be tested.
- Will that milestone matter to the next investor? Ask which prospective leads have said the milestone would change their view. A founder’s internal target may have little value in a financing decision.
- Is the milestone achievable with the proposed cash and time? Check the hiring schedule, sales cycle, product dependencies, and downside case. Hope is not a line item.
- How much of the round is committed? Distinguish signed documents and received cash from verbal interest. A partially funded plan may never reach the milestone it was designed around.
- Which current investors are participating, and why? Insider support can signal conviction. An investor may also sit out because of reserve limits, ownership strategy, conflicts, or fund timing. Ask for the reason instead of treating participation as a verdict.
- What does the fully diluted cap table look like after conversion? Include every SAFE, note, warrant, option, promised grant, and proposed pool increase. Model the full bridge and the next priced round.
- What happens if the next round never arrives? Look for a credible path to lower burn, profitability, a sale, another financing source, or an orderly wind-down. “We will raise again” is not a downside plan.
- Why is this the best use of your next check? Compare the follow-on with new deals and with the reserves you need for the rest of your portfolio.
Our co-founder Elizabeth Yin puts the process plainly in Democratizing Knowledge: “The more disciplined you are in your thought process/rubric, the more you can improve over time.” Write down your answers before urgency and insider pressure rewrite the story for you.
The financing instrument changes the risk
A bridge round is a purpose, not a security. Read the actual documents and the cap table before comparing the headline valuation cap or price.
SAFE
A SAFE generally gives the investor a contractual right to receive equity when a specified event occurs. Review the valuation cap, discount, most favored nation (MFN) clause, pro rata side letter, conversion triggers, dissolution treatment, and change-of-control treatment.
Post-money SAFE caps can stack quickly. Under Y Combinator’s SAFE framework, ownership sold under each post-money cap is additive. Existing SAFEs, the bridge, a future option-pool increase, and the next priced round can all dilute the investor’s eventual stake.
Do not assume every document works like the YC form. The SEC’s crowdfunding-focused SAFE bulletin warns that conversion triggers and other provisions vary, and a SAFE may never convert if its trigger never occurs.
Convertible note
A convertible note is debt that may convert into equity. Review the interest rate, maturity date, valuation cap or discount, qualified-financing threshold, repayment terms, security or collateral, seniority, default provisions, and amendment rights.
Maturity deserves special attention in a bridge. If the next round slips, the note may reach maturity while the startup lacks cash to repay it. The documents determine whether investors can extend, convert, demand repayment, or exercise other remedies. For a fuller breakdown, read our guide to convertible note terms.
Priced preferred equity
A priced bridge issues shares now. It can extend an earlier preferred-stock round on the same terms or create a new price and rights. Review the pre-money and post-money valuation, liquidation preference, participation rights, anti-dilution protection, voting and consent rights, board rights, information rights, and any option-pool increase.
Immediate ownership is easier to see, but the preference stack may become less friendly to common shareholders and earlier investors. Map proceeds under several plausible exit values instead of stopping at the share price.
Read the signals without overreacting
No single sign settles a bridge-round decision. Look for a pattern.
Constructive signals include:
- management identified the miss before cash became an emergency;
- performance has improved even though it trails the original timeline;
- the bridge funds a specific, costed milestone;
- insiders are participating for reasons they can explain;
- founders reduced burn or changed the plan after new evidence; and
- the downside case leaves room for action.
Signals that need more work include:
- a solid business facing a genuinely slower financing market;
- mixed insider participation;
- a rolling close that could leave the operating plan underfunded;
- a milestone that depends on one customer, hire, regulator, or partner; and
- terms that changed late in the process.
Red flags include:
- repeated bridge rounds with the same unfinished milestone;
- no reconciliation between the last plan and actual performance;
- a round size chosen before the cash plan was built;
- missing cap-table instruments or undisclosed liabilities;
- refusal to explain why major insiders declined;
- a next-round story that requires heroic growth assumptions; and
- pressure to wire before investors receive final documents.
An attractive cap does not repair weak evidence. It only changes the price at which you accept the risk.
Decide as if this were a new investment
Your first check is already spent. The follow-on decision concerns the next dollar.
- Rebuild the investment case using current evidence.
- Name the milestone the bridge can achieve and the risk that milestone removes.
- Model the security alongside every existing SAFE, note, share class, and future financing assumption.
- Compare the expected risk and upside with your best available new investment.
- Size the check within a reserve and portfolio-construction policy you set before the deadline arrived.
As Elizabeth Yin writes in Democratizing Knowledge, “Decisions are never in isolation - they are a comparison game.” Pro rata rights give you an option to invest. They do not turn the option into an obligation. Our pro rata guide explains how to evaluate that choice.
This is also where peer review helps. Inside Angel Squad, our angel-investing community, members learn Hustle Fund’s evaluation frameworks and compare how other investors approach real startup decisions before making their own calls.
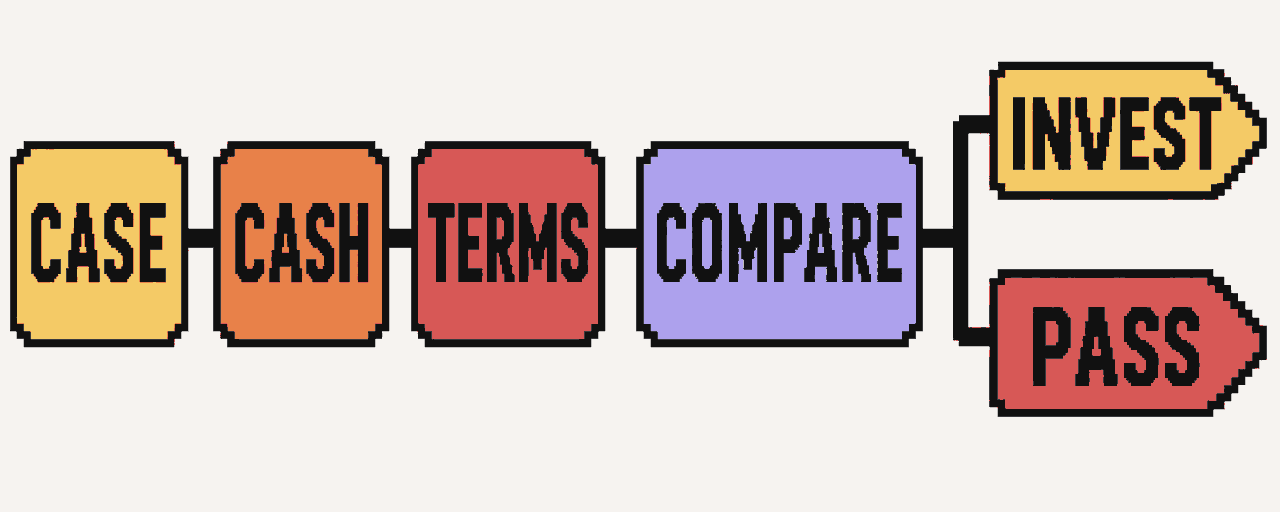
Bridge round FAQ
Is a bridge round always a bad sign?
No. A bridge can fund a strong company through a longer financing cycle or help it reach a valuable milestone. It can also keep a weak company alive without fixing its core problem. The company’s progress, cash plan, terms, and use of proceeds matter more than the label.
Is a bridge round the same as a down round?
No. A down round is priced below the company’s previous round. A bridge describes interim financing. A bridge can preserve the prior price, use an unpriced SAFE or note, or close at a lower valuation.
Does a bridge round dilute existing investors?
Usually, yes. Priced shares dilute ownership when issued. SAFEs and convertible notes generally dilute investors when they convert. The amount depends on the documents, cap table, financing size, conversion terms, option-pool changes, and later rounds.
How long should a bridge round last?
There is no universal number. The bridge should fund the target milestone and leave enough time to prepare, market, negotiate, and close the next round under a downside case. Counting only the months until the milestone understates the capital need.
A good bridge gives a company enough room to create new evidence. A good investor still checks the math, reads the documents, and compares the opportunity. If you want to build those investing reps with experienced peers, apply to Angel Squad.











