
Anti-Dilution Provisions: A Down-Round Guide for Angels
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A startup raises money at a lower share price, and the financing terms affect how much of the company you own. For an angel investor, understanding anti-dilution starts with the security you hold. The conversion mechanics, a worked example, and the limits of each right make the tradeoffs clearer.
What anti-dilution provisions protect
Price-based anti-dilution provisions adjust the conversion price of protected preferred stock when a company issues covered securities at a lower price. Preferred stock is a share class with rights specified in the company’s governing documents, including how it converts into common stock, the ordinary share class generally held by founders and employees.
A lower conversion price means each protected preferred share can convert into more common shares. The adjustment does not automatically issue more preferred shares, preserve your ownership percentage, or guarantee the value of your investment. Cooley explains this distinction in its down-round financing guide.
Three different changes can happen around a financing:
- Ownership dilution: New shares increase the total share count, so an existing holder’s percentage can fall. This can happen in an up round or a down round.
- Lower financing price: New investors buy shares at a lower price than investors paid in an earlier financing. This is a down round.
- Anti-dilution adjustment: A covered issuance below the protected stock’s current conversion price triggers the adjustment specified in its documents, unless an exclusion or waiver applies.
Headline valuations alone don’t establish the adjustment. A financing’s price per share depends on the capitalization used to price the round, including rights to buy stock and instruments that may convert into shares. A fall from a $10 million valuation to $5 million does not, by itself, mean your investment is now worth exactly half as much.
The conversion ratio is the original issue price divided by the current conversion price. If both are $1.00, one preferred share converts into one common share. If the conversion price falls to $0.50, that same preferred share converts into two common shares.
A capitalization table, or cap table, records the company’s ownership. An “as-converted” cap table counts preferred stock as the common shares it could convert into. That is the share count affected by the adjustment.
Full ratchet vs. weighted-average anti-dilution
Full ratchet resets the conversion price to the lower covered issuance price. Weighted average adjusts it using both the price and the size of the issuance. A financing can also have no price-based anti-dilution protection, while retaining separate adjustments for stock splits, which proportionally change share counts.
Full ratchet
Under full ratchet, protected preferred stock with a $1.00 conversion price can reset to $0.50 if covered shares are issued at $0.50. The adjustment does not weight the size of the new financing. A small covered issuance can therefore produce a large conversion-price change. Cooley’s full-ratchet explanation describes that price-only approach.
The additional common-share equivalents change the ownership denominator for everyone. Founders, employees with equity, and unprotected investors can bear more dilution. New investors’ ownership can also be affected, depending on how the round is priced.
Weighted average
Weighted average takes the lower price and the issuance size into account. With other inputs unchanged, a small issuance produces less adjustment than a large issuance at the same price.
The National Venture Capital Association (NVCA) model charter includes this formula:
CP2 = CP1 × (A + B) ÷ (A + C)
- CP1: The conversion price immediately before the issuance.
- CP2: The adjusted conversion price immediately afterward.
- A: The contract-defined common-share-equivalent base immediately before the issuance.
- B: The money or other value received in the new issuance divided by CP1, or the shares that amount would have bought at the old conversion price.
- C: The shares issued, or treated as issued, in the covered transaction.
“Broad-based” and “narrow-based” refer to what is included in A. A broader base produces a smaller downward adjustment, with the other inputs fixed. A narrower base produces a larger one.
The definition can include common stock, preferred stock on an as-converted basis, stock options that give holders a right to buy shares, and other convertible securities. Whether shares reserved for future option grants count depends on the language. “Fully diluted” generally counts shares plus specified rights to receive shares. Its precise denominator depends on the documents.
A worked down-round example
This hypothetical, simplified example compares ownership in one company immediately after a financing. It is not a valuation, investment-return calculation, or projection.
Before the round, the company has:
- 8,000,000 common shares;
- 2,000,000 Series A preferred shares purchased at $1.00 each, initially convertible one-for-one into common; and
- 10,000,000 shares on an as-converted basis.
The Series A investor owns 20% on that basis. The company then raises $5,000,000 by issuing 10,000,000 Series B shares at $0.50 each, also initially convertible one-for-one.
We hold the new price, cash raised, and new share count constant across the cases. There are no options, other equity purchase rights, Simple Agreements for Future Equity (SAFEs), debt that can convert into equity, option-pool increases, or other protected series. We assume no exclusions, waivers, participation requirements, intervening adjustments, or additional investment by the Series A holder. Fees, carry, taxes, exit-payment rights, and contractual rounding are outside this ownership-only example.
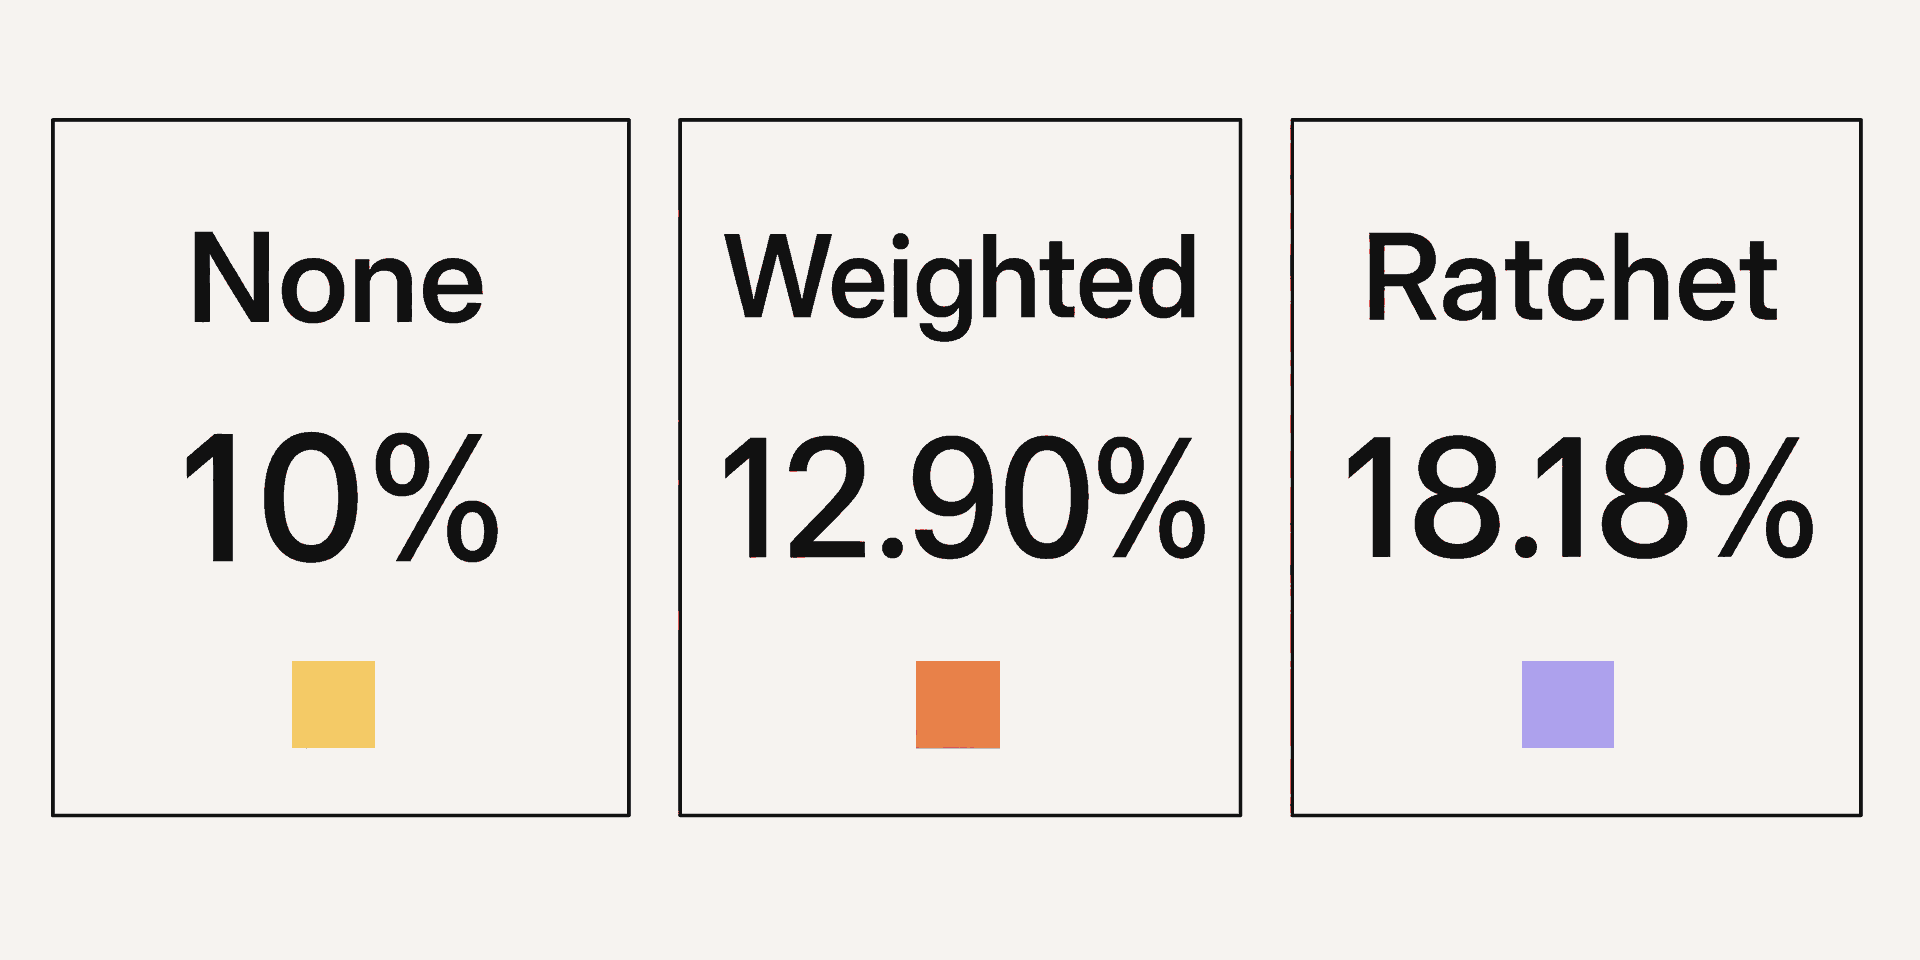
Without a price-based adjustment
Series A still represents 2,000,000 common-share equivalents. After the new issuance, the total is 20,000,000.
Its ownership falls to 2,000,000 ÷ 20,000,000 = 10%.
With full ratchet
The Series A conversion price falls from $1.00 to $0.50. Each preferred share can now convert into two common shares, so Series A represents 4,000,000 common-share equivalents.
The total becomes 8,000,000 + 4,000,000 + 10,000,000 = 22,000,000. Series A owns about 18.18% on an as-converted basis.
With broad-based weighted average
In this simplified cap table, A is 10,000,000. B is $5,000,000 ÷ $1.00, or 5,000,000. C is 10,000,000.
The adjusted conversion price is $1.00 × (10,000,000 + 5,000,000) ÷ (10,000,000 + 10,000,000) = $0.75.
Each Series A share can convert into approximately 1.3333 common shares. Series A represents about 2,666,666.67 common-share equivalents out of a total of 20,666,666.67, or about 12.90%.
Both provisions improve the Series A investor’s ownership relative to no adjustment. Neither preserves the starting 20%. In every case, the investor still holds 2,000,000 actual Series A preferred shares.
In a real round, a fixed pre-money valuation is the company’s agreed value before the new investment. If its pricing share count includes the anti-dilution adjustment, the price and share counts need to be solved together. Our cases instead fix the new price and share count, so they do not hold the new investor’s ownership percentage constant.
Preferred stock, SAFEs, and pro rata are different rights
An angel’s rights follow the security and its documents. The labels “angel” and “venture capitalist” don’t determine whether a share has anti-dilution protection.
An angel can hold protected preferred stock
If you buy preferred shares in a series with anti-dilution rights, those rights can apply to your shares. A smaller check does not automatically strip the series’ conversion protection away.
Separate participation rights may have investor-size thresholds. The NVCA model rights agreement, for example, uses a defined “Major Investor” threshold for its right to buy into later issuances. That threshold should not be confused with the charter’s preferred-stock conversion rights.
A SAFE’s cap is a conversion term
A SAFE gives an investor future equity rights. Before conversion, an unmodified U.S. Y Combinator (YC) cap-only SAFE does not give its holder the charter’s preferred-stock conversion-price protection.
A valuation cap sets an upper valuation reference for calculating conversion. A discount reduces the conversion price relative to the financing price. A most-favored-nation provision can allow specified later terms to be adopted. Their effects depend on the instrument; none guarantees protection against every future dilution.
At an equity financing, the YC cap-only SAFE uses the conversion alternative that produces more shares. After conversion, the rights of the preferred series issued to the investor matter. The U.S. SAFE forms separate these instruments and their terms.
“Post-money” in a post-money SAFE also needs care. Its ownership convention is after the SAFE money, before the new money in the priced financing. The SAFE user guide explains that boundary.
Pro rata requires another check
Pro rata is a right to buy additional shares with additional money, subject to its terms. It can help you maintain ownership if the right covers the issuance and you exercise it. Price-based anti-dilution changes conversion economics without requiring a new purchase for that adjustment itself.
Rights can expire. YC’s optional pro rata side letter covers the equity financing in which the SAFE converts and terminates at its initial closing, or an earlier specified liquidity or dissolution event. It does not provide perpetual follow-on access.
Even when participation is available, another check is a fresh investment decision. Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge: “Decisions are never in isolation - they are a comparison game.” A follow-on competes with other investments and your cash needs. Our explanation of pro rata rights explores that decision separately.
The terms that can change the protection
The formula is one part of the right. The NVCA model charter also illustrates exclusions, consent requirements, and an optional pay-to-play provision. A useful legal review covers:
- The protected series and trigger. Which shares have the right, what price triggers it, and how options or convertible securities are treated as issuances.
- The excluded issuances. Employee equity, existing security conversions, and other specified transactions may be excluded from price-based adjustments. Stock splits can have separate proportional adjustments.
- The share base. The precise definition of A, including options and convertible securities, matters more than the broad-based label alone.
- Waivers and amendments. The required holder consent can allow protection to be waived or changed. An individual investor may not have a personal veto.
- Pay-to-play. A provision may require participation in a qualifying financing to retain specified rights. Depending on the terms, nonparticipation can cause preferred stock to convert into common.
These are negotiated document choices, not rules that appear in every financing.
How we’d approach the negotiation
We’d start with the existing security and the full financing package. There is no universal $50,000 or $100,000 check threshold that makes anti-dilution available, and asking for a right does not obligate you to reject the deal if the answer changes.
For a priced preferred-stock financing, broad-based weighted average is a useful starting point for discussing price protection. It accounts for issuance size and avoids a full price reset from a small covered issuance. Full ratchet deserves careful modeling because its effect can be much larger.
For a SAFE investment, importing a preferred-stock clause into a side letter is a different drafting exercise. The conversion terms, future share class, and interaction with other investors’ documents all matter. Independent startup counsel can explain what a proposed term would change before you commit.
The founder’s remaining ownership and the company’s ability to finance its next stage belong in the same discussion. In the worked example, stronger protection increases the old investor’s common-share equivalents and reduces the percentages held by others. A clause that improves your percentage can still make the broader financing harder to agree on.
We’d evaluate that tradeoff alongside price, liquidation preferences that set payment priority and amounts in an exit, participation rights, and the amount invested. Our term-sheet guide puts those terms together.
Portfolio construction belongs alongside this document work. Elizabeth Yin’s advice in Democratizing Knowledge is direct: “Don't try to pick a co. Select a portfolio.” Spreading your startup exposure does not change a clause, cure an expensive entry price, or guarantee that winners will cover losses. You should be prepared for most startup bets to fail, including investments with anti-dilution protection.
To build your understanding of startup terms alongside other investors, apply to Angel Squad. Our community combines education, curated deal flow, and peer discussion so you can practice evaluating the full investment.
This material is educational and is not legal, tax, investment, accounting, or valuation advice. Seek independent review of the governing documents from qualified legal and tax professionals, and financial or valuation advisers where appropriate. Startup investments are speculative, illiquid, long-term, and can result in a total loss. Actual ownership and proceeds depend on the documents, cap table, financing and exit timing, distribution rights, and applicable fees, carry, and taxes. Paper values depend on the valuation method and policy; past results and current marks do not guarantee future results.











