
Angel Investing Taxes: A Practical U.S. Planning Guide
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Angel investing taxes can change with the instrument you sign, the entity that owns the investment, and what happens years later. Those details are easiest to capture while the deal is still fresh. A practical plan gives your tax and legal advisers the evidence they need before a sale, shutdown, or filing deadline forces a rushed answer.
Start with the four possible tax paths
A startup check doesn’t create an automatic federal deduction. Its tax consequences depend on the applicable rule and the later event. Separate the possibilities before you estimate any benefit:
- A tax credit reduces a tax bill under a specific program. Angel investor credits are generally state programs with their own investor, company, application, and timing rules.
- A gain exclusion can keep qualifying gain out of federal gross income. Qualified small business stock (QSBS) under Section 1202 is the main federal example for startup investors.
- A deductible loss may arise when stock is sold or becomes wholly worthless. The loss may be capital or, if the stock and taxpayer qualify under Section 1244, ordinary within statutory limits.
- A reporting obligation can exist without cash arriving. An investor in a partnership-taxed special purpose vehicle (SPV), for example, may receive a Schedule K-1 that reports the investor’s share of partnership items.
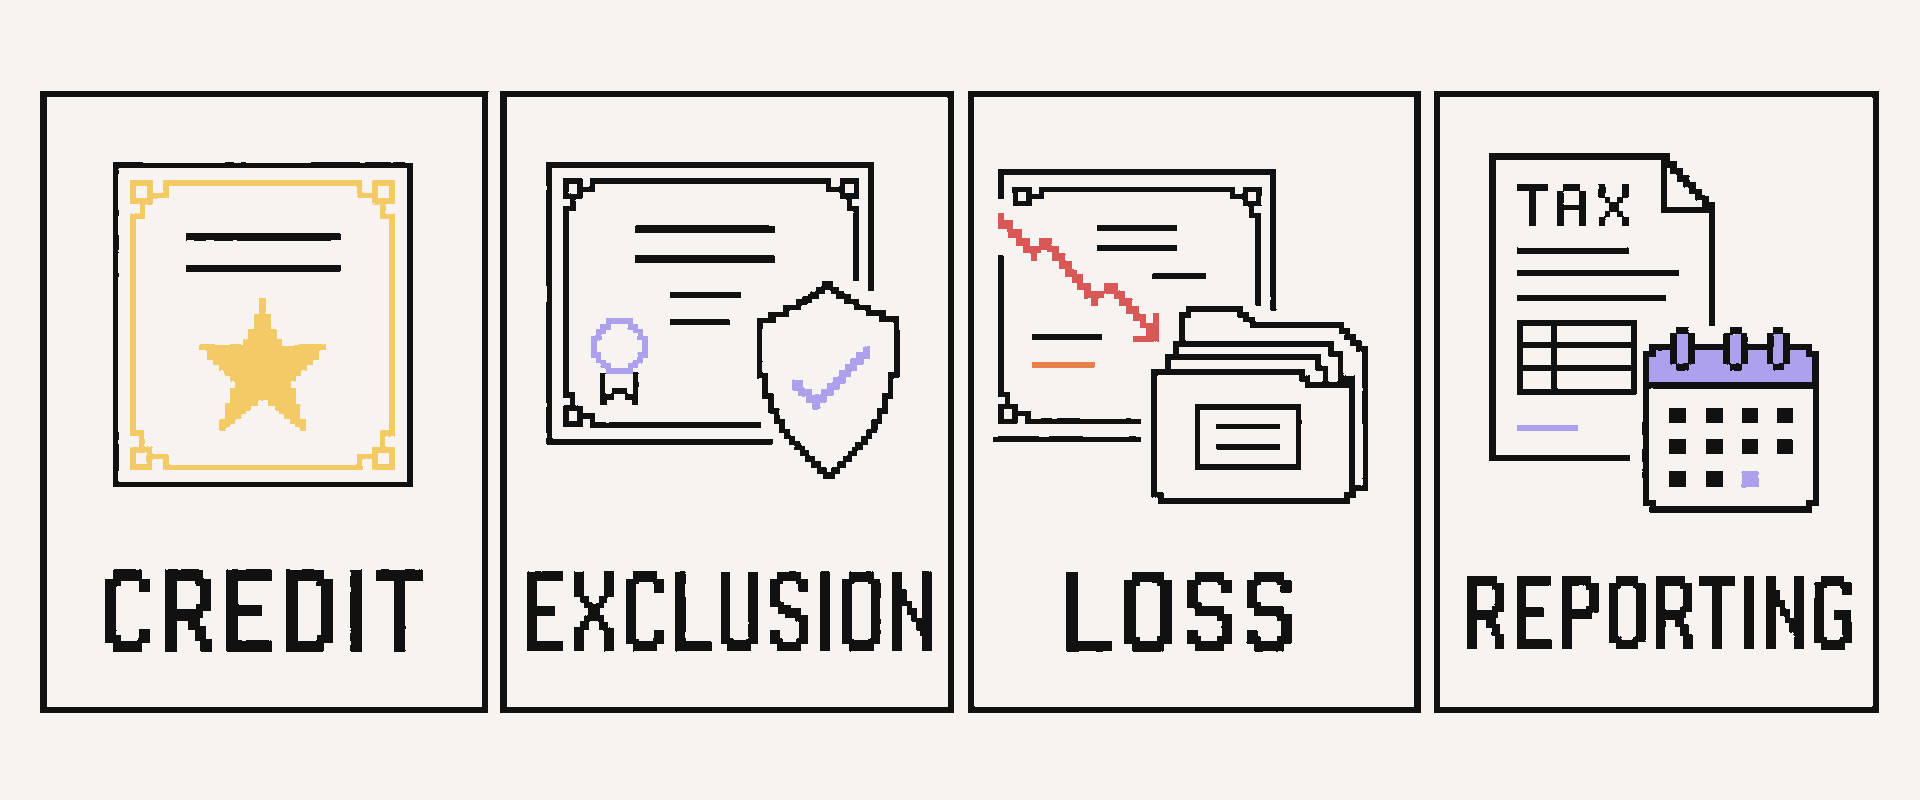
These paths can overlap. A state credit at investment doesn’t decide the federal treatment of a later sale. A K-1 doesn’t prove that cash was distributed. A company failure doesn’t by itself establish when a loss became deductible.
Our angel investing tax basics guide explains the first-pass mechanics. The planning job is to preserve choices and evidence across the full life of the investment.
Build the tax file before you wire
Tax diligence should sit beside business and legal diligence. Gather facts for an adviser. A founder cannot guarantee your personal tax result.
Record five items for every investment:
- The legal owner. Name the individual, trust, retirement account, limited liability company (LLC), or SPV that will hold the interest. A later transfer can raise separate tax, securities, and company-consent questions.
- The instrument. Save the signed stock purchase agreement, Simple Agreement for Future Equity (SAFE), convertible note, subscription agreement, and any conversion paperwork. A label alone doesn’t settle federal tax classification.
- The issuer facts. For a potential QSBS investment, ask for the corporation’s entity type, original-issuance details, aggregate gross assets before and immediately after the issuance, and the business activities relevant to Section 1202.
- Your basis and dates. Keep proof of payment, fees, issuance or acquisition date, number and class of shares, conversions, splits, and later contributions. Do not reconstruct basis from a cap-table screenshot years later.
- The reporting route. For an SPV or fund, record the tax contact, expected Schedule K-1 process, and where notices will arrive. Our K-1 investor guide explains that reporting lane in detail.
Elizabeth Yin, our co-founder and general partner, writes in Democratizing Knowledge, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” A one-page tax intake checklist applies that discipline to administration. It also makes your annual adviser conversation faster and more specific.
Keep the supporting documents in the same system as the investment record. Our separate record-keeping guide covers the full file rather than repeating it here.
Put QSBS on the agenda at acquisition
Section 1202 can exclude some or all qualifying gain on qualified small business stock held by a noncorporate taxpayer. The word “qualified” carries most of the work.
Under current Section 1202, stock generally must be original-issue stock in a domestic C corporation, the issuer must satisfy the aggregate-gross-assets test, and the corporation must meet an active-business requirement during substantially all of the holding period. The statute excludes several business categories and contains redemption, aggregation, transfer, and pass-through rules.
Federal law now treats newer shares differently. For QSBS acquired after July 4, 2025, the exclusion percentage is 50% after at least three years, 75% after at least four years, and 100% after at least five years. The same 2025 law raised the per-issuer dollar cap to $15 million for eligible post-July 4 stock and raised the issuer gross-assets ceiling to $75 million for stock issued after that date, with inflation adjustments scheduled for tax years after 2026. Older shares can follow different holding-period, exclusion, and cap rules. Our new QSBS rules guide walks through the change without turning this page into a second QSBS primer.
SAFEs and notes need instrument-specific review
Section 1202 applies to stock. A SAFE or convertible note can raise questions about when the investor acquired stock, whether the original-issuance requirement is satisfied, and when the relevant holding period begins. The tax code doesn’t give every startup instrument one universal answer.
Give your adviser the executed instrument, conversion documents, issuer history, and dates. Avoid writing “QSBS eligible” in your model as if it were a settled fact. Treat it as a diligence question until qualified counsel or a tax professional has reviewed the actual facts.
SPVs can preserve QSBS treatment only under conditions
Investing through an LLC or partnership-taxed SPV doesn’t automatically destroy QSBS treatment. Section 1202 has a pass-through rule, but the entity and investor must satisfy its conditions. Among them, the investor generally must hold the relevant entity interest when the entity acquires the stock and continuously through the entity’s disposition.
That is one reason to save subscription dates, ownership changes, and every Schedule K-1. It is also a reason to read the SPV documents before transferring an interest. For more complex trust and gifting questions, our QSBS stacking guide lays out the issues that require individual legal and tax review.
Plan for a sale before the terms harden
A signed exit document can leave little time to resolve holding periods, basis, rollover decisions, and estimated-tax cash needs. Start the tax review when a tender offer, secondary sale, merger, or acquisition becomes credible.
Bring your adviser a short transaction packet:
- the proposed seller and the asset being sold
- acquisition, issuance, and conversion dates
- basis and expected gross proceeds
- transaction fees, escrow, holdbacks, earnouts, and payment timing
- any QSBS support from the issuer or fund administrator
- state residence and other state connections during the relevant periods
If QSBS is sold before the Section 1202 holding period is met, Section 1045 may allow a qualifying noncorporate taxpayer to defer gain by purchasing replacement QSBS. The sold stock must have been held for more than six months, the replacement purchase window is 60 days from the sale, and the election has additional requirements. That short clock makes Section 1045 an early adviser question, never an after-filing cleanup tactic.
A taxable gain may also create an estimated-tax obligation. The IRS advises that taxpayers with taxable capital gains may need estimated payments. Set aside cash based on a professional estimate before reinvesting proceeds or making another startup check.
State treatment needs a separate analysis. States may differ on QSBS conformity, capital gains, residency, source rules, and angel investor credits. A federal conclusion doesn’t answer the state question, and a state credit program should be assessed under that state agency’s current rules.
Treat failure as a tax event with evidence
Startup stock can lose economic value long before it meets a tax rule for a deductible loss. Silence from a founder, an offline website, or an internal zero mark may be relevant evidence. None is a universal worthlessness test.
A startup that has stopped operating may still own cash or intellectual property and be negotiating an asset sale. Its shares may have little economic value, yet those facts don’t establish complete worthlessness. The investor’s next step is to collect the objective evidence and ask an adviser which tax year, if any, supports a loss.
Under the federal worthless-security rule, stock that becomes wholly worthless during the tax year is generally treated as sold on the last day of that year. IRS Publication 550 likewise says the security must become completely worthless and explains that the loss is reported on Form 8949. Save dissolution notices, bankruptcy records, final investor communications, cap-table information, and any recovery details for your adviser.
The default capital-loss path also has limits. Capital losses first offset capital gains. For an individual whose losses exceed gains, the annual deduction against other income is generally capped at $3,000, or $1,500 for a married person filing separately, under the federal capital-loss limit. The IRS capital-loss guidance explains that unused net capital losses can generally carry forward.
Section 1244 may treat a qualifying small-business-stock loss as an ordinary loss for an individual, subject to an annual ceiling of $50,000 or $100,000 on a joint return. Qualification depends on the stock, issuer capitalization, issuance, taxpayer, and company gross receipts. Read our Section 1244 guide before assuming the rule applies, and compare the facts with current Section 1244.
SAFEs, notes, and partnership interests can follow different loss and reporting rules. A fund or SPV’s write-down doesn’t automatically give every investor a personal deduction for the same year or amount. Wait for the governing documents, tax reporting, and professional analysis.
Run a four-moment tax calendar
Most angel-investment tax work belongs at four moments. Put them in your portfolio workflow so the tasks don’t depend on memory.
Before the investment
- Identify the owner and instrument.
- Ask the issuer or lead for the facts relevant to potential QSBS treatment.
- Send unusual entity, trust, retirement-account, SAFE, or note questions to your advisers before signing.
- Store the signed documents and proof of payment.
During the hold
- Record conversions, financings, redemptions, reorganizations, transfers, and SPV ownership changes.
- Collect annual tax forms and issuer notices.
- Keep your address and tax-delivery details current with every administrator.
- Revisit QSBS support when the company or your ownership structure changes.
Before liquidity or transfer
- Confirm basis, holding period, seller, expected proceeds, fees, and payment timing.
- Review federal and state treatment while there is still time to act.
- Raise Section 1045 within its 60-day window when the facts may fit.
- Reserve cash for estimated federal and state payments.
At failure or year-end
- Separate an internal valuation change from a closed transaction or complete worthlessness.
- Gather objective evidence about dissolution, bankruptcy, remaining assets, and possible recovery.
- Compare capital-loss, Section 1244, debt, and pass-through treatment with an adviser.
- Reconcile your records with Forms 1099, Schedule K-1, Form 8949, and Schedule D as applicable.
A tax benefit cannot rescue a weak investment
Tax treatment belongs in the investment memo as a scenario, never as the reason a speculative startup becomes investable. Most individual startup bets may fail, and even surviving companies may never provide liquidity. A financing, redemption, business change, transaction structure, or missed document can alter the expected tax result.
Elizabeth puts the risk plainly in Democratizing Knowledge: “Investing in risky/uncertain things (such as startups) is a total mindwarp.” Good tax planning respects that uncertainty. It records the facts, preserves deadlines, and gets the right professional involved before the decision becomes irreversible.
Build the habit with other angels
Tax judgment improves when it sits inside a repeatable investment process. Members of our community learn from Hustle Fund’s early-stage approach, review curated opportunities, and compare diligence questions while leaving deal-specific tax conclusions to their own qualified advisers. If you want to build that process with peers, apply to Angel Squad.
This material is for general educational purposes only and does not constitute tax, legal, investment, accounting, or valuation advice. Angel investments are speculative, illiquid, long-term, and may result in total loss. Tax treatment depends on the taxpayer, issuer, instrument, holding period, transaction documents, entity structure, and applicable federal, state, and local law. Review the governing documents and your circumstances with qualified, independent tax and legal professionals before acting. Past results and current marks do not guarantee future results.











