
First Angel Investment in 30 Days: A Decision Plan
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Treat a plan for a first angel investment in 30 days as a decision window, not a promise to write a check. You will set financial boundaries, learn the basic deal structures, compare opportunities, investigate one company, and document your judgment. If no suitable deal appears, a well-reasoned pass is a successful outcome.
What 30 days can and cannot do
Angel investing means putting your own money into a private startup, directly or through a vehicle that holds the startup investment. You might buy shares now, hold debt that can convert later, or sign a Simple Agreement for Future Equity (SAFE), a contract that may convert into shares if its stated trigger occurs.
A month can teach you the vocabulary and give you a first decision process. It cannot make startup outcomes predictable, create liquidity, or turn an unsuitable deal into a suitable one. The Securities and Exchange Commission (SEC) warns that private placements can produce a total loss, offer limited disclosure, and require investors to hold securities indefinitely.
Use the plan only with money whose complete loss would not change your living expenses, emergency savings, taxes, retirement plans, or other obligations. Diversification may reduce the damage from one company failing, but no fixed number of startup investments suits every investor. Your finances, access, time, and tolerance for illiquidity should determine your pace with help from your own advisers.
Before Day 1: pass the readiness gate
Start the clock after these four conditions are true:
- Your risk budget is written. Set the maximum amount you can lose and leave locked up. Set a separate cap for one check. A legal investment limit is a ceiling, not a recommendation.
- You know which offerings you may enter. Many private startup rounds use Regulation D. Common individual routes under the current accredited investor definition include income above $200,000 individually or $300,000 with a spouse or spousal equivalent in each of the prior two years, with a reasonable expectation of the same this year, or net worth above $1 million excluding a primary residence. Certain professional credentials and other categories can also qualify.
- You understand routes open to non-accredited investors. Regulation Crowdfunding (Reg CF) is one non-accredited route, subject to an aggregate 12-month investment limit. Under the current rule, the transaction must occur exclusively through one online platform operated by a single SEC-registered broker-dealer or funding portal, each a Financial Industry Regulatory Authority (FINRA) member. Follow verified payment instructions provided through that platform. Those instructions may direct funds to a qualified third-party escrow or holding party, as the SEC intermediary guide explains. Never pay the startup directly for a claimed Reg CF investment. Regulation A can also admit non-accredited investors, with limits depending on the tier and circumstances.
- You are willing to pass. A founder’s deadline, a popular co-investor, or a full allocation bar cannot substitute for missing evidence or terms you do not understand.
Joining an investing community does not make you accredited. Eligibility attaches to the investor and the offering. Suitability is a separate personal decision.
The month has four jobs: define your boundaries, compare available deals, investigate one candidate, then decide and document. Each phase leaves an artifact you can reuse.
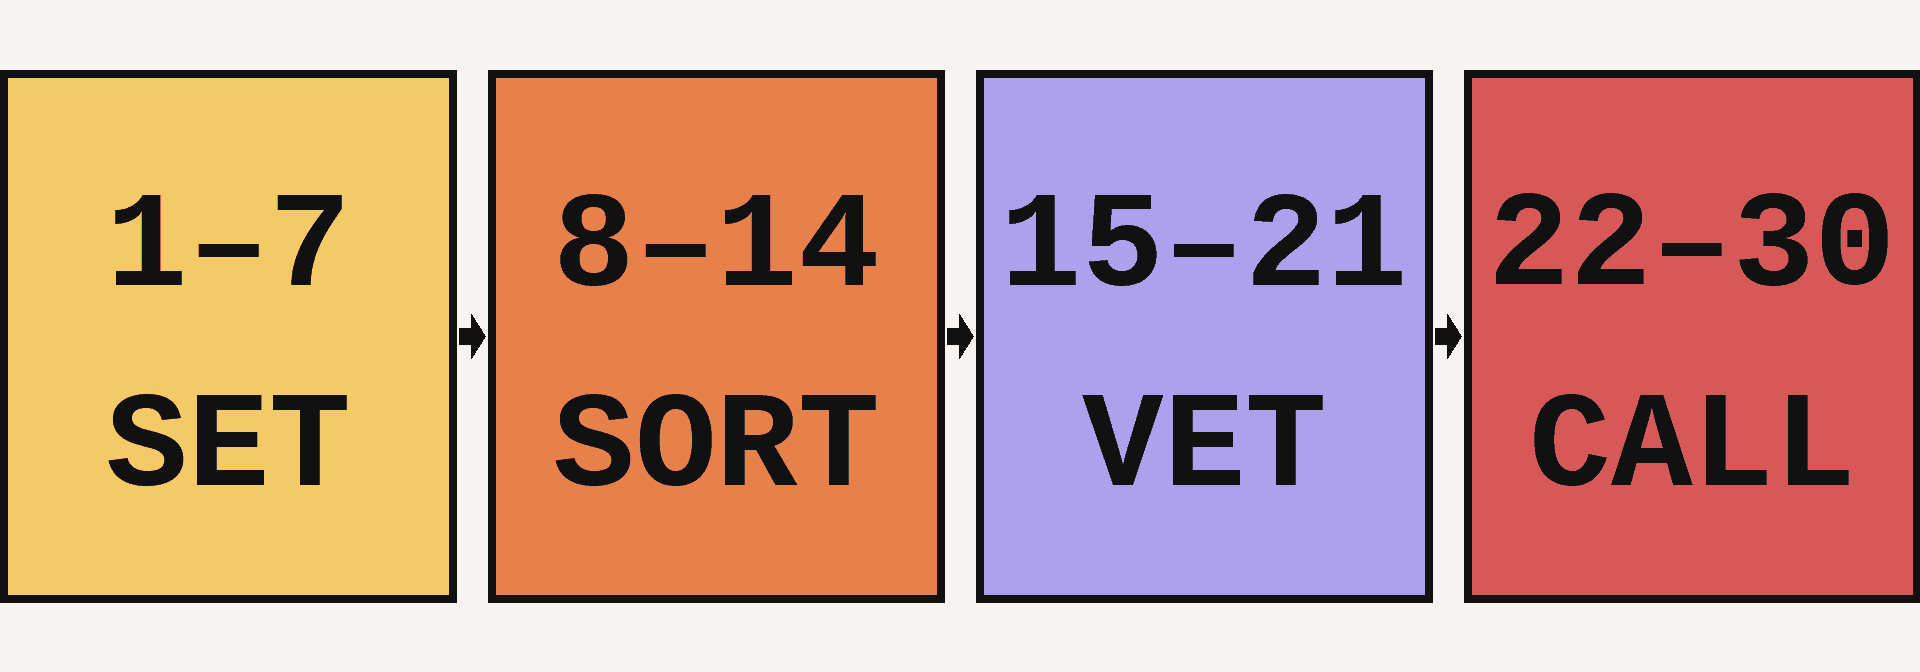
Days 1–7: build your rules before you see the pitch
Learn the minimum viable vocabulary
Learn what you could own:
- Priced equity: shares issued now at a stated price, with rights defined across the company’s governing documents.
- SAFE: a contract for potential future shares. A SAFE is not current stock and may never convert if no stated trigger occurs. Read the SEC’s SAFE investor bulletin.
- Convertible note: debt that can convert under stated terms. Interest, maturity, repayment, and conversion mechanics matter.
- Special purpose vehicle (SPV): a legal vehicle that pools investors and holds the startup security. You own an interest in the vehicle, so fees, carry (the manager’s stated share of investment profits), manager powers, expenses, and distribution rules affect your position.
You need enough fluency to explain the instrument, recipient, fees, rights, and main risks in plain English. You do not need to become a securities lawyer in a week.
Write a personal opportunity filter
Choose the sectors, stages, geographies, and business models you can assess from real experience. A hypothetical business-to-business software operator may understand enterprise buying cycles and retention evidence while lacking the expertise to underwrite a clinical biotech program. That is a useful boundary, not a verdict on either sector.
Record your check cap, annual startup risk budget, expected holding constraints, and automatic pass conditions. Examples include an investing entity you cannot identify, founder claims that conflict with records, missing documents, terms you cannot explain, or pressure that prevents adequate review.
Open a deal log
Create the log before your first check. Give each opportunity one row or note with:
- company, source, and review date
- problem, customer, stage, and instrument
- terms and investing entity
- evidence reviewed and open questions
- decision, amount, and reason
- future milestones and updates
Find two or three near-peer investors who made their first investment within the past year. Ask what confused them, which document deserved more attention, and why they passed on one memorable deal. Near peers often remember the beginner questions that experienced investors have stopped noticing.
Day 7 deliverable: a written risk budget, opportunity filter, pass list, and empty deal log.
Days 8–14: compare deals without trying to force a winner
Review the live or historical opportunities available to you. Volume does not prove progress. Two carefully compared companies can teach you more than 15 pitch decks skimmed to hit a quota.
If you are sourcing without a community or membership, FINRA’s funding-portal list is one place to identify portals that may host Reg CF offerings. The list includes suspended firms, so check a portal’s current registration and suspension status before using it. For a broker-dealer or broker, check FINRA’s BrokerCheck. A listing or registration record is not an endorsement of the intermediary or any offering. Evaluate each candidate independently.
For each company, fill in the same deal-log fields. Separate three layers:
- The company’s claim. What did the founder or deck state?
- The curator’s view. What did the lead investor, platform, or memo investigate and conclude?
- Your evidence. What can you substantiate, what remains unknown, and which uncertainty are you willing to accept?
Curated deal flow and a lead investor’s memo can save sourcing and first-pass work. They do not transfer the decision or the risk. In our Angel Squad community, members can read deal memos, review opportunities sourced by Hustle Fund, and compare notes with peers. Membership does not require accredited investor status. Eligibility for each investment is separate, and the private deals we currently share require accredited investor status. There is no obligation to invest.
Attend one pitch or deal-review session if one is available. Ask one relevant question about evidence, terms, or downside, then record the answer. If no live session fits the week, use a recording or a historical deal and write the question you would have asked.
Compare notes with a peer who is willing to disagree with you. Ask which fact would change each person’s view. Agreement feels nice. A specific disagreement exposes the assumption doing the real work.
Day 14 deliverable: completed notes on available opportunities and a shortlist of zero to three companies. Zero is valid when nothing fits your filter.
Days 15–21: investigate one candidate and write the case against it
Pick one candidate only if it fits your financial limits and knowledge boundary. Start with the evidence most likely to change your decision.
Check four diligence buckets
- Founders. Confirm roles, work history, domain knowledge, commitment, and ownership of product, sales, and operations. Ask references how the founders respond when they are wrong or under pressure.
- Product and customers. Inspect the product or credible usage evidence. Trace revenue, retention, pilots, contracts, and customer claims to their source. Define what is observed, contracted, collected, or projected.
- Market and execution. Identify how the customer solves the problem now, why this team can enter, and what must become true for growth. Our co-founder and general partner (GP) Eric Bahn puts it plainly: “Pre-seed investing and seed investing is largely an exercise of assessing the potential of the founders.” Look for fast learning tied to evidence and a meaningful metric, rather than motion for its own sake.
- Company and financing. Identify the legal issuer or SPV, security, fundraising target, use of funds, cash runway, meaning how long the company expects its cash to last at its expected net cash-burn rate, debt, outstanding SAFEs or notes, option pool, valuation or cap, senior rights, fees, carry, conflicts, and possible dilution. Read the actual documents.
Match the documents to the offering route. For Reg CF, read the issuer’s Form C and any amendments. For Regulation A, read the offering circular and use SEC EDGAR to find the specific issuer’s Form 1-A materials, including amendments or supplements, plus the QUALIF Notice of Qualification before you buy. The SEC’s Regulation A guide provides background on the qualification requirement, but it does not confirm a particular offering’s status. For Regulation D, read the applicable private-placement documents, which may include an offering memorandum, subscription agreement, instrument or governing documents, and side letters. A Form D is a notice filed after the first sale. None of these filings means the SEC approved the merits of the deal.
Diligence depth should follow the size of the possible loss, the complexity of the business and financing, the reliability of the evidence, and your ability to understand it. A small check can still create legal, tax, fraud, and reputation exposure.
Write a one-page memo with the decision still blank. Include the thesis, supporting evidence, strongest case against the investment, unresolved questions, instrument, terms, proposed amount, and facts that would cause a pass.
Day 21 deliverable: a dated memo whose risks are as specific as its upside case.
Days 22–30: decide, then close only if the evidence supports it
Make the invest-or-pass decision
Set a quiet deadline before the issuer’s deadline. Read your original filter, deal log, and memo without the pitch deck open. Then choose:
- Invest: material questions are answered, the remaining unknowns are explicit, the structure fits your limits, and you can accept a complete loss.
- Pass: a material claim conflicts with evidence, an important question stays unanswered, the structure remains unclear, the deadline blocks responsible review, or the deal sits outside your risk budget.
- Pause: more evidence could resolve a specific question and the process allows time. Name the missing evidence and a final decision date.
A pass does not require proof that the company will fail. “I cannot underwrite this risk” is enough.
Complete the decision line in your memo. In Democratizing Knowledge (2021), page 131, our general partner Elizabeth Yin writes, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” A dated record protects the lesson from hindsight.
If you invest, finish the full close
A commitment click or bank transfer does not prove that an investment closed. Use our first-check execution guide for the detailed workflow. At minimum:
- Read the subscription agreement, SAFE or note, stock purchase papers, SPV agreement, offering memorandum, and side letters that apply as one package.
- Reconcile the investor name, recipient, amount, instrument, valuation or cap, rights, restrictions, fees, carry, conflicts, allocation, cancellation terms, and tax administration across every document and screen.
- For Reg CF, complete the transaction exclusively through the one registered intermediary’s online platform. Follow verified payment instructions provided through that platform, which may direct funds to a qualified third-party escrow or holding party. Never pay the startup directly. For other routes, confirm funding instructions through a known platform or an independently established issuer contact. Stop if the account changes.
- Save the transfer receipt, accepted or countersigned documents, closing notice, final allocation, ownership or SPV record, contact details, and expected update and tax-document channel.
- Update the deal log with what actually closed, which may differ from the amount first requested.
Qualified independent legal and tax professionals should review questions specific to your documents, entity, jurisdiction, and circumstances. A community, platform, memo, or learning plan cannot provide that personal review.
If you pass, keep the record
Finish the memo with the decisive reason, the evidence that would have changed your answer, and the next type of opportunity you want to review. A clean pass gives you a reusable boundary. Deleting the notes wastes the work.
Day 30 deliverable: a completed invest, pass, or pause memo. If you invested, add the final closing record. If you passed or paused, add the next review condition.
Your Day 30 scorecard
You have completed the plan when you can check each item:
- Your startup risk budget and single-check cap are written.
- You know the offering route, eligibility rule, security, and investing entity.
- You used the same deal log to compare available opportunities.
- You investigated one candidate deeply enough for its complexity and your possible loss.
- Your memo records evidence, risks, unknowns, terms, and a reasoned decision.
- Any investment has a confirmed close and permanent document record.
- Your next review date and learning goal fit your life, without a mandatory deal count or deployment schedule.
The month measures process, not courage. An invest decision, a pass, and a pause can each be correct when the record supports it.
Build your judgment with people who will challenge it
If you want curated deal flow, investing education, and peers who can pressure-test your first memo, apply to Angel Squad. Membership is open without accredited investor status, while eligibility for our current shared private deals requires accredited status. There is no obligation to invest. Bring your risk limits and your willingness to pass.
This material is for educational purposes only and is not investment, legal, tax, accounting, or valuation advice. Startup investments are speculative, illiquid, long term, and can lose their entire value. Offering documents, fees, carry, capitalization, tax treatment, valuation methods, closing terms, and timing affect outcomes. Read the governing documents and consult qualified independent investment, legal, tax, accounting, and valuation professionals for advice on your circumstances.











