
Angel Investing Due Diligence Checklist (Step-by-Step)
Brian Nichols is the co-founder of Angel Squad, a community where you’ll learn how to angel invest and get a chance to invest as little as $1k into Hustle Fund’s top performing early-stage startups.
Angel investing due diligence starts after a startup earns your interest. You test the claims that drive the investment, surface risks the pitch omitted, and record what remains unknown. The depth should fit the company, stage, risk profile, and size of your check.
This material is educational. It is not legal, tax, or investment advice. Financing documents, entity law, securities rules, IP, employment obligations, and tax treatment vary by company, investor, and jurisdiction. Use qualified startup counsel for legal review and a qualified tax professional for tax questions before you commit capital.
Run angel investing due diligence in five steps
Due diligence is risk mitigation. It cannot make an early-stage company predictable. Many startup financings are private placements with less required disclosure than registered offerings, and investors may need to hold an illiquid security indefinitely, as the SEC's investor bulletin explains.
We organize diligence into three buckets:
- People: integrity, founder-market fit, learning speed, role coverage, and working relationships.
- Product: customer pain, product quality, distribution, traction, technology, security, and defensibility.
- Paperwork: ownership, financing terms, corporate approvals, intellectual property (IP), contracts, compliance, and financial records.
The five steps below move through those buckets in a repeatable order.
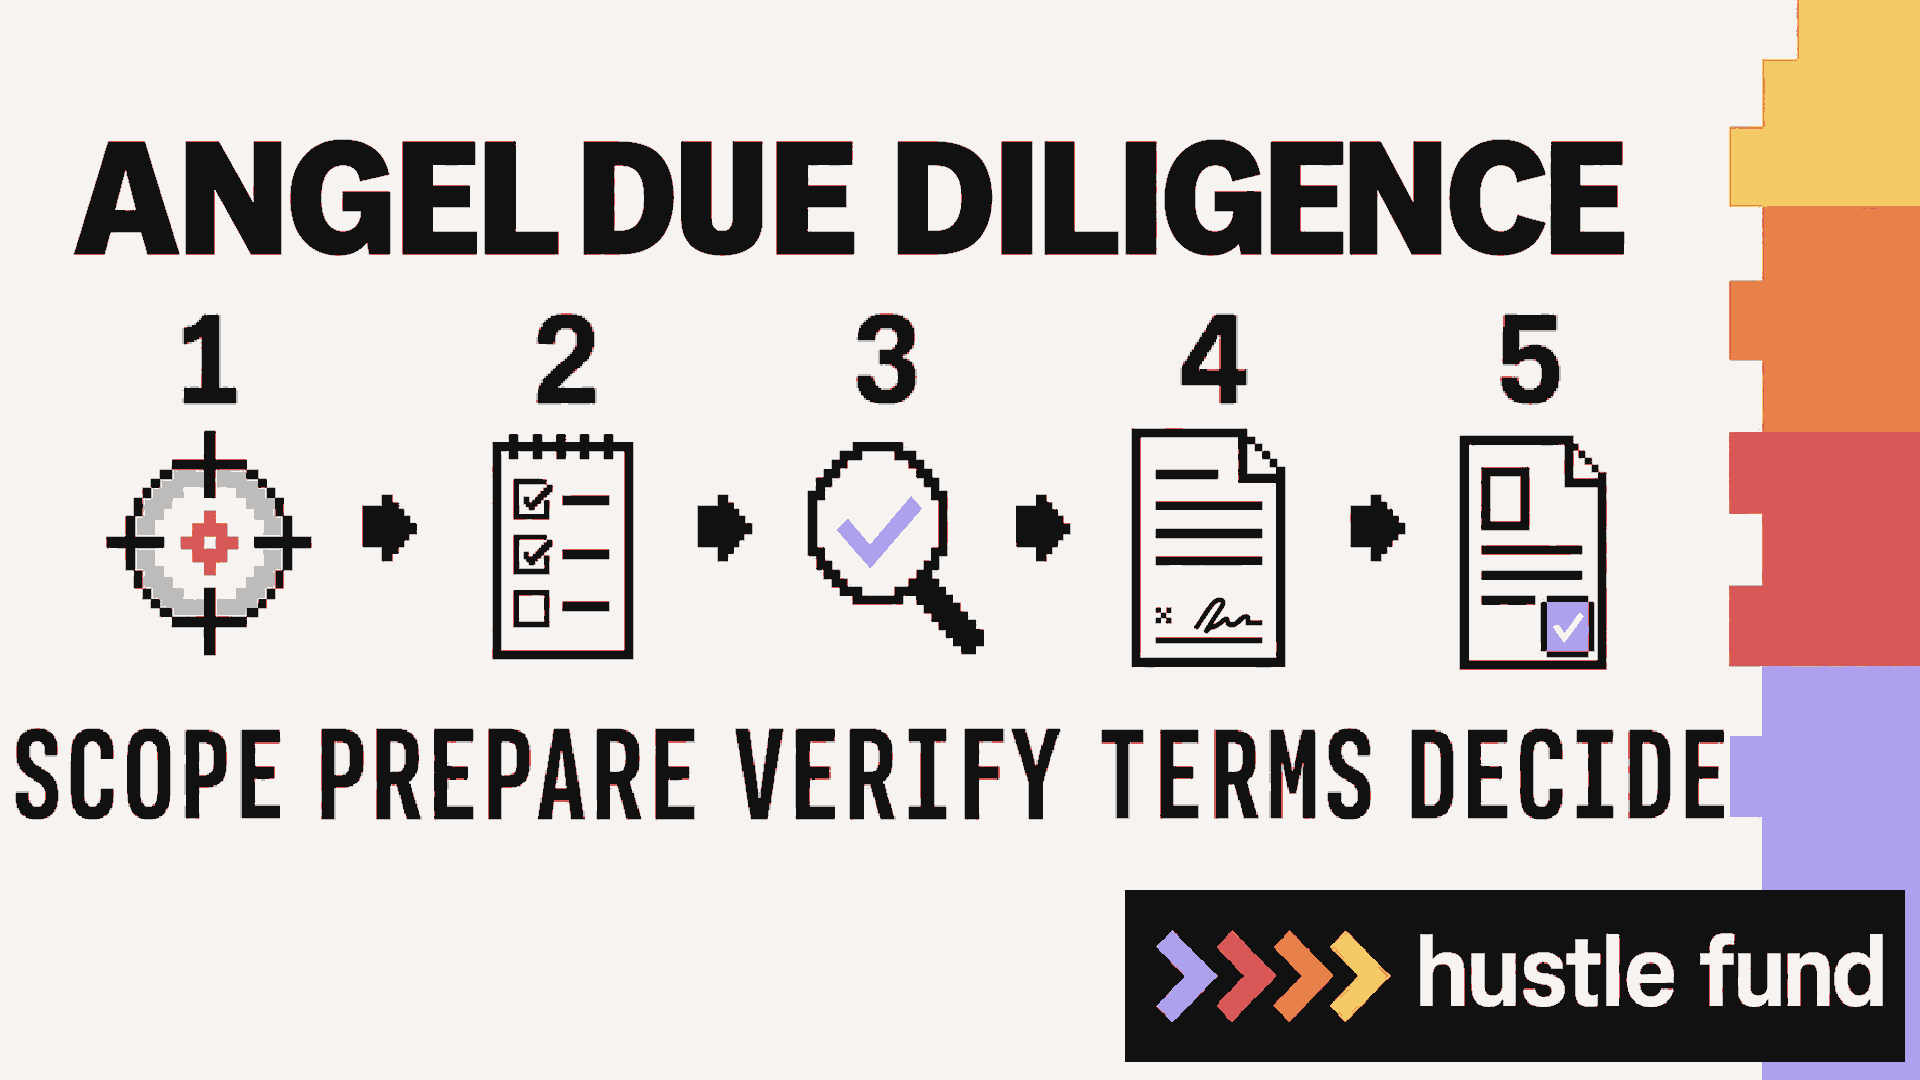
1. Scope the work in proportion to the risk
Write down the three to five claims that must be true for the investment to work. Rank each by potential impact and uncertainty. Those claims become your diligence plan.
Set the depth using four factors:
- Stage: At pre-seed, weight the founders, problem insight, customer discovery, prototype, use of funds, and ownership basics. At seed, add retention, unit economics, go-to-market (GTM) repeatability, hiring, security, contracts, and a fuller financial review.
- Check size: A small portfolio check may justify a founder follow-up, a reference, customer evidence, and a focused document review. A concentrated or large check deserves more independent calls, scenario work, and professional review.
- Your role: A follower can study a lead's work, then verify the claims most important to their own thesis. A lead's responsibilities depend on its role, structure, agreements, and applicable law. An informal lead may share its work, while a syndicate or special purpose vehicle (SPV) manager may have additional diligence, disclosure, administration, or fiduciary duties under the governing agreements and applicable law. Qualified counsel can interpret them.
- Risk profile: Add depth for regulated markets, clinical or deep technology, hardware, sensitive data, unusual entity structures, customer concentration, disputed IP, or financing terms you do not understand.
Do not reward effort for its own sake. Early-stage diligence rarely benefits from:
- A five-year forecast treated as a promise.
- A perfectly polished data room.
- A line-by-line code audit when the technology is not the core risk.
- Informal background searches on every employee.
- A giant market report that never reaches a specific customer, price, and route to market.
Use a decision date to keep the process finite. Our illustrative starting point is a two-week schedule:
- Days 0 to 2: Check thesis fit, list the decisive claims, scan for obvious conflicts, and send one document request.
- Days 3 to 10: Hold founder follow-ups, see the product, call references and customers, and reconcile the evidence.
- Days 10 to 14: Review terms and legal issues, close the most important gaps, and write the decision memo.
Compress that schedule for a small follower check with credible lead work. Extend it when technical, legal, regulatory, or customer risk needs specialist review.
2. Prepare before the founder meeting
Preparation turns a pitch call into an evidence-gathering conversation. Start with this checklist:
- Write your thesis fit in one sentence.
- State the three claims that would make the deal work.
- State the facts that would make you pass.
- Read the deck, product site, financing summary, and public founder history.
- Separate facts, forecasts, and your own assumptions.
- List contradictions or missing numbers to resolve live.
- Decide which questions require a document, a demo, a customer, or a reference.
If the deal comes through a lead, syndicate, or SPV, ask what role the manager is performing, what it verified, and what it accepted on the founder's word. Our co-founder and general partner Shiyan Koh has a clean test: “Show me the incentives, and I'll show you the outcome.” Review any administration fee, management fee, carried interest, allocation policy, follow-on rights, and voting or decision authority. Ask whether the lead, its affiliates, or anyone who introduced the deal receives compensation, and whether the lead is investing its own capital. The governing structure, agreements, and applicable law determine the manager's duties.
Diligence also runs both ways. Tell the founders what help you can provide, how often you expect updates, whether you may invest again, and where you have conflicts. Invite them to speak with founders you have backed. Founder-investor alignment matters because this relationship can last for years.
3. Gather evidence, including behavior
Match each claim to the strongest available source. A founder answer starts the inquiry. A live demo, bank or accounting record, signed contract, product data, customer conversation, or independent reference can confirm it.
Watch how the team handles the process. Do answers stay consistent across meetings? Can a founder distinguish what they know from what they believe? Do they send the promised follow-up? Do co-founders let each other answer questions in their own domains? Conversation behavior provides signals about preparation and working dynamics. Consistency can support a hypothesis about candor, but it is not proof of honesty. Corroborate important claims. Avoid treating accent, polish, confidence, or familiarity as competence.
Before outreach beyond founder-supplied names, get founder consent when the contact could reveal the company, financing, or a sensitive relationship. Respect privacy, confidentiality, and reasonable boundaries. Then, with appropriate discretion, speak with a former manager, peer, direct report, customer, or prior investor who saw the founder under pressure. Ask for an example of missed commitments, conflict, changed judgment, and whether the person would work with the founder again.
Keep founder background work focused and proportional to risk. With the founder's informed consent, verify only the identity, employment, education, professional license, litigation, or other history that could change your thesis, and treat a discrepancy as a prompt for context rather than an automatic finding of misconduct. If you engage a screening provider, minimize the personal data you collect and ask counsel which notice, authorization, privacy, and retention rules apply to the people and jurisdictions involved.
Sanctions compliance deserves the same risk-based treatment. U.S. persons must comply with sanctions administered by the U.S. Treasury's Office of Foreign Assets Control (OFAC), but that does not create one universal "OFAC check" for every angel investment. The sensible scope depends on the investors, company, founders, major owners, transaction vehicle, banks, locations, and applicable sanctions programs.
Where those factors create exposure, a risk-based screen of the relevant people and entities against current applicable lists may be warranted. Compare more than names because OFAC notes that many hits are false positives. Pause a close match, ownership concern, or geography-based sanctions issue and route it to qualified sanctions counsel or compliance personnel before signing or funding.
For customer evidence, combine founder-supplied calls with independently sourced market conversations when possible. Ask what happened the last time the problem appeared, how it is solved now, who owns the budget, and what switching would require. Never pose as a customer or misuse confidential information.
In Angel Squad, our angel-investing community, templates and peer review make this work easier to repeat. A shared framework helps investors compare notes without outsourcing judgment.
4. Review terms, legal issues, and the payment path
Read the actual documents. For a Simple Agreement for Future Equity (SAFE), identify the valuation cap, discount, conversion mechanics, pre-money or post-money form, pro rata rights, information rights, and side letters. An MFN, or most favored nation, clause may let a holder elect specified terms from a later SAFE, depending on the document. It does not have one universal effect.
For a convertible note, add interest, maturity, repayment or conversion provisions, and any security or seniority. For a priced round, focus on share class, liquidation preference, participation or conversion, seniority, anti-dilution provisions, option-pool treatment, voting and board rights, protective provisions, information rights, and pro rata rights. Our explainers on post-money valuation mechanics and liquidation preference can help you frame questions for counsel.
If you are asked to send a wire, confirm the recipient's legal name and role against the final documents. The recipient could be the company, an escrow account, or an investment vehicle. Confirm the instructions by phone using a number you obtained independently or used before. The FBI's wire-fraud guidance recommends calling through independently sourced contact information. Stop if instructions change at the last minute and repeat the verification.
5. Make and record the decision
Resolve every issue by classifying it as:
- Verified: Evidence supports the claim.
- Disconfirmed: Evidence contradicts the claim.
- Open: The answer remains uncertain and the uncertainty is acceptable.
- Blocking: The risk must be resolved before an investment.
Then choose invest, pass, or wait. A wait needs a specific trigger such as a signed pilot, reconciled cap table, specialist opinion, or founder commitment. “More traction” is too vague.
Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge (p. 287), “Decisions are never in isolation - they are a comparison game.” Your final comparison includes the deal, your other opportunities, and the option to keep the capital uncommitted. The memo near the end of this checklist captures that decision.
Founder and team checklist
At the earliest stages, the team carries unusual weight because the product and market approach may change. Look for relevant insight, integrity, pace, judgment, and the ability to recruit.
- Founder-market fit: What gives this team unusual access to the problem, customer, technology, or distribution?
- Learning ability: What belief changed after customer evidence? Our coachability framework offers deeper questions.
- Execution: What did the team ship, sell, recruit, or learn in the last 30 to 90 days?
- Role coverage: Who owns product, engineering, sales, operations, and finance? Which missing role becomes urgent after the raise?
- Co-founder history: How long have the founders known each other, what have they built or overcome together, and why did they choose to partner?
- Co-founder dynamics: How do they divide authority, handle disagreement, and resolve a deadlock?
- Commitment: Are the founders full-time? If not, what is the transition plan and what dependencies remain?
- Incentives: What are the vesting terms, option pool, advisor grants, and consequences if a founder leaves?
- References: Do supplied and independently sourced references tell a consistent story about performance under pressure?
One weak answer is a question. A pattern of evasion, blame, or shifting facts is a risk.
Market and customer checklist
Define the ideal customer profile, user, buyer, and budget owner. They may be four different people.
- Ask customers to describe the last occurrence of the problem and its cost in time, money, missed revenue, or risk.
- Identify the current workaround, including spreadsheets, agencies, internal tools, and doing nothing.
- Confirm who can approve a purchase and what security, legal, procurement, or integration steps slow it down.
- Build market size from a realistic customer count and annual contract value, then apply adoption limits.
- Identify the initial wedge and an evidence-based expansion path.
- Ask why the market is changing now and why incumbents have not already solved the problem.
- Map direct competitors, substitutes, and the customer's option to delay.
Test the return path too. Who could credibly acquire the company, what strategic asset would they buy, and what milestones would make that outcome plausible? An initial public offering may be possible. It should not be the only path in your reasoning. Model whether a conservative exit could still produce an acceptable result after future dilution and the preference stack.
Product, technology, security, and IP checklist
Watch a live product demo. Start at sign-up or implementation, then follow the user to the first useful outcome.
- Value: Does the product solve the painful part of the workflow?
- Adoption: What blocks setup, activation, repeat use, or team-wide rollout?
- Delivery: How often does the team ship, and what did recent customer feedback change?
- Reliability: What fails today, and how does the team detect and recover from it?
- Defensibility: Is the advantage rooted in data, workflow, distribution, switching cost, IP, speed, or another concrete asset?
- Dependencies: Which cloud, model, platform, supplier, manufacturer, or license can change cost or access?
For security, scope questions to the data and promises involved. Ask what data the company collects, where it resides, who can access it, how access is removed, whether multi-factor authentication and backups are used, how incidents are handled, and which vendors process customer data. The NIST small-business guide is a useful baseline. A company selling into healthcare, finance, government, or large enterprises may need specialist review and evidence that matches its claims.
For IP, confirm that founders, employees, and material contractors assigned relevant work to the company. Review licenses for third-party code, data, models, university research, or prior-employer work. Patents matter when the business depends on enforceable technical rights. A confidentiality agreement or clause may protect information under its terms. Confidentiality obligations alone do not transfer IP ownership. Read the full agreement, including its assignment provisions, with qualified counsel.
Traction and go-to-market checklist
Use metrics that match the business model and stage. Revenue is useful. Retention, usage, paid pilots, conversion, sales-cycle progress, and customer learning may be more informative before revenue becomes repeatable. Our guide to early-stage traction goes deeper.
- Reconcile headline metrics to a dated source and a clear definition.
- Separate contracted revenue, recognized revenue, pipeline, pilots, letters of intent, and verbal interest.
- Review cohorts for retention, repeat use, expansion, or churn.
- Explain any spike from a launch, promotion, founder network, channel partner, or one large customer.
- Identify the GTM motion, owner, sales cycle, conversion steps, and cost drivers.
- Compare customer acquisition cost (CAC), gross margin, payback, and lifetime value only when the data is mature enough to support them.
- Ask what channel has failed and what the team learned from it.
For business-to-business companies, paid conversion, renewals, expansion, and referenceable customers are strong signals. For consumer companies, activation, repeat use, retention curves, organic acquisition, and monetization matter more than downloads alone.
Financials, cap table, and future funding checklist
Review cash in context. The raise should fund specific work that reaches a measurable milestone before the company needs capital again.
- Current cash, monthly burn, runway, payroll, debt, and material liabilities.
- Historical profit and loss statement, plus a simple balance sheet and cash flow view when available.
- A 12 to 18 month operating plan with assumptions, hiring, use of funds, and a downside case.
- Revenue by customer, refunds, churn, gross margin, and concentration where relevant.
- Bookkeeping, payroll-tax, income-tax, and sales-tax processes appropriate to the business and jurisdiction.
- Current cap table on a fully diluted basis, including issued shares, options, warrants, SAFEs, notes, side letters, and promised grants.
- Founder ownership and vesting, employee option capacity, and advisor grants.
Then model future financing. Ask how much capital the company may need to reach its next two major milestones, which financing routes are plausible, and how another option-pool increase plus one or two rounds could affect your ownership. Include all outstanding SAFEs and notes. Exact dilution depends on the documents and future financings, so treat the model as a scenario and have counsel review the mechanics.
Capital strategy also tests alignment. A founder aiming to build a durable cash-generating company may make different financing and exit choices from one pursuing rapid venture-scale growth. Decide whether that path matches your return goals before you invest.
Legal and stage-calibrated data room checklist
Ask for one organized folder with a current index. At the earliest stages, an incomplete data room is not automatically fatal. Missing or irreconcilable basics such as formation records, the cap table, financing documents, and IP assignments can stall a close until the gaps are resolved. Substance comes first. Clean naming and prompt follow-up are secondary signals of operating discipline. A beautiful data room cannot repair a false metric, missing ownership, or a broken financing record.
Pre-seed baseline
- Formation document, governing document, and relevant amendments.
- Current cap table and schedule of outstanding SAFEs, notes, options, warrants, and side letters.
- Proposed financing instrument, subscription document, or term sheet.
- Founder equity purchase and vesting records, plus approvals for issuances.
- IP, confidentiality, and invention-assignment agreements for founders and material contributors.
- Current cash, burn, runway, operating plan, and use of funds.
- Material customer, vendor, licensing, debt, and contractor agreements that already exist.
- Written disclosure of threatened claims, regulatory inquiries, or known disputes.
Add at seed
- Board and stockholder consents or minutes relevant to financing, equity, debt, and major contracts.
- Equity plan, grant records, and the latest valuation used for option pricing, if applicable.
- Monthly financial statements and revenue detail that reconcile to the traction claims.
- Cohort, retention, pipeline, unit-economics, and customer-concentration support.
- Employment and contractor templates, plus records for material departures or disputes.
- Material customer and vendor contracts, privacy terms, security policies, subprocessor list, and incident history.
- Insurance coverage, licenses, permits, and tax filings relevant to the business.
Add for regulated, security-sensitive, hardware, or IP-led companies
- Required licenses, approvals, studies, filings, and regulator correspondence.
- Patent applications, assignments, licenses, and specialist IP analysis where the thesis depends on them.
- Security assessments, penetration-test results, remediation status, and material incident records.
- Architecture, validation, reliability, or technical-review materials tied to the core claim.
- Manufacturing, supply, quality, warranty, and environmental records relevant to delivery.
The company may have legitimate reasons to limit personal data, customer-confidential material, source code, or privileged legal advice. A summary, redacted record, counsel confirmation, or staged access can answer the risk without collecting information you do not need.
Red flags versus acceptable uncertainty
Red flags concern truth, ownership, authority, or a risk that can kill the company. Early-stage uncertainty concerns a future the team has not proven yet. Keep those categories separate.
Pause and investigate when you find:
- Core metrics, contracts, customer status, or founder history that change across sources.
- A cap table that does not reconcile or undisclosed securities, debt, promises, or side letters.
- Unclear ownership of core IP or missing assignments from a founder or material contributor.
- An unresolved co-founder equity, authority, or commitment dispute.
- Refusal to share the basic evidence needed to understand cash, ownership, terms, or material obligations.
- A claimed license, security control, patent, customer, or approval that does not exist.
- Financing documents whose economics differ materially from the pitch.
- Undisclosed lead, syndicate, introducer, or affiliate conflicts and fees.
- Unexplained wire-recipient changes or last-minute payment instructions.
Uncertainty can be acceptable when:
- A pre-seed company has no revenue, yet customer discovery and product learning are specific and documented.
- Unit economics are immature, and the team knows what it can and cannot measure.
- The product has rough edges, while users still reach a valuable outcome and the team ships quickly.
- One executive role remains open, with a credible owner and hiring plan.
- A process or folder is messy, while the underlying records reconcile and the team fixes gaps promptly.
- The precise exit buyer and timing are unknowable, while credible exit paths and return economics exist.
An unresolved red flag can lead to a pass or a wait. A known weakness can still fit an invest decision when you understand its impact, the team is candid, and the rest of the case compensates for it.
One-page investment memo template
Complete this before you send funds. Keep claims and evidence next to each other.
- Deal snapshot
- Company, date, stage, round size, instrument, valuation cap or price, source, your role, and proposed check.
- Decision
- Invest
- Pass
- Wait until: [specific evidence or milestone]
- One-sentence reason
- We will [invest/pass/wait] because [decisive reason].
- People
- Founder-market fit:
- Execution and learning evidence:
- Co-founder and role risk:
- Reference findings:
- Product and market
- Customer and pain:
- Product evidence:
- Market wedge and competition:
- Security, technical, or IP risk:
- Traction and GTM
- Metrics verified:
- Retention or customer evidence:
- Distribution thesis:
- Paperwork and economics
- Cash, burn, runway, and milestone:
- Cap table and expected dilution:
- Key terms, side letters, and preferences:
- Legal, regulatory, contract, and tax issues routed for qualified review:
- Return and portfolio fit
- Credible exit paths:
- Conservative return scenario:
- Concentration and opportunity cost:
- Alignment and conflicts
- Founder goals and investor expectations:
- Lead or SPV fees, carry, rights, allocation, and conflicts:
- What remains uncertain
- Acceptable unknowns:
- Blocking issues and owner:
- Final instruction
- Amount:
- Conditions before signing or funding:
- Wire details confirmed by and on:
If you want a longer version for an investment committee or syndicate, adapt our investment memo template. The one-page version is enough to preserve what you believed, what you verified, and why you acted.
FAQ
What is due diligence in angel investing?
It is the process of testing a startup's important claims across people, product, and paperwork before deciding whether to invest. The goal is to understand and choose risk. Uncertainty will remain.
How long does angel due diligence take?
We use two weeks as an illustrative starting point for a focused early-stage process. A small follower check with credible lead work may take less time. A lead investment or a company with regulatory, technical, security, IP, or legal complexity may take longer. Set the scope and decision date before you start.
What documents should an angel investor request?
At pre-seed, start with formation and governing documents, the cap table, outstanding securities, financing documents, founder equity and vesting records, IP assignments, basic cash and runway data, and any material contracts or disputes. Add operational, financial, governance, security, regulatory, and option records as the company matures or the risk requires them.
Do angel investors sign NDAs?
Some do, particularly when later-stage diligence or sensitive technical, customer, or regulated information requires one. A founder may decline an NDA for an initial pitch. Request only the information needed for your decision, protect what you receive, and use counsel when confidentiality terms or competitive conflicts matter.
Can I rely on a lead investor's due diligence?
You can use it, but you still own your decision. Understand what the lead checked, where it relied on management, how its check and rights compare with yours, and what fees or conflicts affect the recommendation. Verify the claims that matter most to your thesis.
When should I involve a lawyer or tax professional?
Bring in qualified counsel when you cannot confidently explain the financing instrument, ownership, corporate approvals, IP, contracts, regulatory exposure, or investor rights. Use a qualified tax professional for the investment's tax treatment and your circumstances. A checklist cannot replace either review.
Good diligence improves through repetition, written decisions, and candid feedback. If you want to practice those habits with our investor community and learn from our approach to evaluating startups, apply to Angel Squad.











