
Why do LPs re-up? Inside the decision to back another fund
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
An LP can trust a venture manager and still decline the next fund. Another may re-up before the first fund has returned much cash. The decision combines what the manager has proved with what fits the LP’s portfolio today. That distinction explains why the same performance report can produce a yes, a smaller check, or a no.
What an LP re-up means
A limited partner (LP) is an investor that commits capital to a venture fund. The general partner (GP) manages the fund, selects investments, and calls the committed capital over time under the fund documents.
A re-up is a new commitment from an existing LP to a later fund run by the same manager. The new commitment does not extend the old fund. It puts fresh capital into a separate vehicle with its own strategy, size, terms, team, and portfolio.
That makes a re-up different from backing a new manager. An existing LP has firsthand evidence: capital calls, reports, portfolio marks, realized distributions, strategy changes, and the GP’s behavior when an investment struggles. Familiarity can reduce diligence work, but it should never make the next commitment automatic.
Capital is concentrating among established managers. In the first half of 2026, US venture firms raised $72.4 billion across 405 funds, and established firms took 89% of that capital, according to the PitchBook-NVCA Venture Monitor. The report does not identify how much came from re-ups. It does show that LP capital has concentrated around managers with an existing record.
Why LPs re-up
Most yes decisions rest on two separate findings. The LP still believes in the manager, and another commitment fits the LP’s own portfolio. Five factors usually shape those findings.
1. The evidence supports the investment case
Mature funds give LPs realized evidence. Distributions to paid-in capital (DPI) equals cumulative distributions divided by contributed capital. Those distributions may be cash or securities. Total value to paid-in capital (TVPI) adds the reported remaining value of the fund’s investments to distributions, then compares that total with paid-in capital.
DPI shows what has come back. TVPI includes unrealized value, so valuation policy and the quality of the remaining portfolio matter. Our TVPI and DPI guide explains why two funds with similar headline multiples can present very different evidence.
Venture timing complicates the decision. Cambridge Associates found that earlier-stage venture funds in its historical sample typically needed seven to nine years to settle into their final performance quartile. Re-up decisions usually arrive sooner. LPs therefore examine realized performance, current marks, investment-level progress, losses, and whether results came from the stated strategy.
2. The manager’s edge appears repeatable
The original guest perspective behind this post came from investor and podcast host David Weisburd. He framed a venture manager’s edge through three abilities:
- Sourcing: The manager consistently sees enough high-quality, thesis-matched opportunities.
- Picking: The investment process selects companies with attractive potential at the offered price and terms.
- Winning: The manager earns allocation in the deals it wants and can build the portfolio it promised.
This is a useful lens, rather than a complete re-up model. An LP still has to connect each claimed edge to evidence. Follow-on rounds and prominent co-investors may signal outside conviction or access. They do not prove that the fund will return capital, that current marks are durable, or that the process will repeat.
Sourcing also has to last beyond one network or market cycle. That is why LPs ask where deal flow comes from, how opportunities are screened, and which partner made each decision. We cover those questions in what LPs ask fund managers.
3. The GP did what it said it would do
An LP underwrote a specific strategy. Material changes to stage, sector, geography, check size, ownership targets, reserves, or portfolio size create a new risk question, even when the first fund looks healthy.
Consider a manager that promised concentrated pre-seed investing and then raised a much larger successor fund. The LP needs to know whether the manager can deploy the extra capital without moving later, paying higher prices, or making more investments than the team can support. Strategy can evolve, but the new model needs its own evidence. Our guide to evolving a fund thesis shows how those changes affect the investment case.
4. The people and incentives still line up
Fund performance belongs to people, processes, and incentives. An LP asks who sourced and led the strongest investments, whether those people remain, how decisions are made, and what happens if a key partner leaves.
The review also covers fees, carried interest, GP commitment, governance, conflicts, valuation practices, and reporting. A familiar manager can lose a re-up after a major team departure, a weak succession plan, unexplained term changes, or repeated surprises. ILPA’s standard due diligence questionnaire devotes separate sections to strategy changes, track record, succession, governance, valuation, and reporting for this reason.
5. The commitment fits the LP’s portfolio now
Every re-up competes with other uses of finite capital. As our co-founder and general partner Elizabeth Yin writes, “Decisions are never in isolation - they are a comparison game.”
An LP compares the manager with other venture funds, other private-market strategies, liquid assets, and the need to reserve cash for capital calls. It also checks sector, geography, vintage year, and manager concentration. A fund can clear the manager test and still fail the portfolio-fit test.
Why LPs do not re-up
A no can reflect lost conviction, a portfolio constraint, or both. Treating every decline as a verdict on the GP leads to the wrong lesson.
Performance or execution weakened conviction
The clearest decline happens when results and process both disappoint. Warning signs include losses outside the stated risk budget, unsupported marks, inconsistent attribution, poor reserve decisions, or a portfolio that no longer resembles the strategy the LP approved.
Weak DPI alone is not always decisive for a young venture fund. Weak DPI combined with deteriorating portfolio evidence, unexplained strategy drift, and little proof of a repeatable edge is a much harder case to defend.
The successor fund changed too much
A larger fund may need different deal sizes, stages, or ownership. A new strategy may require skills the current team has not demonstrated. New terms may shift economics or governance away from the LP.
The LP is evaluating the proposed fund, rather than grading the predecessor in isolation. A good Fund I can still be weak evidence for a very different Fund II.
Team or trust changed
Key-person departures, unclear succession, turnover below the partner level, weak reporting, valuation surprises, or unmanaged conflicts can stop a re-up. These issues affect the LP’s confidence that prior results belong to the team that will manage the new vehicle.
Trust matters most when the data is incomplete. If the manager has been candid about write-offs, delays, and changes, the LP has a better basis for judgment. This is an input to the LP’s decision. Our separate fund-manager re-investment guide owns the communication and relationship tactics for earning another commitment.
Liquidity and pacing leave no room
Private funds create obligations long before they create cash returns. An unfunded commitment is capital the LP has promised but the GP has not called yet. Net asset value (NAV) is the reported value of the fund’s assets minus its liabilities at a given date.
An LP may already have high NAV and large unfunded commitments across prior vintages. If distributions arrive slowly, a new commitment can push the portfolio above its target or leave too little liquid capital for future calls. NEPC’s 2025 pacing analysis found that extended fund lives, elevated NAV, and lower venture distributions were reducing modeled capacity for new commitments.
That produces a frustrating but rational answer: strong manager, no room. The LP may re-up at a smaller amount, postpone the decision, or decline.
The LP changed
An LP’s mandate, leadership, investment committee, staffing, risk limits, or target allocation can change between funds. A family office may need cash for another business. An endowment may reach its venture cap. A new chief investment officer may consolidate managers. A fund-of-funds may lose an underlying investor.
The GP can perform well and still fall outside the LP’s current plan. The decline says what fits today, not necessarily what the LP thinks of the manager forever.
A practical yes-or-no re-up framework
A repeatable process keeps one exciting company, one painful write-off, or one relationship from controlling the whole decision. Elizabeth Yin puts the learning point plainly: “The more disciplined you are in your thought process/rubric, the more you can improve over time.”
Use three gates in order.
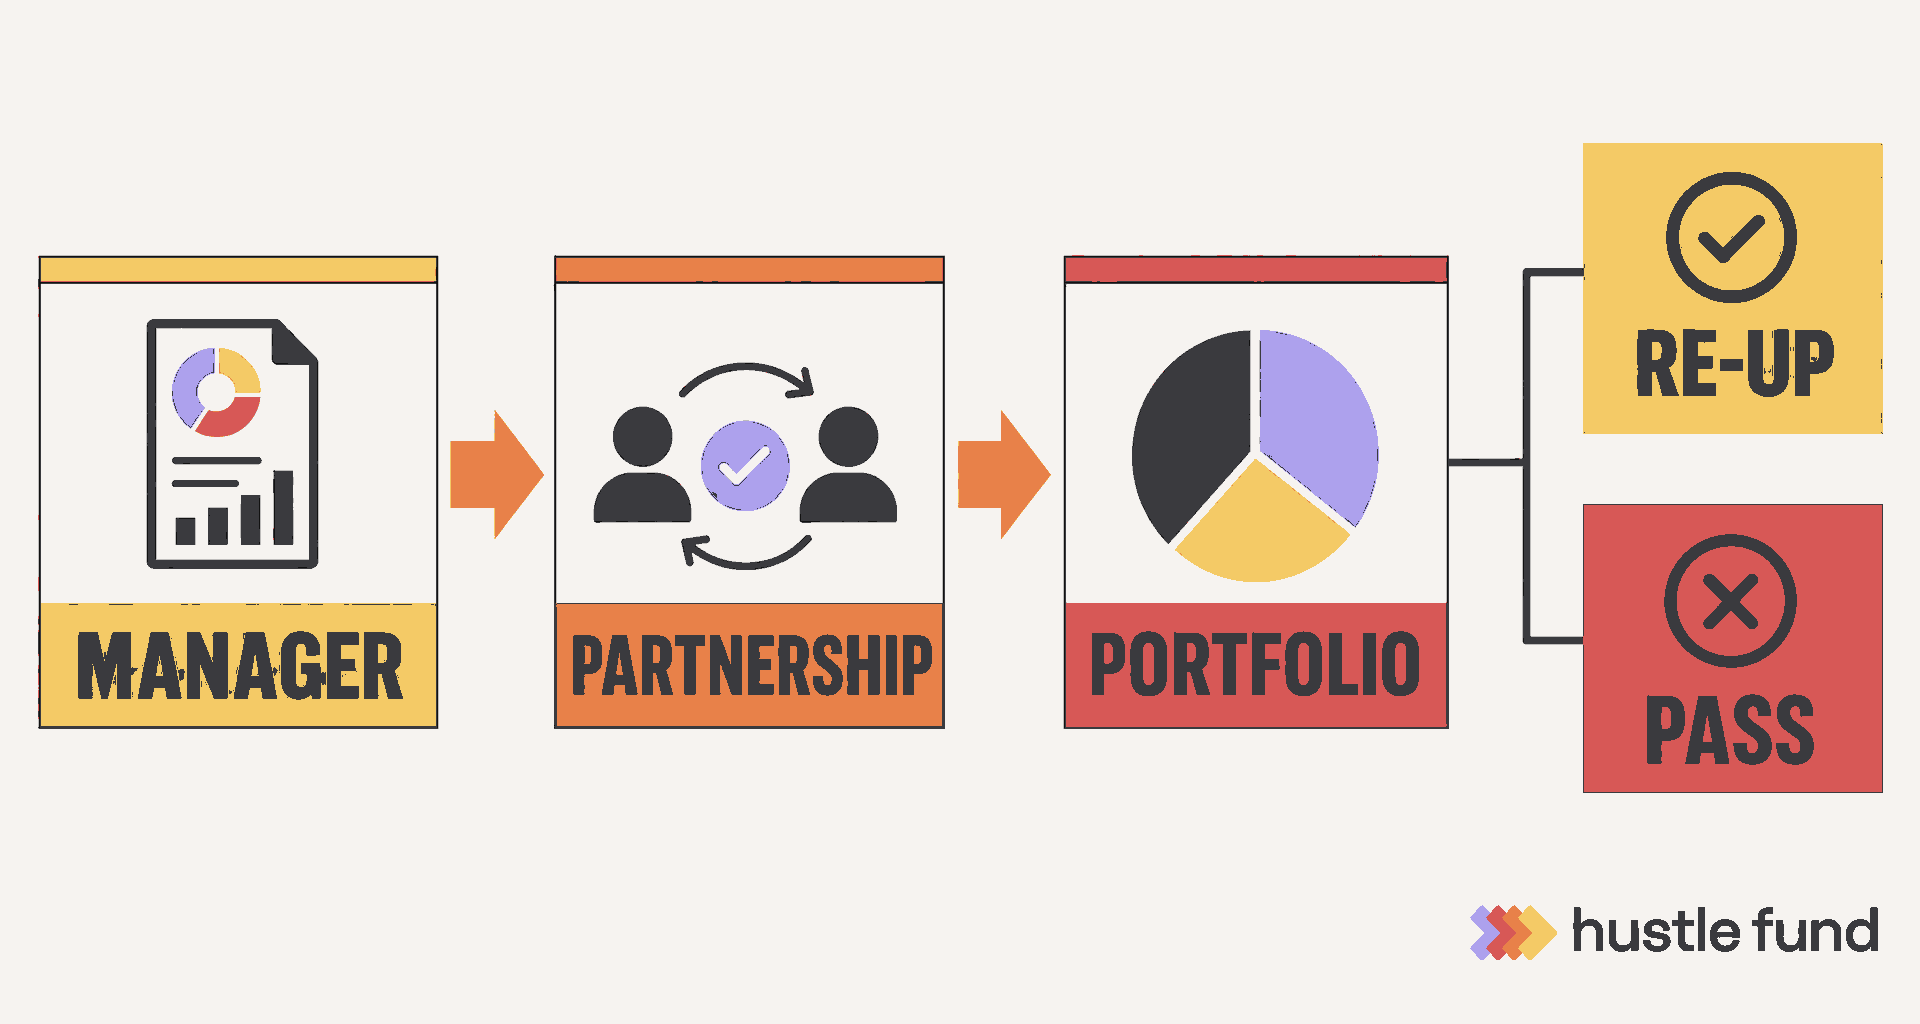
Gate 1: Is the manager case still strong?
- Compare the original thesis with actual investments, check sizes, stages, reserves, and portfolio construction.
- Separate realized distributions from unrealized marks and review valuation policy.
- Attribute sourcing, investment decisions, board work, and outcomes to the people who will remain.
- Test sourcing, picking, and winning against evidence from the portfolio and current opportunity set.
- Decide whether the proposed fund size and strategy can preserve the edge.
A no here means decline. More portfolio capacity cannot fix a manager case that no longer works.
Gate 2: Is the partnership still investable?
- Review team continuity, succession, decision rights, and key-person provisions.
- Compare fees, carry, GP commitment, governance, conflicts, and reporting with the prior fund.
- Examine how the GP handled write-offs, valuation changes, capital calls, and difficult disclosures.
- Confirm that the LP can explain the fund’s risks and role to its own investment committee.
A no here also means decline until the concern is resolved. Strong early marks do not cancel misalignment or weak governance.
Gate 3: Does this commitment fit the portfolio today?
- Model NAV, expected capital calls, unfunded commitments, distributions, and liquid reserves across scenarios.
- Check target allocation, manager concentration, sector exposure, vintage pacing, and policy limits.
- Compare the re-up with new managers and other available uses of capital.
- Confirm staff and investment-committee capacity to complete diligence on schedule.
A yes across all three gates supports a re-up. The LP should size the commitment separately. A no at Gate 3 can support a smaller check or a pass caused by capacity, while preserving conviction in the manager.
Early fund data needs humility
LPs often decide while the previous fund is still young. A Cambridge Associates study of 2,606 private funds found that 85% moved through three or four performance quartiles when measured by internal rate of return before settling. Young rankings can swing dramatically.
Venture manager performance still showed persistence in a 2023 academic study using institutional cash-flow data. Yet the interim performance visible during fundraising was only moderately correlated with final performance. Track record deserves weight. Early marks do not deserve blind faith.
The same balance appears in ILPA’s 2025–26 survey of 99 senior private-equity investment professionals. Respondents ranked long-term track record, a repeatable source of excess performance, and alignment above short-term track record and DPI when deciding whether to bring an opportunity to investment committee. ILPA defined private equity broadly for the survey, including buyout, growth, and venture capital.
This is why good re-up diligence combines fund metrics with the organization, strategy, attribution, terms, and the LP’s own capacity. One number cannot carry the decision.
Build the judgment behind the check
If you want more reps evaluating early-stage companies, comparing notes with experienced operators, and building a consistent investment rubric, apply to Angel Squad. Joining the community does not require accredited-investor status, while investing in relevant offerings does. Membership does not guarantee allocation, returns, or success.
Venture funds and startup investments are speculative, illiquid, and long term. Investors can lose all committed capital, and many startups fail. Past results and current marks do not guarantee future results. Actual outcomes depend on the governing documents, fees, carried interest, taxes, cap tables, valuation policies, and timing. This material is educational and is not investment, legal, tax, accounting, or valuation advice. Review the fund and subscription documents and seek advice from qualified independent professionals.











