
Venture Capital No Shop Clause: What to Know
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A signed term sheet starts a sensitive stretch of a venture deal. The investor is spending time and money on diligence and documents. The founder may still be filling the round. A no shop clause can protect the path to closing, but vague scope or heavy-handed enforcement can stall the raise and damage trust. Investors need to know what the clause covers and when exclusivity earns its cost.
What is a no shop clause?
A no shop clause is a term that stops a company and, often, its founders from soliciting or negotiating competing financing offers for a defined period. You may also see it called a no shop agreement, no shop provision, or exclusivity clause.
The clause usually appears after an investor offers a venture capital term sheet. It gives the investor time to finish diligence, negotiate definitive documents, and move toward closing without the company using that offer to secure a different lead or better terms elsewhere.
Most economic provisions in a term sheet express intent rather than create a final investment obligation. A no shop can be binding when the document says it is. The 2020 NVCA model term sheet, for example, treats its combined no-shop and confidentiality provision as binding while leaving the exclusivity period as a blank for the parties to negotiate. NVCA maintains its current Model Legal Documents separately. Read the current materials with qualified counsel, since the 2020 term sheet illustrates one drafting approach rather than a current market standard.
Signing a term sheet does not necessarily commit the investor to fund. Signing its no shop can still limit the company’s fundraising. Investors should request only the scope and time their closing process can justify.
Why VCs request a no shop clause
A lead investor may spend meaningful time and money after a term sheet is signed. The work can include customer calls, legal and financial diligence, partnership approval, allocation discussions, and drafting definitive documents. Exclusivity lowers the risk that this work becomes free price discovery for a competing lead.
The clause can also simplify the closing process. Both sides know which deal they are trying to complete, who is setting the terms, and which open issues need an answer. That focus is especially useful when the investor is leading the round or writing a check that anchors it.
Early-stage rounds are often active when a term sheet arrives, and one lead check may leave room for angels or other participants. A broad clause can freeze those conversations. A long clause can leave the company stranded if the investor later walks away.
Our co-founder and general partner Elizabeth Yin writes in Democratizing Knowledge, “At the end of the day, money is a commodity.” The relationship and the investor’s conduct start differentiating the offer immediately. A clear, narrow no shop can build confidence. An investor who demands exclusivity and then moves slowly signals the opposite.
What a no shop clause restricts
The signed words control. Do not rely on a verbal understanding of what “shopping” means.
A venture no shop may restrict the company and founders from:
- soliciting a new lead investor or competing term sheet;
- initiating or encouraging negotiations over a different price, valuation, or structure;
- accepting a competing offer during the exclusivity period;
- circulating the signed term sheet to create a bidding contest; or
- assisting a third party with a proposal covered by the clause.
Some forms reach beyond financing and also cover a sale, license, or other disposition of the company or material assets. That broader scope deserves explicit business and legal review. An investor seeking financing exclusivity should be able to explain why any strategic-transaction restriction belongs in the same clause.
Permitted actions need explicit carve-outs
A carve-out is a written exception to the restriction. When a lead check does not fill the round, useful carve-outs may let the founder:
- continue discussions with angels and non-lead investors on the agreed terms;
- accept additional participants in the same financing;
- respond to unsolicited inbound interest without negotiating a competing lead or new terms;
- share information with the board, existing stockholders, lawyers, accountants, and other named advisers; and
- continue ordinary-course commercial or strategic conversations that are outside the clause.
The notice requirement also needs precision. A clause may require the company to tell the lead about every third-party inquiry, even when the founder did not solicit it. Define what must be reported, to whom, and how quickly.
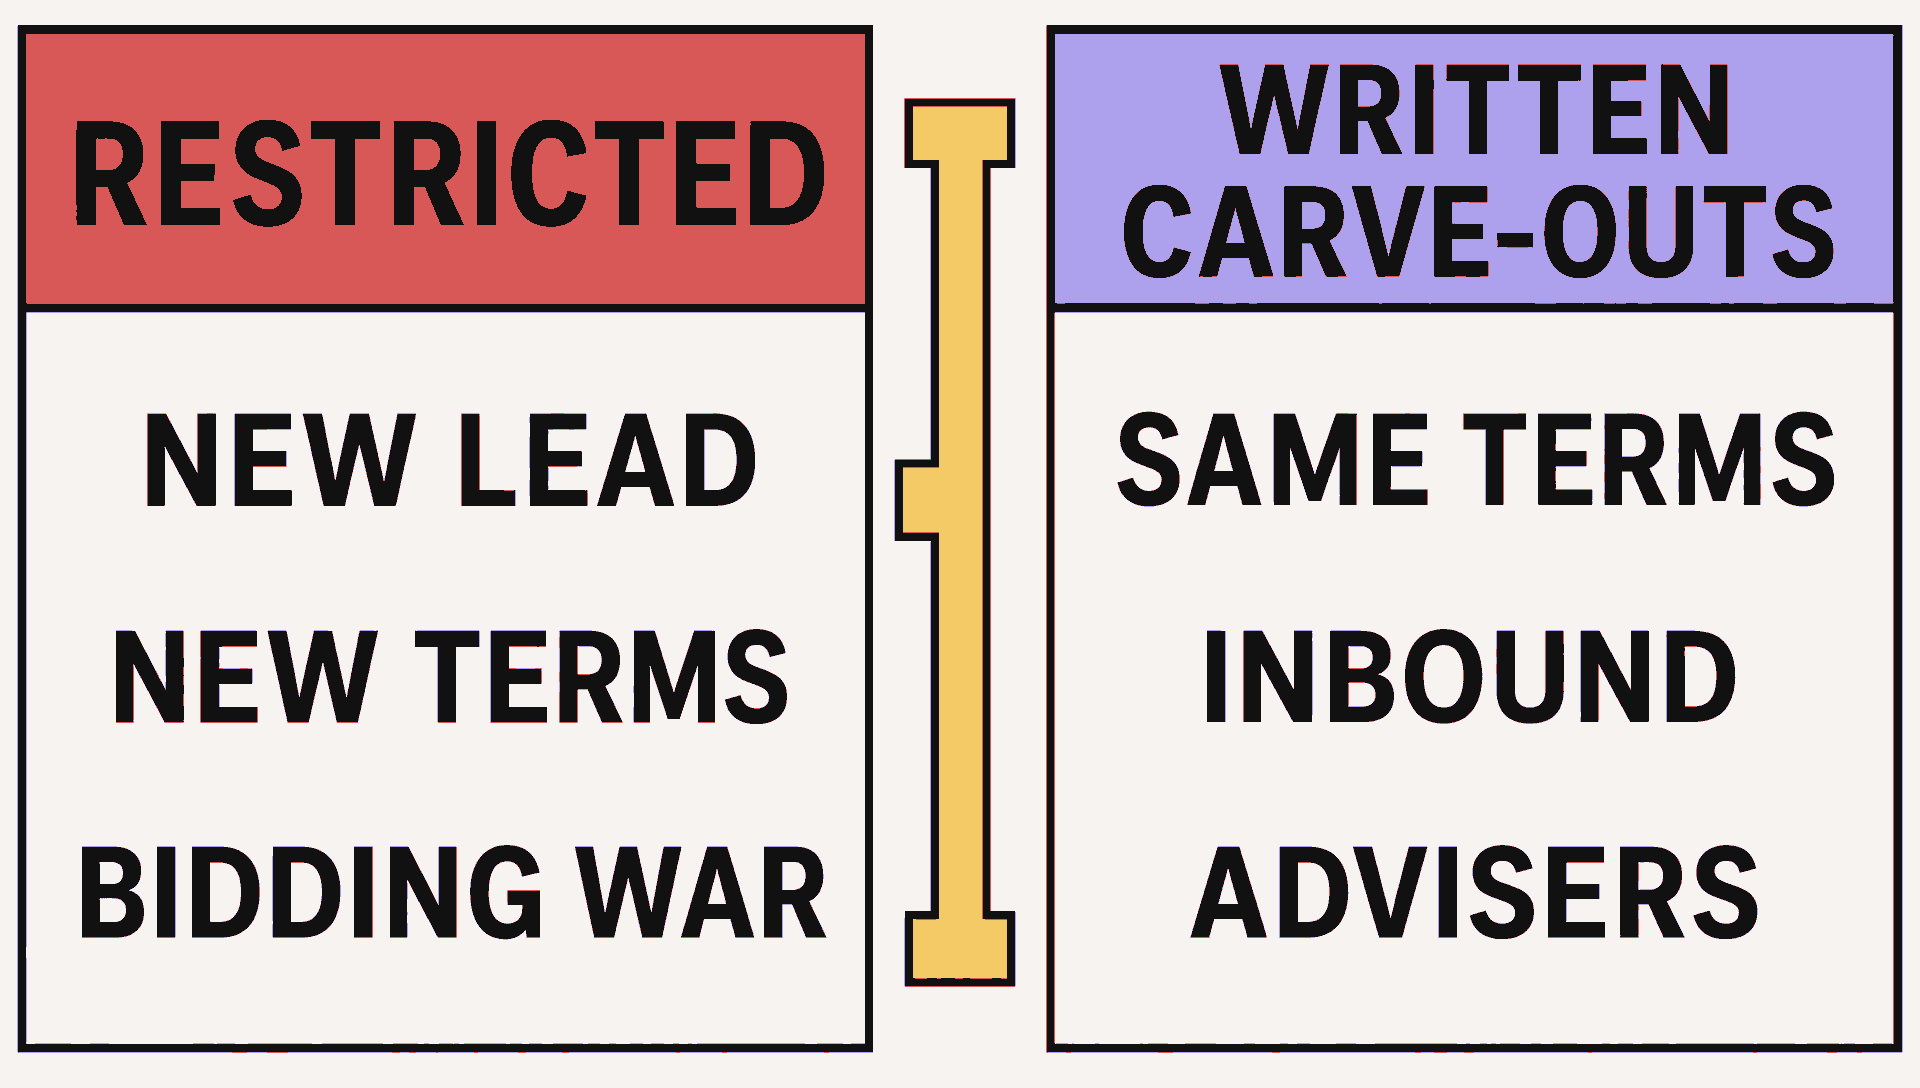
“We both know you can keep filling the round” is weak protection for both sides. Put the permitted categories in the term sheet. Written boundaries let the investor protect a lead position while the founder keeps the agreed financing moving.
Set a deal-dependent duration
There is no universal no shop period for every venture deal. The appropriate timing depends on the work remaining, the parties’ roles, the financing structure, and the conditions to closing. The 2020 NVCA model term sheet leaves the number of days open rather than declaring one standard.
Set the period after answering five questions:
- What diligence remains? List the legal, financial, technical, customer, and partnership work that must finish.
- Who controls the timeline? Separate investor work from third-party items and company deliverables.
- How much of the round is covered? A lead financing the round has a different case for exclusivity from a small participant.
- What may continue? State the investor conversations, inbound contacts, and same-terms participation that remain permitted.
- How does the period end? Use a clear start time, expiration time, and extension process.
Automatic extensions can turn a short restriction into an open-ended one. If the investor needs more time, the parties can discuss the reason and document new consent. Company and investor counsel should review the final duration, triggers, and extension language under the governing law.
What happens if a no shop clause is breached?
A suspected breach can end the deal because it undermines the premise of exclusive negotiations. It does not create one automatic consequence across every financing.
The term sheet may let the investor stop negotiations. It may include expense reimbursement, a negotiated fee, injunctive relief, or other remedies. Those consequences apply only as the signed language and governing law allow. A breakup fee is not an automatic feature of every venture no shop.
Use a proportionate response:
- Read the exact clause. Identify the covered conduct, carve-outs, notice duty, dates, and named parties.
- Establish the facts. An unsolicited email is different from a founder asking another fund to beat the signed terms.
- Talk promptly. A candid conversation may reveal ambiguity, a missed notice, or conduct that can stop without derailing the financing.
- Choose the narrowest effective response. That may be a clarification, written waiver, revised carve-out, short extension, or a decision to end the deal.
- Use counsel for remedies. Qualified lawyers should assess enforceability, available relief, and securities or fiduciary issues in the relevant jurisdiction.
Proportionate enforcement protects the process without turning every unclear inbound conversation into a threat. It also preserves information. If a founder felt forced to hide an inquiry, the investor should ask whether the clause or the communication around it caused that incentive.
Confidentiality agreement vs. no shop clause
These provisions often sit together in a term sheet, but they do different jobs.
- A no shop clause controls conduct. It limits solicitation, negotiation, acceptance, and other specified activity involving competing offers.
- A confidentiality provision controls disclosure. It limits who can see the term sheet, its terms, or other protected information.
A founder could keep the term sheet confidential and still violate a no shop by privately negotiating with another lead. The reverse is also possible: a permitted disclosure to a lawyer or board member may comply with the confidentiality carve-out and have nothing to do with shopping the deal.
Read both sections together. Confirm who may receive the terms, whether potential same-round participants need the lead’s consent, and whether consent may be withheld or delayed. The combined language should let the company obtain advice and close the agreed financing without creating a loophole for competing negotiations.
When a no shop clause may be unnecessary
Exclusivity should solve a real process risk. It may add little when:
- the investor is writing a small check and is not leading or setting terms;
- the company is accepting separate Simple Agreements for Future Equity (SAFEs) without one lead or shared closing process;
- the investor has completed its work and there is no meaningful gap between signing and funding; or
- the requested restriction would burden the active round more than it protects the investor’s remaining work.
Declining a no shop is not automatically a founder red flag. Ask what the founder needs to keep doing, why the investor needs protection, and whether a narrower clause can satisfy both.
As Elizabeth writes in Democratizing Knowledge, “Going back to first principles is super important since the market always changes and evolves.” Apply that discipline here. Boilerplate is a starting point. The investor’s role, work, and actual exposure decide whether exclusivity belongs in the deal.
Investor checklist before requesting exclusivity
Before sending the term sheet, confirm that you can answer each item in plain language:
- Purpose: What specific time, expense, or closing risk does exclusivity protect?
- Scope: Which financings, asset transactions, people, and actions are restricted?
- Carve-outs: Can the founder keep filling the round on the agreed terms, handle inbound interest, and consult advisers?
- Timeline: What work will you finish during the period, and who owns each step?
- Notice: Which inquiries must the company disclose, and when?
- Exit: What ends the clause early if the investor stops pursuing the deal?
- Extension: Does more time require written consent?
- Consequences: What remedies are actually written, and are they proportionate?
- Confidentiality: Who can receive the term sheet and support the closing?
- Legal review: Have qualified counsel for the relevant parties and jurisdiction reviewed the binding terms?
The discipline runs both ways. If an investor asks a founder to stop seeking alternatives, the investor should move with the urgency the clause demands.
No shop clause FAQ
Is a no shop agreement legally binding?
It can be. Many term sheets say their economic terms are non-binding while making no shop and confidentiality provisions binding. The exact document and governing law control, so qualified counsel should review the clause before signature.
Can a founder keep raising during a no shop period?
Only to the extent the signed clause permits it. A written carve-out can allow conversations with non-lead investors, participation on the agreed terms, and a defined response to inbound interest. Without that language, the founder should not assume those actions are allowed.
How long should a no shop clause last?
Long enough for a defined, credible path to closing and no longer than the parties can justify. Diligence scope, financing complexity, investor role, open conditions, and explicit carve-outs all affect the answer. There is no universal number for every deal.
Does a breach automatically trigger a breakup fee?
No. A fee or expense payment depends on the signed language and applicable law. An investor may instead stop the deal, grant a waiver, revise the clause, or pursue another available remedy after qualified legal review.
Make exclusivity a judgment call
You learn terms faster when you see how they change incentives in a live deal. Our investor community reviews startup opportunities, compares diligence, and learns from our approach to early-stage investing. If you want to build that judgment with experienced peers, apply to Angel Squad.
This content is for educational purposes only and does not constitute legal, tax, or investment advice. Deal terms, enforceability, remedies, and securities obligations depend on the facts, documents, jurisdiction, and parties. Obtain independent review from qualified legal, tax, and investment professionals before signing or acting on any financing document.











