
Fund Manager Due Diligence: Questions LPs Ask
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Fund manager due diligence is how a limited partner (LP) tests a manager’s story before committing, using documents, data, references, and operating behavior.
This framework adapts institutional practices for emerging venture managers. A first-time fund may lack predecessor-fund reports or history. The Institutional Limited Partners Association (ILPA) acknowledges that gap in its due diligence questionnaire (DDQ) user guide. A missing item is a question to resolve.
Fund manager due diligence checklist
Use these questions as a first pass for manager selection due diligence. Each answer should lead to evidence you can inspect.
- Strategy: What will the fund invest in, and why does this team have a repeatable edge there?
- Track record: Which investments did each person source, select, support, and exit?
- Team: Who makes decisions, and what happens if a key person leaves?
- Portfolio construction: Do check sizes, pace, reserves, and concentration fit the fund size?
- Terms: How do fees, expenses, carried interest (the manager’s share of eligible fund profits, often called carry), the general partner (GP) commitment, and extensions affect alignment?
- Governance: How are conflicts, allocations, and exceptions handled?
- Operations: Who controls cash, accounting, valuation, reporting, and sensitive data?
- References: Do founders, co-investors, LPs, and service providers confirm the manager’s claims?
The ILPA DDQ 2.0 is much longer. Its categories are useful even when you do not need a full institutional questionnaire.
1. Is the strategy specific enough to test?
Start with the proposed fund. Record its stage, sectors, geography, initial check range, target pace, planned portfolio count, reserve policy, concentration limits, and target fund size.
Then test whether those parts fit together. A manager planning 35 initial checks, selective follow-ons, and a meaningful reserve pool needs a fund size that can support all three after fees and expenses. If the math only works when every check lands at the bottom of the stated range, the plan is already strained.
The manager’s edge should also produce observable behavior. Ask for:
- deal sources by channel, such as founders, operators, other investors, events, or inbound content;
- examples of deals the fund won when founders had other credible options;
- deals the team passed on, the reason for each pass, and what happened next;
- founder references that can describe support after the check; and
- evidence that the source can keep working after the manager’s immediate network is exhausted.
A network is a starting point. A repeatable deal-flow system is an operating process. LPs should be able to see how the manager’s fund differentiation helps the team source, win, and support the companies the strategy calls for.
Public writing can help an LP assess whether a GP’s beliefs are specific and consistent over time. As our co-founder Elizabeth Yin wrote, “Blogging and tweeting really works.” Treat that body of work as evidence of beliefs, never as proof of investment results.
2. Who created the track record?
A polished headline return can hide the decisions that produced it. Ask for a complete investment history, including gains, losses, write-offs, and holdings that remain unrealized. Every performance set should state its as-of date and distinguish gross investment results from the net result experienced by LPs.
Gross multiple on invested capital (MOIC), explained in our MOIC guide, measures investment value relative to investment capital before fund-level fees, expenses, and carry. Net total value to paid-in capital (TVPI) compares an LP’s distributions plus remaining value with that LP’s paid-in capital after fund economics. They answer different questions.
For a spinout or a manager presenting deals from a prior firm, establish attribution investment by investment:
- Who originated the relationship?
- Who led diligence and made the recommendation?
- Who sat on the board or supported the company?
- Who influenced follow-on and exit decisions?
- Does the prior firm agree with the attribution?
Request the cash flows or records that support the calculations. ILPA’s performance template offers a consistent way to connect metrics with contributions and distributions. The U.S. Securities and Exchange Commission (SEC) described examination findings in its 2022 risk alert that included cherry-picked or stale track records, omitted fee and expense effects, and unsupported predecessor performance.
An early portfolio will contain paper marks and may have little realized evidence. That is normal for venture, and it puts more weight on attribution, valuation discipline, and candor about losses.
3. Can the team execute without a fragile key person?
Map the real work behind the titles. Who sources, screens, leads diligence, makes the final call, supports founders, handles follow-ons, manages exits, reports to LPs, and oversees the firm?
For a multi-partner fund, ask how long the partners have worked together and review examples of agreement and disagreement. Decision rights should be clear when the vote is split or one partner has a conflict. Economics and ownership should give the people doing the work a reason to stay.
For a solo GP or small team, concentration is obvious. Ask which responsibilities are delegated, who can keep the fund operating during an emergency, and whether the management company has enough resources for the planned fund. Read the key-person provisions and succession terms in the limited partnership agreement (LPA). A reassuring conversation cannot replace those rights.
Past departures also deserve direct questions. Ask why each senior person left, how deals and carried interest were reassigned, and whether references tell the same story.
4. Does portfolio construction match the fund?
Portfolio construction turns the thesis into capital allocation. It covers the number of companies, initial check sizes, ownership targets, pacing, concentration, and reserves for follow-on rounds.
As Elizabeth Yin puts it, “Portfolio construction is how you win championships.” Her next point matters too: no single portfolio strategy works for every fund. An ownership target that suits a concentrated seed fund may make little sense for a high-volume pre-seed strategy.
Follow-on policy exposes the tradeoffs. Money reserved for an existing company cannot fund a new one. “Decisions are never in isolation - they are a comparison game,” Elizabeth Yin writes. Ask the manager to walk through past follow-on decisions and show what information changed the initial view.
Look for a repeatable process, including who decides, what evidence matters, and how conflicts are handled. Pro-rata rights are negotiated rights to invest in a later financing so an investor can try to maintain its ownership percentage. They do not guarantee an allocation because actual rights and available room depend on the documents and financing terms.
The broader general partner role also matters here. Founder support can improve access to information and future rounds, but LP diligence should verify the work through founders rather than accept a service menu at face value.
5. Do the terms align incentives?
Read the fund documents alongside the pitch. Focus on terms that move money, decision rights, or time:
- the management-fee basis during the investment period and any later step-down;
- organizational, broken-deal, travel, legal, compliance, and other fund expenses;
- the carried-interest waterfall, escrow, and clawback mechanics;
- the GP commitment, including how it is funded;
- recycling of investment proceeds;
- investment-period and fund-term extensions; and
- side letters or other rights that may give certain LPs different economics, information, or access.
The carry waterfall sets when and how the manager receives carried interest. A clawback can require the manager to return excess carry after later losses or expenses. Recycling lets the fund reinvest certain proceeds instead of distributing them, within the limits in the fund documents.
Investor.gov explains that offering documents and agreements govern fees and expenses across a private fund’s life. Read the private placement memorandum (PPM), LPA, subscription documents, and any applicable side letters. Have qualified counsel explain how the provisions work together.
Also ask the manager to show how fees and expenses have been calculated in practice. A clause and an invoice should tell the same story. ILPA’s Principles 3.0 gives LPs a useful reference for fee, clawback, governance, and alignment questions.
6. How does governance handle conflicts?
Emerging managers often run more than one vehicle. Ask how the firm allocates opportunities among the main fund, older or newer funds, special purpose vehicles (SPVs), co-investors, and personal accounts. The allocation policy should cover limited room in a financing, follow-ons, and deals that fit more than one mandate.
Review affiliate relationships and fees. Ask who approves a cross-fund transaction, valuation conflict, extension, strategy exception, or key-person event. If the fund has a limited partner advisory committee (LPAC), read its defined role and confirm that the manager follows its notice, consent, and recordkeeping process.
The SEC’s 2020 risk alert describes examination findings involving undisclosed allocation conflicts, side arrangements, affiliate providers, cross-transactions, and expenses charged contrary to disclosures. These findings give LPs concrete scenarios to test.
Where the manager or its personnel appear in public adviser records, compare the pitch with filings in the Investment Adviser Public Disclosure (IAPD) public database, including registration status, employment history, and disclosed disciplinary events. Registration obligations vary, so the absence of a record is a prompt to understand the structure and applicable regime.
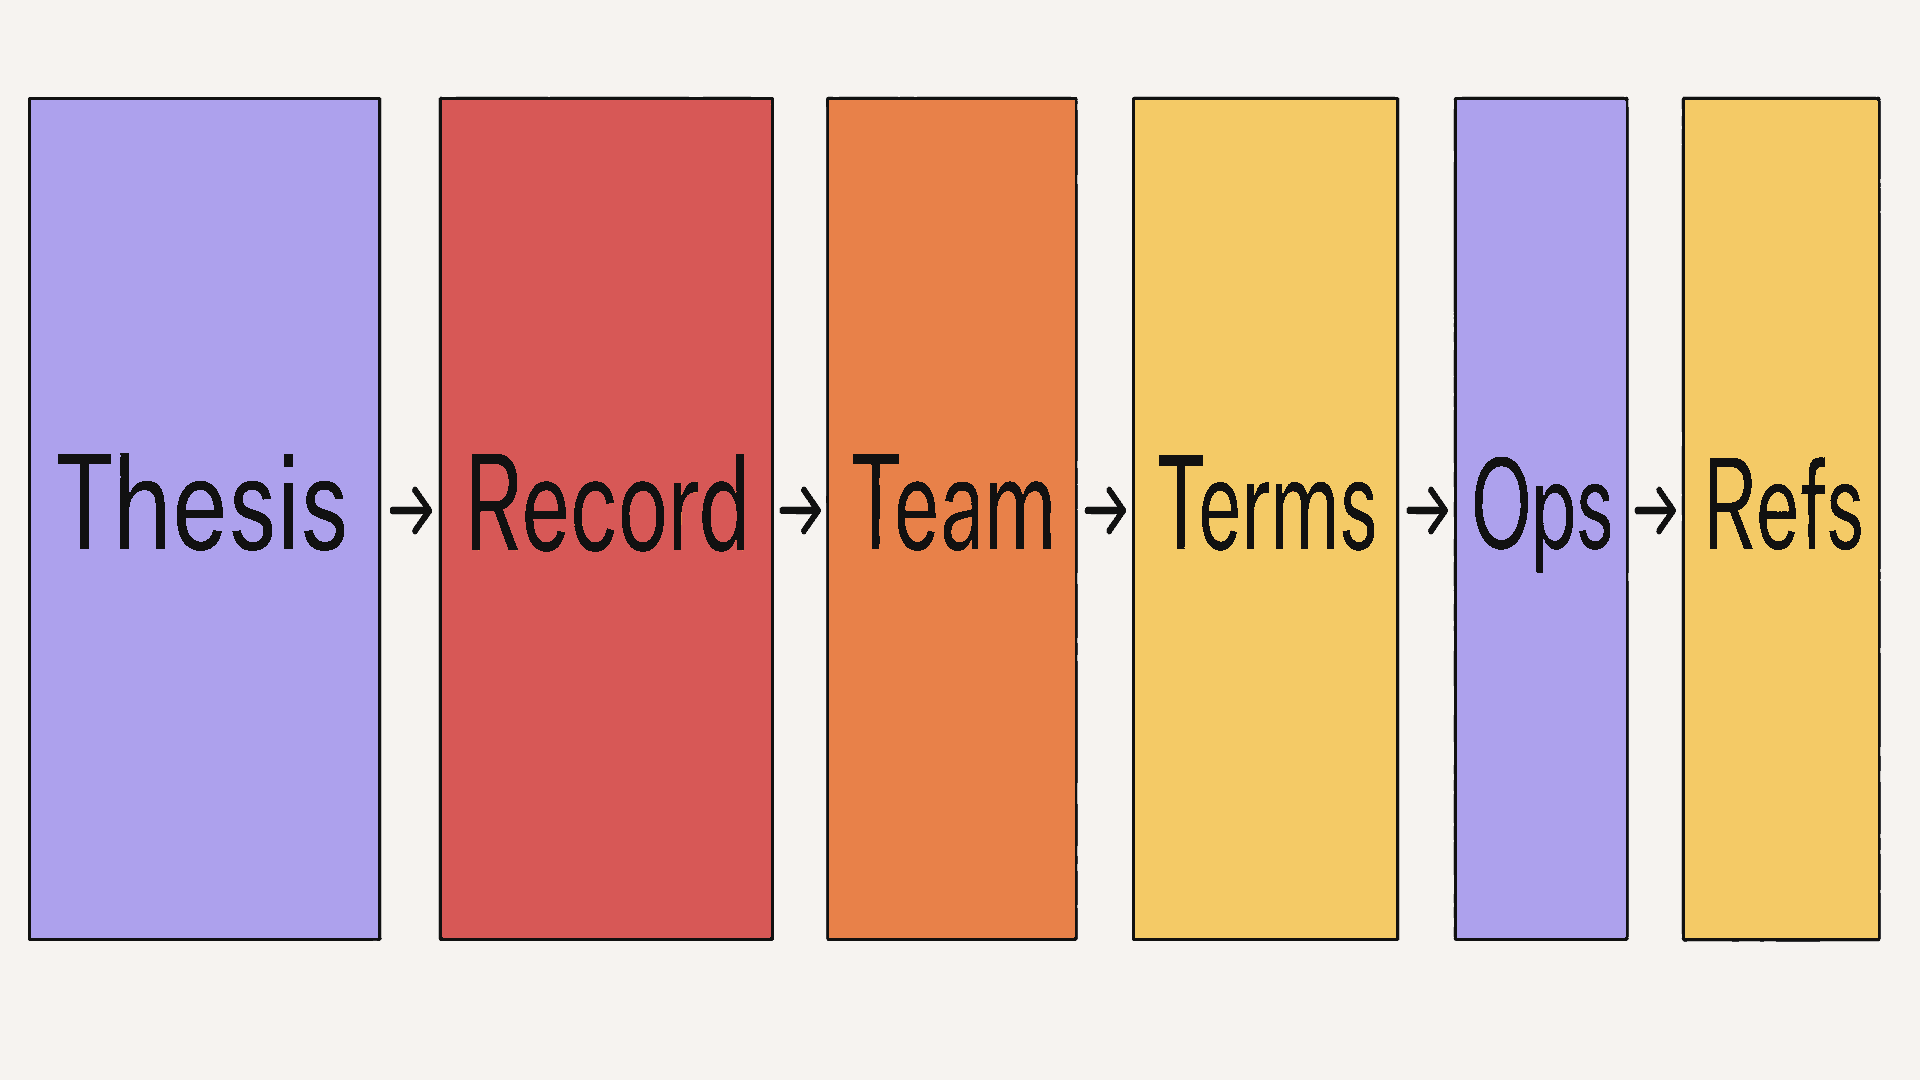
Investment manager due diligence and operational diligence meet here. A six-stage review moves from strategy and track record through the team and terms, then closes with operations and independent references.
7. Can operations protect assets, data, and LP reporting?
Good investments can still sit inside a poorly run fund. Operational fund due diligence checks how cash moves, records are kept, values are set, and LPs receive information.
Identify the fund administrator, bank or custodian where applicable, accountant, auditor, tax adviser, legal counsel, compliance support, and technology providers. Then ask which work remains with the GP and who checks the provider’s output.
Inspect a sample quarterly report, annual financial statements if available, a capital-account statement, and a redacted capital call. Trace one fee or expense from the LPA rule to the administrator’s calculation and the LP report. Ask how corrections are logged and communicated.
The valuation policy should state who prepares marks, who approves them, what evidence is retained, and how conflicts are handled. The International Private Equity and Venture Capital Valuation (IPEV) 2025 guidelines make clear that a recent financing price is not automatically fair value at a later measurement date. Market conditions, company performance, security rights, and other facts can change the estimate.
Security questions belong in the same review:
- Does a wire-instruction change require independent callback verification and two approvals?
- How are access rights removed when an employee or contractor leaves?
- Which vendors can access bank, investor, portfolio, or valuation data?
- Has the firm had a material cyber incident, attempted wire fraud, or data loss, and what changed afterward?
- What is the business-continuity plan if a person, office, bank, administrator, or system becomes unavailable?
- Where is artificial intelligence (AI) used, what sensitive data can it receive, and who reviews its output?
The SEC’s 2026 examination priorities highlight access controls, incident response, vendor oversight, cyber recovery, and supervision of AI use. Those priorities do not create identical duties for every GP. Ask which legal and regulatory duties apply to this manager, then compare its written policies with its operating behavior.
The SEC’s 2023 private-fund rules on mandatory quarterly statements, audits, and preferential treatment were vacated in 2024. Do not treat that package as current law. Contractual promises and other applicable rules still require careful review with counsel.
8. Do references confirm the pattern?
Let the manager explain the strategy first. Then build your own reference list instead of speaking only with the manager’s happiest introductions.
Talk with founders from strong companies and at least one company that struggled, when appropriate. Ask what the GP did after the news became bad, whether promised help arrived, how follow-on decisions were communicated, and whether the GP behaved consistently with its stated values.
Co-investors can speak to judgment, speed, allocation, and conduct in difficult rounds. Existing LPs can speak to reporting quality, surprises, capital calls, and responsiveness. Administrators, auditors, lawyers, or other providers may be able to confirm operating habits within confidentiality limits.
Verify factual claims independently. Match company names and financing dates with source records, trace reported figures to supporting data, and compare references with the manager’s written process. One glowing call proves little. Repeated details across independent sources are more useful.
Fund manager due diligence red flags
A red flag calls for deeper investigation. The most serious patterns are gaps between what the manager says, what the documents permit, and what the firm does.
- Selective track record: Winners are highlighted while losses, write-offs, or less flattering predecessor funds are missing.
- Stale or unsupported figures: Performance lacks an as-of date, cash-flow support, a gross or net label, or clear attribution.
- Expense mismatch: The manager cannot explain who paid an expense or why the allocation matches the LPA.
- Valuation mismatch: The reported mark conflicts with the written policy or relies on an old round without current analysis.
- Hidden preferences: Side-letter, co-investment, or information rights could favor some LPs without adequate disclosure.
- Strategy drift: Actual checks, stages, sectors, or concentration depart from the pitch without a clear approval trail.
- Ignored governance: Required LPAC review, key-person action, conflict approval, or extension process happens late or not at all.
- Reference resistance: The manager blocks reasonable independent calls or offers explanations that change across conversations.
Put the evidence next to the answer
An investment manager due diligence checklist works when it leaves a clear record. For each major claim, save the supporting document, data set, reference, or operating example. Record unresolved questions and decide which must be answered before commitment.
Emerging GPs can use the same structure to prepare. Keep a complete track record, documented attribution, coherent fund model, current policies, sample reporting, and candid explanation for items that do not exist yet. First-time managers will have young systems and missing history. LPs need enough evidence to judge whether the strategy and firm can hold up through a long, risky fund life.
Disclaimer: This material is for educational purposes only and is not legal, tax, accounting, investment, or valuation advice. Private-fund investments are speculative, illiquid, long-term, and can result in total loss. Past results and current marks do not guarantee future results. Outcomes depend on the governing documents, fees, expenses, carried interest, taxes, cap-table and security terms, valuation policy, and timing. Consult qualified independent professionals and review the governing documents before making any decision.











