
Co-investment rights for emerging fund managers and LPs
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Co-investment access can deepen a general partner’s relationship with a limited partner. A vague promise can damage it. Emerging managers need to say what an investor will receive, how scarce capacity will be allocated, and which costs and risks sit outside the main fund. Limited partners need the same clarity before they assign value to that access.
When the original series was written, Sam Loui worked at Sydecar and answered our questions about setting up funds and special purpose vehicles (SPVs).
What co-investment rights mean
A limited partner (LP) commits capital to a fund. The general partner (GP) invests that pooled capital across a portfolio. A co-investment gives an LP the chance to put an additional, separate check into a specific company alongside the main fund.
That last phrase matters. If the main fund is not investing in the transaction, the opportunity may be a direct deal from the manager’s network rather than a co-investment. The governing documents decide the label and the LP’s rights.
An LP’s contractual right and a GP’s allocation policy do different jobs. If an LP expects an enforceable right, it should appear in the limited partnership agreement (LPA) or a side letter and define the conditions that apply. Those rights can include:
- Notice or information: The GP must tell the LP about a qualifying opportunity or provide specified information. This alone creates no allocation.
- Evaluation or participation: The LP may evaluate a deal or request an allocation, subject to the conditions in the documents.
- Priority: The GP must consider or allocate to the LP before a stated group, using the order and limits in the documents.
- Reserved capacity: The GP must hold a defined amount or percentage for the LP when the stated conditions are satisfied.
A discretionary allocation policy is the GP’s framework for dividing capacity among the fund, affiliates, LPs, and other co-investors. It can describe eligibility, priorities, scaling, deadlines, and conflicts. The policy does not give a particular LP a contractual entitlement unless the LPA or a side letter incorporates that entitlement.
A fundraising deck that promises “co investment opportunities” leaves those distinctions unanswered. So does an informal handshake. “We expect to share selected opportunities” is a relationship intention. “The LP may review each qualifying opportunity” is an information right. “For each qualifying deal with at least $500,000 of co-investment capacity, the GP will reserve $100,000 for the LP until the stated response deadline” describes reserved capacity. The LPA or side letter still needs to define a qualifying deal, investor eligibility, funding requirements, and what happens when the available tranche is smaller.
Why GPs offer co-investment and why LPs care
A GP may use co-investment when a company has more room than the fund should take, given its size, ownership targets, concentration limits, or reserves. Extra capital can also help a manager participate in a larger round while keeping the main fund within its strategy.
For the LP, the appeal is deal-level choice. The investor can assess one company, increase exposure to a sector or stage, and observe how the manager underwrites a live opportunity. Some arrangements charge lower fees and lower carried interest than the main fund. Carried interest is the manager’s contractual share of investment profits. The documents need to confirm the percentage, calculation, and payment terms.
The strategic benefit is strongest when the GP explains why the main fund is taking its amount and why additional capacity exists. Without that explanation, an LP cannot tell whether the tranche reflects portfolio construction or a conflict.
“Decisions are never in isolation - they are a comparison game.” Elizabeth Yin, our co-founder and general partner, wrote those words in Democratizing Knowledge (Hustle Fund, 2021, p. 287). The same principle applies here. An LP should compare the specific company with its other uses of capital, and the GP should compare the proposed fund allocation with its mandate and remaining capacity.
How one deal can create three ownership paths
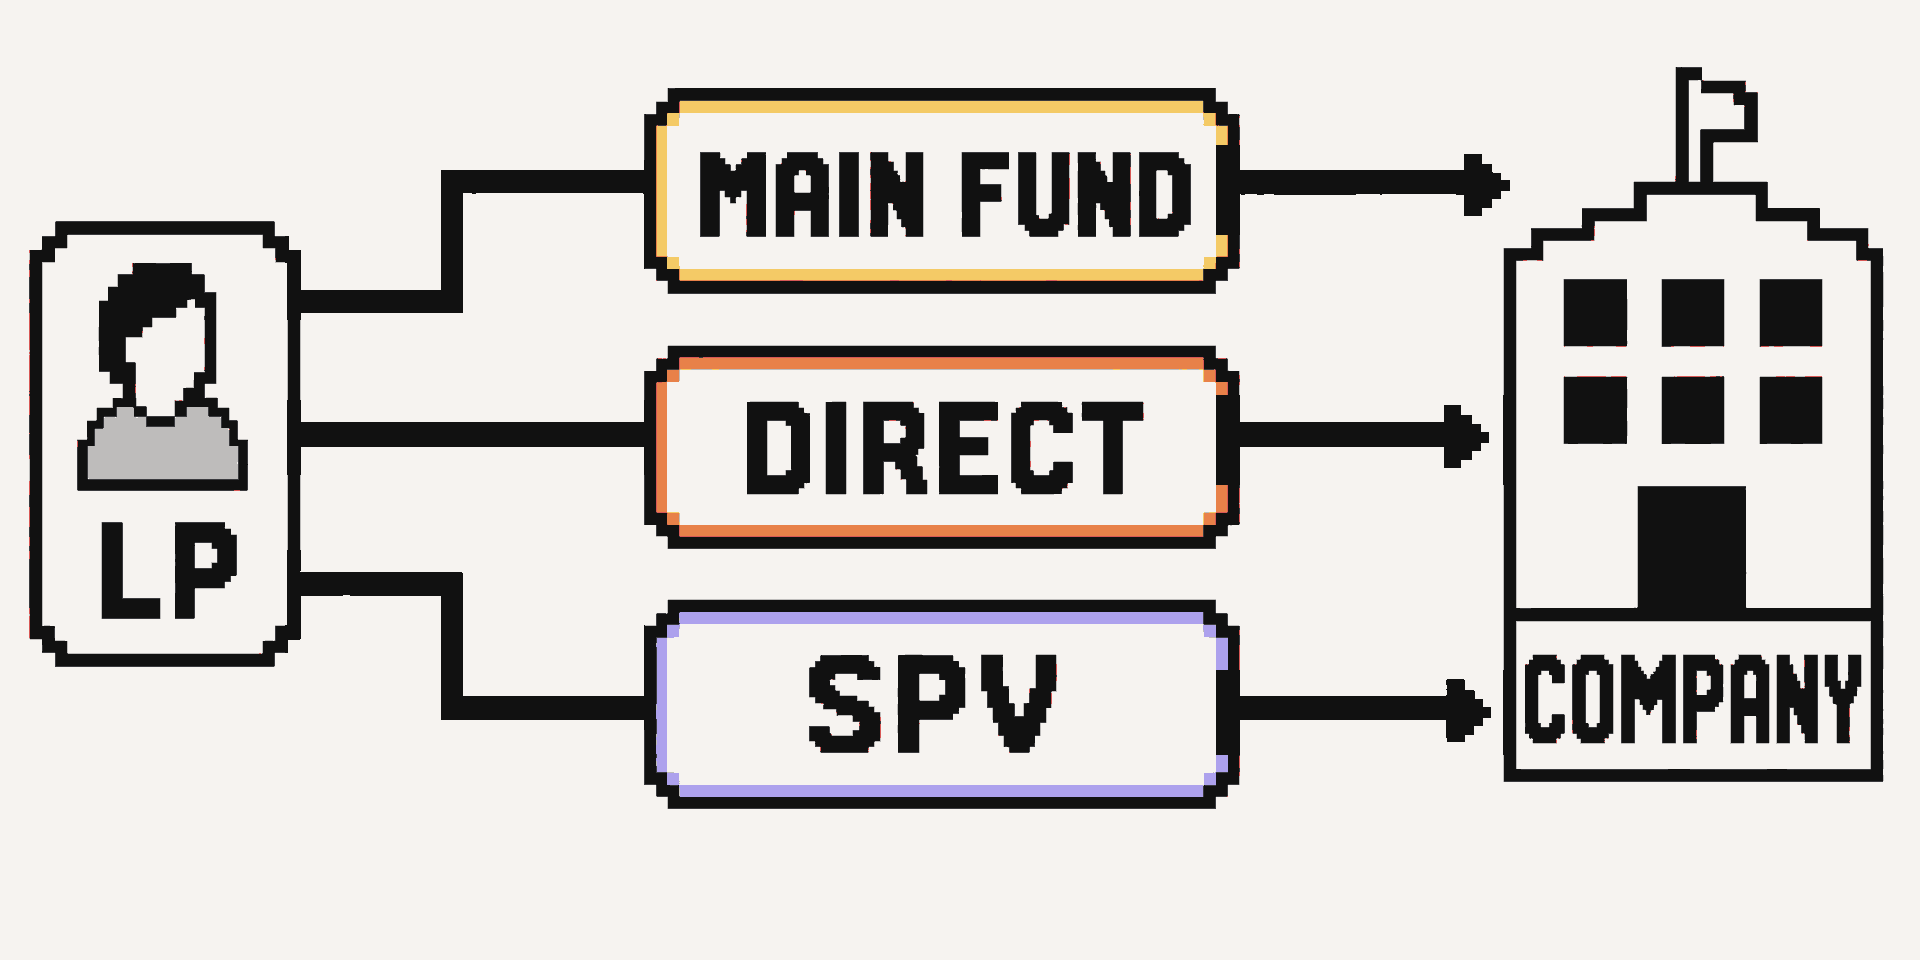
Consider a simplified example. A $20 million venture fund has room to invest $750,000 in a company under its portfolio model. The round gives the GP access to $1.25 million. The GP invests $750,000 through the main fund and makes the remaining $500,000 available under its co-investment policy.
The extra check can reach the company in two ways:
- Direct investment: The LP signs the company’s transaction documents and holds the security itself. The LP is responsible for its own funding, administration, tax work, and any investor obligations in those documents.
- SPV: The LP buys an interest in a separate vehicle, and that vehicle holds the company’s security. The SPV’s manager handles the vehicle, while its governing documents set fees, carried interest, expenses, voting, reporting, transfers, and distributions.
Both routes are separate from the LP’s main fund commitment. The security and valuation may match the fund’s terms, but that result is not automatic. Different closing dates, information rights, tax treatment, transfer limits, or follow-on rights can produce a different economic experience.
A clean process usually follows this order:
- Size the main fund’s investment. Apply the fund strategy, concentration limits, ownership target, reserves, and available capital.
- Document why extra capacity exists. Record why the amount belongs outside the main fund and whether the GP or an affiliate receives separate economics.
- Send a complete invitation. Give eligible LPs the investment memo, key risks, proposed security, valuation, route, minimum check, economics, deadline, and known conflicts.
- Allocate and close. Apply the stated priority and oversubscription rules, complete eligibility checks, and sign the deal-specific documents.
- Administer the investment. Deliver reporting, allocate expenses, manage follow-ons, and distribute proceeds under the applicable documents.
The GP should avoid marketing a deal before steps one and two are settled. Otherwise, investor demand can start influencing how much capital the main fund receives.
Define the allocation policy before a deal gets crowded
Demand often exceeds the available tranche. That is when a relationship benefit can turn into a trust problem.
The Institutional Limited Partners Association (ILPA) Principles say GPs should disclose in advance to all LPs, through the private placement memorandum, LPA, and relevant regulatory filings, a written framework for allocating co-investment opportunities, interests, and expenses, including whether any prioritization applies. The framework should describe how conflicts and transaction-specific risks will be disclosed or mitigated.
ILPA also says opportunities that fit the fund’s strategy should first be allocated to the fund when it has available commitments. The GP should explain why a co-investment tranche exists. When side letters grant rights to evaluate or participate pro rata, ILPA says the GP should disclose the existence of those arrangements to all LPs, along with differentiated economics and the allocation of follow-on investments.
An emerging manager’s written policy should answer:
- Which deals qualify, including stage, geography, check size, and whether the main fund must invest.
- How the GP determines the main fund’s allocation before creating a separate tranche.
- Which LPs are eligible, which LPA or side-letter provisions create contractual priority or reserved capacity, and where the GP retains discretion.
- How strategic factors such as speed, sector knowledge, or portfolio-company value are weighed.
- How oversubscribed deals are scaled, such as pro rata by requested amount, fund commitment, or a stated tier.
- What happens when an LP misses a response or funding deadline.
- Which vehicle, legal, tax, broken-deal, and transaction expenses each participant bears.
- How follow-on capacity will be divided between the fund and co-investors.
A GP should use preferential allocation only when the governing documents permit it, disclosures explain it, the policy is applied consistently, and material conflicts receive the review required by the fund’s documents and policies. The GP may reasonably value an LP that can decide in 48 hours or help a portfolio company enter a regulated market. The invitation should make that basis clear enough for other eligible LPs to understand the process.
Record every offer, request, allocation, decline, and reallocation. In a private fund risk alert, U.S. Securities and Exchange Commission staff described observed cases where advisers applied allocation processes inconsistently with disclosure or allocated shared expenses contrary to policy and governing documents. A contemporaneous allocation log gives the GP evidence that its practice matched its promise.
Economics are deal terms, not a perk
Co-investment is often described as “no fee, no carry.” That can be one structure, but it is not the definition.
Depending on the route and documents, an LP may pay:
- An annual management fee or a one-time setup or administration fee.
- Carried interest on profits after returning capital, according to the vehicle’s distribution terms.
- Legal, formation, tax preparation, audit, banking, platform, and regulatory costs.
- Transaction expenses and a share of costs from a deal that fails to close.
The base for each charge matters. A management fee might apply to committed capital, invested capital, or another stated amount. For carried interest, confirm when contributed capital is returned, which profits the percentage applies to, and whether the calculation covers each investment separately or the whole vehicle. Expenses can reduce net proceeds even when stated fees are zero.
The LP also needs to understand governance. Who votes the security? Who consents to amendments? What reporting reaches a direct holder or SPV member? Can the manager transfer the asset, extend the vehicle, recycle proceeds, or call additional capital? What happens if the company raises a bridge round?
None of those answers can be inferred from the fund’s LPA alone. The subscription agreement, the SPV’s governing documents, company documents, and offering materials control the separate investment.
LP diligence before relying on the right
The ILPA due diligence questionnaire asks managers to describe their allocation policy, indicate whether contractual co-investment arrangements exist, describe historical examples, and report fees and carried interest. For predecessor funds, it separately asks whether past co-investments were syndicated and whether any involved co-underwriting before signing. Those questions form a useful baseline.
An LP should ask:
- Is this a right to information, an invitation, priority, or reserved capacity?
- Which deals qualify, and must the main fund participate?
- How does the GP size the main fund’s check before offering the rest?
- Which side-letter or strategic rights affect priority?
- How are oversubscribed requests, missed deadlines, and unused allocations handled?
- Will the investment be direct or through an SPV, and which security will each route hold?
- What are all fees, carried interest, expenses, and broken-deal obligations?
- What information, voting, transfer, reporting, and follow-on rights come with the investment?
- How much time will the LP have to decide and fund, and what investor-eligibility checks apply?
- How has the policy worked in practice, including opportunities offered, accepted, scaled, or changed?
Historical detail is more useful than a count of past deals. Ask for an anonymized example showing the main fund’s allocation, co-investment capacity, eligible requests, scaling method, final allocations, economics, and timeline. The example exposes whether the stated policy is operational or aspirational.
The risks sit outside the sales pitch
For an LP, a co-investment adds single-company concentration. The company can fail and the investment can go to zero. The security may remain illiquid for years. A short response window can compress diligence, and an SPV adds a second set of documents, expenses, reporting, and tax administration.
Access also creates selection risk. The LP sees the deals the GP decides to share, under the circumstances the GP chooses. A large co-investment tranche might exist because the fund reached a concentration limit, because another investor dropped out, or because the round expanded. Each reason changes the questions the LP should ask. Lower fees do not repair weak underwriting.
For a GP, the risks include conflicts over allocation, the appearance of favoring influential LPs, misallocated expenses, confidentiality leaks, administrative burden, and missed closing deadlines. Separate carry or fees can intensify the conflict if the GP controls how much of a deal goes to the main fund versus an affiliate vehicle.
“The more disciplined you are in your thought process/rubric, the more you can improve over time.” Elizabeth Yin wrote that in Democratizing Knowledge (Hustle Fund, 2021, p. 131). For GPs, the rubric is the allocation policy and the record of how it was applied. For LPs, it is the deal-specific underwriting process. Relationship enthusiasm should not override either one.
Make access part of the relationship
Co-investment rights work when both sides know what will happen before a competitive deal arrives.
GPs should describe access narrowly, prequalify interested LPs, settle the main fund’s allocation first, disclose the economics and conflicts, and keep an allocation record. LPs should separate relationship value from investment merit, maintain a deal-level diligence process, and reserve enough time and capital for follow-ons and administration.
The strongest promise is a process the manager can repeat consistently. It gives an LP useful access while protecting the main fund and the broader partnership.
Before the next fundraise, use our guide to the questions LPs ask fund managers to pressure-test your deal flow, fund differentiation, and support for founders.
This material is for educational purposes and is not legal, tax, accounting, or investment advice. Fund managers and investors should consult qualified legal, tax, and other professional advisers about their documents, obligations, and circumstances.











