
Fund audit 101: What auditors examine and how to prepare
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
A fund audit is an independent examination of an investment fund’s financial statements. If you’re managing a first fund or investing as a limited partner, the process can feel like a pile of requests with no clear purpose. Understanding the audit’s scope, the people involved and the records they need makes that pile easier to organize.
What a fund audit covers
The auditor expresses an opinion on the fund’s financial statements as a whole under the applicable accounting framework. Those statements describe the fund’s financial position and activity, including its investments, cash, expenses and investor capital. The accompanying notes explain accounting policies and other relevant disclosures.
The auditor seeks reasonable assurance that the statements are free from material misstatement caused by fraud or error. A material misstatement is an error or omission significant enough to affect a reader’s decisions.
Reasonable assurance is a high level of assurance, with limits. The American Institute of Certified Public Accountants describes risk-based audit procedures and the use of sampling, rather than examining every transaction.
A fund audit doesn’t certify each portfolio company’s health, establish an exact sale price for each investment or endorse the manager’s investment choices. It also doesn’t guarantee that all fraud has been detected.
The output is the auditor’s report together with the audited financial statements and notes. The number of pages depends on the fund. For a limited partner (LP), the opinion and the notes belong together: the opinion gives assurance about the statements, while the notes explain how the reported numbers were prepared.
Who does what during the audit?
The fund manager, fund administrator and independent auditor have different jobs.
- Fund manager: Takes responsibility for the financial statements, accounting judgments and information supplied to the auditor. Hiring an administrator doesn’t transfer that responsibility away from management.
- Fund administrator: Helps maintain the books, prepare schedules and financial statements, and organize supporting records within the scope of its engagement. Our explanation of fund administration covers investor reporting and capital calls, the requests for investors to send committed money.
- Independent auditor: Plans and performs audit procedures, evaluates the evidence and issues the audit opinion. The auditor determines what evidence is needed, which can include information obtained directly from outside parties.
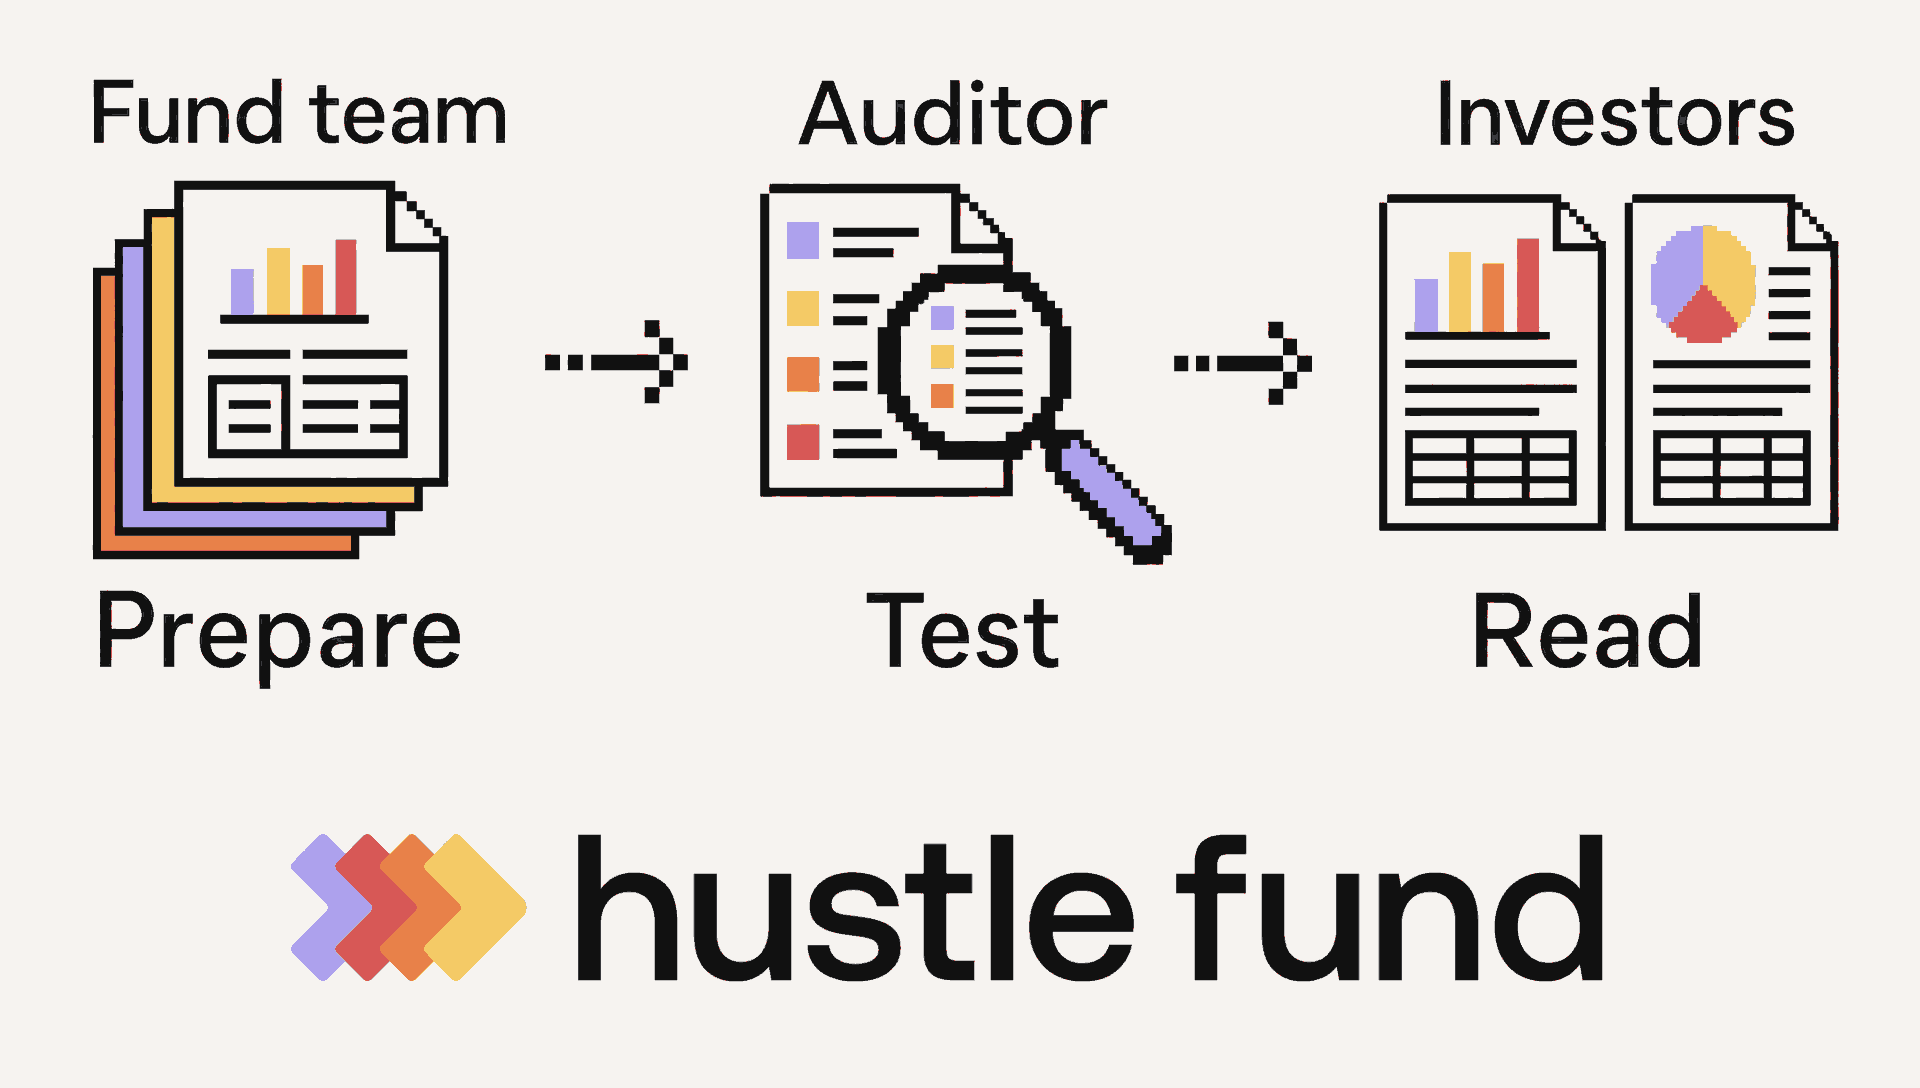
At Hustle Fund, gathering information from founders has been part of our team’s audit preparation. Quarterly portfolio reporting has helped us keep information organized for the annual process. Those updates support preparation; they don’t provide the assurance of an independent audit.
How to prepare for a fund audit
Preparation starts with a shared timetable and the auditor’s prepared-by-client request list, often shortened to PBC list. It identifies the records and schedules the fund team needs to supply. The list varies with the fund’s structure, investments and audit risks.
Agree on who owns each request, when it’s due and who handles follow-up questions. Keep one version of the request tracker so your administrator and investment team aren’t answering the same question separately.
Organize the records behind the numbers
A useful starting pack has five parts. The auditor’s specific requests determine what you’ll need for the engagement.
- Fund and investor documents. Assemble the limited partnership agreement, which governs the fund, along with subscription agreements, side letters and amendments. A side letter records additional terms agreed with a particular investor.
- Books and cash records. Organize the general ledger, the detailed accounting record, and the trial balance, its account-balance summary. Include bank or custody statements and reconciliations that explain how the records agree.
- Capital activity, fees and expenses. Keep support for investor contributions, distributions, management fees and fund expenses, including how income and expenses are allocated to partners. Include the calculations and supporting agreements or invoices.
- Investment and valuation support. Assemble signed investment documents, transaction records, available company information and the manager’s documented basis for reported investment values. Keep the reporting date clear.
- Reviews and changes. Retain evidence of approvals and reviews. Flag unusual transactions, dealings with the manager or its affiliates, and significant events after year-end for discussion with the auditor.
CBIZ’s first-audit guidance stresses supported investment transactions and allocations consistent with fund documents. A spreadsheet total is easier to explain when the signed agreement, cash movement and accounting entry are organized together.
Leave time for questions and completion
Once the records are available, the auditor performs procedures and follows up on gaps, differences or significant judgments. Supplying the initial pack doesn’t mean the audit is finished. Management may need to explain an assumption, provide another document or address a proposed adjustment.
Reserve time for the final financial statements, remaining questions and the management representation letter, which contains management’s written representations to the auditor. Wipfli’s audit completion guidance includes these closing tasks alongside its recommendations for organized records and documented reviews.
For an LP receiving the finished package, the reporting period and valuation notes matter. An unrealized investment value is an estimate for a holding the fund still owns. It isn’t cash distributed to investors or a promise of what an exit will produce.
Why the process can take so much time
At our February 2023 team offsite, fund-audit discussions generated enough frustration that I wanted to retreat to the kitchen and eat cookies. Collecting information across our portfolio was a real operational burden.
In our experience, founder follow-ups could stretch over months. Some founders weren’t sending regular investor updates, so our team had to chase information while also sourcing investments and supporting companies. That’s our experience, rather than a standard audit duration.
The practical lesson is to make record collection part of ongoing portfolio work. Keep financing documents when transactions happen and retain company updates with their dates. Missing records are harder to reconstruct under a year-end deadline.
Audit fees also belong in the fund’s operating plan. Our co-founder and general partner Elizabeth Yin wrote in Democratizing Knowledge (Hustle Fund, 2021): “Not all $10m will necessarily go into funding startups.” Fund capital can cover expenses as well as investments. The fund’s governing documents determine which expenses it bears, and an audit budget needs to reflect the actual engagement scope.
Why venture investment valuations need supporting evidence
Private startup investments often lack a publicly traded price. Management has to support the values reported in the fund’s statements, and the auditor evaluates that support.
Fair value is the estimated price for selling an investment in an orderly transaction between market participants at the measurement date. The Financial Accounting Standards Board’s fair-value framework ties the measurement to the asset’s characteristics and market conditions at that date. A portfolio company’s headline valuation and the value of the fund’s holding are different figures.
A recent financing can provide evidence, but its share price doesn’t automatically establish the current fair value of every investment in that company. The investment held, its terms and changes since the transaction matter. Later-stage investments still require judgment; a priced round doesn’t make the audit a spreadsheet exercise.
At Hustle Fund, our early-stage portfolio work has included gathering information about revenue, fundraising and cash burn to help support valuation discussions. Cash burn describes how quickly a company spends its cash. The relevant evidence depends on the investment and the circumstances.
A founder’s failure to respond creates an information gap. It doesn’t, by itself, establish a lower value. Management and the auditor need to address the missing evidence and its implications for the financial statements and audit. An automatic markdown rule would confuse an evidence problem with a valuation conclusion.
Why funds get audited
The obligation can come from fund agreements, investor requirements or applicable regulation. Being small, investing early or having no exits doesn’t settle the question.
Fund documents and LP expectations
A fund’s limited partnership agreement or other governing documents may require audited financial statements. Investors can also make an audit a condition of investing. These expectations can matter for individual and family-office investors as well as institutions.
For a manager raising another fund, a history of audited fund statements can support investor diligence. It shows a history of independent financial reporting. It doesn’t prove that the manager chose good companies or that the next fund will perform well.
The SEC custody-rule audit route
The federal rules depend on the adviser’s circumstances. Some private-fund advisers qualify for exemptions from registration with the U.S. Securities and Exchange Commission (SEC). These SEC registration exemptions don’t remove contractual obligations or every other legal requirement.
For advisers registered, or required to register, with the SEC that have custody of client assets, the SEC custody rule has an audit route for certain pooled investment vehicles. Custody includes holding client assets or having authority to obtain possession of them. A qualifying annual audit replaces the annual surprise examination, an unannounced asset examination, and certain other requirements. Other custody safeguards remain relevant.
That route has conditions concerning auditor independence and eligibility, the financial statements and their delivery. The ordinary delivery deadline is 120 days after the fund’s fiscal year-end. The SEC’s custody guidance describes specific conditions and limited exceptions. That deadline isn’t a universal audit calendar for every venture fund.
The separate private-fund audit rule adopted in 2023 was vacated in June 2024. It isn’t a current blanket audit mandate. Fund counsel and the independent auditor can establish the applicable requirements and timetable for the fund’s actual structure.
A financial-statement audit is separate from tax preparation
Audited statements and tax filings can draw on the same underlying records, and the audit work may inform tax preparation. They remain separate deliverables.
For a fund taxed as a partnership, Form 1065 reports partnership tax information, and Schedule K-1 reports each partner’s share of relevant items. The Internal Revenue Service’s partnership tax instructions explain that partners include those items in their own returns. A K-1 doesn’t determine an LP’s entire tax bill; the investor’s circumstances also matter.
The audit opinion doesn’t replace the tax return or K-1. Nor is an audit a universal prerequisite for partnership tax preparation: the Schedule M-3 instructions for reconciling financial and tax reporting explicitly accommodate unaudited statements and, in some circumstances, the partnership’s books and records.
On a personal note
The back-office cost of running a fund has frustrated our team. We want more people to learn how startup investing works, and the administrative burden can make that harder.
Elizabeth Yin put the access problem plainly in Democratizing Knowledge (Hustle Fund, 2021): “Infrastructure costs impede progress.” She was discussing legal, accounting and audit overhead in investing. That concern is part of why we care about investor education.
If you want to build your investing judgment before deciding whether to run a fund, apply to Angel Squad. Our community combines startup-investing education and peer learning with Hustle Fund’s investing experience. It doesn’t replace a fund’s auditor, administrator or independent advisers.
This is educational information, not investment, legal, tax, accounting or valuation advice. Seek independent review from qualified legal, tax and accounting professionals for your circumstances. Startup investments are speculative, illiquid and long-term, and you can lose all your capital. Most startup bets may fail. Past results and current investment values don’t guarantee future results.











