
Haley Bryant, Hustle Fund Partner: 4 first-year lessons
Brian Nichols is the co-founder of Angel Squad, an angel investing community where aspiring and active angels learn from Hustle Fund’s approach, review curated deal flow, and connect with peers.
Today, Haley Bryant is a Partner at Hustle Fund. In 2020, she was an operator making her first angel investments and learning where instinct helped and where it fell short. Brian Nichols spoke with Haley in 2024 about that first year. Her account gives new angels a candid look at how an investment process takes shape after the check is written.
How Haley made her first angel investment
In her 2024 conversation with Brian, Haley traced her start back to summer 2020. She was working at a content marketing company when a teammate told her that he was thinking about starting a business.
Haley knew his work ethic, operating ability, and knowledge of the market. She had never made a startup investment or seen a term sheet, yet she offered to invest and encouraged him to pursue the company full time.
That company was Sacra, a private markets research business. Haley told Brian that Sacra's research helped her learn about business quickly. Its community also introduced her to founders, operators, and investors who later became part of her network.
Haley described that first investment as lucky. A trusted relationship gave her access and conviction, while her investment process was still taking shape. She then made 15 investments during her first year, based on her account. That number describes her 2020 experience, not a target for someone else's portfolio.
One promising first bet can create too much confidence. Portfolio construction matters because early-stage outcomes are uncertain and losses are common. We explore that risk in our case for spreading your bets. Elizabeth Yin makes the same point in Democratizing Knowledge: “Don't try to pick a co. Select a portfolio.”
Four lessons from Haley's first year
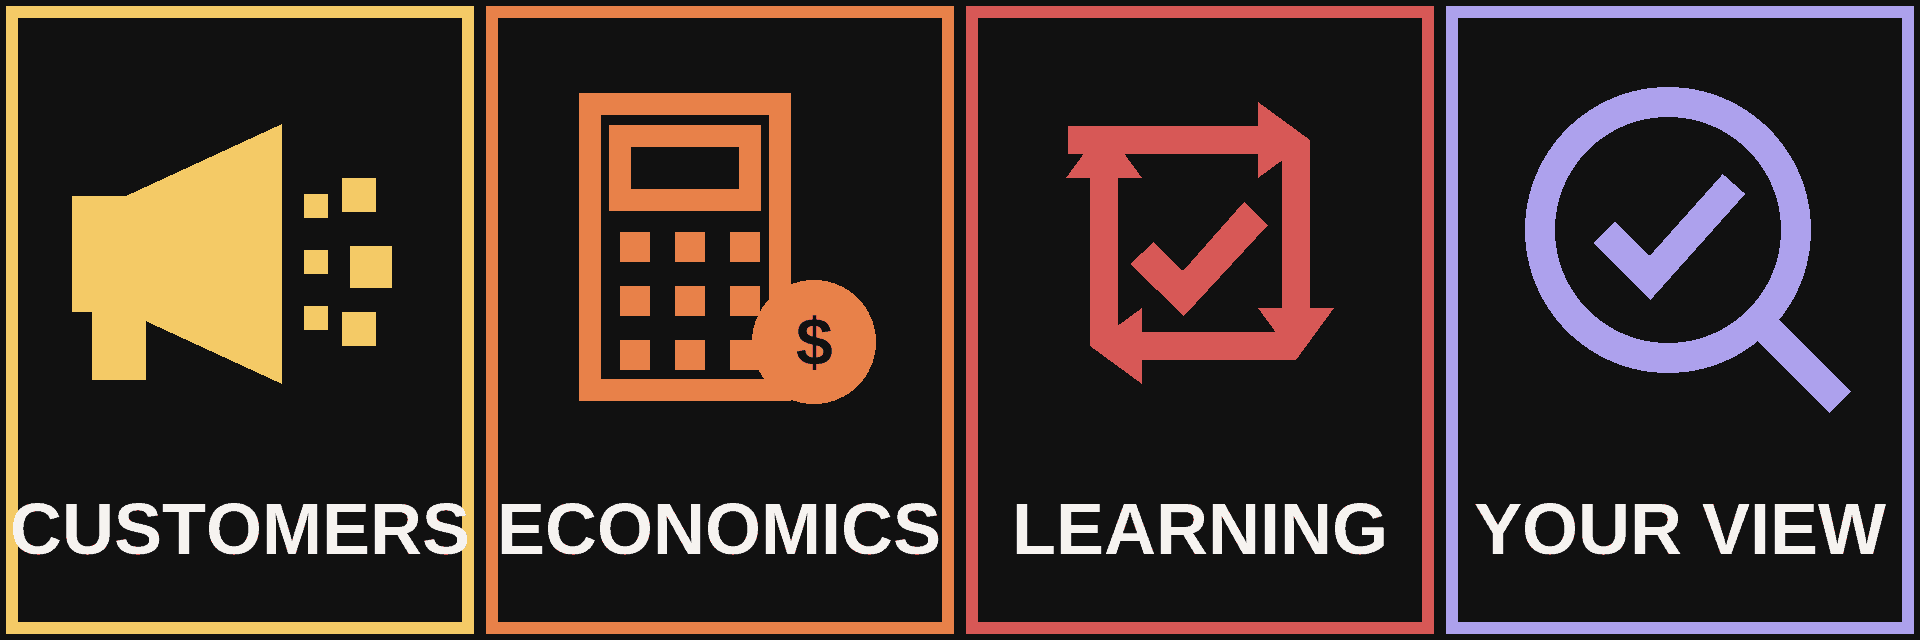
The examples below describe investments Haley made in 2020 and details she shared with Brian in 2024. They are retrospective observations, not universal rules. Together, they give investors four lenses for a founder call: customer acquisition, unit economics, founder learning, and independent diligence.
1. B2C customer acquisition needs a credible path to scale
One company Haley backed was building an upskilling platform for people stuck in jobs with little upward mobility. She loved the mission. The early customer-acquisition motion was the hard part.
The founders had to sell the product to each person individually. That work took time and brought in relatively little revenue. In Haley's account, the company showed her how quickly a compelling business-to-consumer idea can run into a distribution constraint.
Her lesson was narrower than “avoid B2C.” She began looking for a founder with relevant marketing experience, the willingness to hear “no” repeatedly, and a plan to turn those conversations into better tests. Before investing, an angel can ask:
- Channel: How are customers finding the product today?
- Retention: What evidence shows that they keep using or paying for it?
- Scale: What must change for growth to outpace acquisition cost?
Customer acquisition cost (CAC) is the amount a company spends to win one customer. A low early CAC can still mislead if it comes from the founders' personal networks or a channel that cannot support much more volume. The useful signal is a believable path from early adoption to repeatable distribution.
2. Unit economics deserve early scrutiny
Haley also invested in a grocery-delivery company during 2020. Demand for delivery was easy to see during the pandemic, and she found the team and technology compelling. The business later taught her to examine the economics of each order much earlier.
Unit economics describe the revenue and direct costs tied to one customer, order, or delivery. A company can grow its top-line revenue while losing money on each additional transaction. Grocery delivery also adds practical questions about picking, packing, driver time, route density, refunds, and promotions.
Haley's takeaway was to avoid assuming that scale will repair weak margins. An investor can ask what one order contributes after variable costs, how repeat behavior changes that result, and which costs improve with density. If the answer depends on permanent discounts or an untested operational leap, the model still has work to do.
3. Founder resilience shows up as learning velocity
Two companies from Haley's 2020 portfolio shaped how she thinks about grit. By the time of her 2024 conversation with Brian, one team had tried 11 ideas before landing on its then-current product. Another rebuilt its product from the ground up almost two years after starting.
The second founder also sent monthly investor updates. He documented the experiments the team had run and what they learned. Those updates gave Haley evidence of movement, even when the product itself was changing.
This is a more useful version of resilience than stubborn persistence. Haley learned to look for founders who run customer discovery, change their approach when evidence calls for it, and explain what changed. Endurance alone is weak evidence. A fast learning loop gives an investor something concrete to assess.
4. Independent diligence beats borrowed conviction
In another 2020 deal, a friend introduced Haley to a founding team that the friend had already backed. Haley liked the founders and saw a need for the product. She did not know the market well, and she invested without building an independent view of the company.
The company later closed, according to Haley's 2024 account. A referral from someone you respect can help a company reach your inbox. It cannot answer whether the customer need is urgent, the economics work, or the team has evidence behind its plan.
A repeatable rubric makes that independent work easier. As Elizabeth Yin wrote in Democratizing Knowledge, “The more disciplined you are in your thought process/rubric, the more you can improve over time.” For each deal, write down what you believe about the customer, distribution, economics, and team. Record what evidence supports each belief. Then make your own decision.
Build your own investment rubric
Haley's first year shows how useful experience becomes when you turn it into a process. If you want to review curated deal flow, compare your reasoning with peers, and build your own diligence habits, apply to Angel Squad.
This material is for educational purposes only. It is not investment advice or a recommendation to buy or sell any security. Startup investments are speculative, illiquid, and long-term, and you could lose your entire investment. Past outcomes do not guarantee future results.











